Blog

  • Why the SEC will Ultimately Deny VanEck’s Third Application for a Bitcoin Spot ETF and What it Means for Digital Assets

    Late last month, August 2022, the SEC announced a 45-day delay to rule on VanEck’s third Bitcoin Spot ETF application. This comes on the heels of the SEC denying Grayscale’s GBTC – an SEC backed Bitcoin Trust – conversion to a spot ETF, as well as Bitwise Asset Management’s application for a spot ETF, on the same day in late June 2022. VanEck currently has an SEC-backed Bitcoin futures ETF, the “VanEck Bitcoin Strategy ETF” (Cboe: XBTF). Their two previous applications for a Bitcoin spot ETF were rejected first in 2017, then late in 2021. VanEck is considered somewhat of an “investment giant”, with roughly $65B currently in AUM.

    Grayscale, with roughly $20M in AUM and a digital asset manager giant themselves, a subsidiary of Digital Currency Group (DCG) – who’s also the parent company of CoinDesk – sued the SEC immediately after they rejected the GBTC’s conversion from a SEC-backed Bitcoin Trust to a SEC-backed spot ETF. A ruling from a Federal Appellate Court is expected sometime in Q4 2023 or Q1 2024.

    Why Will the SEC Reject VanEck’s Application for a Bitcoin Spot ETF a Third Time?

    A better way to phrase the question is: why wouldn’t they? Has anything dramatically changed about either the SEC’s mandates, Bitcoin, market conditions, or is VanEck’s application unique? No, for all the above. VanEck’s Bitcoin spot ETF, which they’ve proposed to list on the Cboe BZX Exchange, would still create direct Bitcoin ownership for investors who purchased it. In my opinion, the SEC’s had to issue a 45-day delay because VanEck’s argument appears to differ from Grayscale’s. VanEck isn’t relying on a futures versus spot Exchanged Traded Fund [ETF] derivative comparison. Rather, they’re urging the SEC to reconsider because investors can access Bitcoin spot ETFs through our neighbors in Canada.

    They’re not wrong. As early as February 2021, Canada became one of the first countries in the world to place a Bitcoin spot ETF on one of their national exchanges. But given that was back in February 2021, the question remains: what’s changed? It’s completely unrealistic for the SEC to admit they weren’t aware of a Bitcoin spot ETF on a Canadian exchange. Hypothetically, it would very likely give Grayscale the green light to pursue further, more substantial legal action against the SEC.

    At the time Grayscale’s GBTC was rejected, many analysts cited the heightened potential for fraud and malpractice amongst digital assets being a key reason institutional investors, who generally purchase far more spot products than futures derivatives (as part of their traditional investment strategies), should not get access to an SEC-backed Bitcoin spot ETF yet. They said digital currency exchanges needed total transparency inside their marketplaces, like the DOW and NASDAQ. While this flies in the face of many reasons investors purchase digital assets and it’s not practical, it didn’t matter. That’s what the institutional investor community who was with the SEC just two months back demanded. VanEck is not purely a digital asset manager like Grayscale and in terms of AUM, they’re over 3 times larger.

    As another interesting reference point VanEck currently has 3 CO (Commodity) ETFs. The first is XBFT (Bitcoin Strategy ETF) and the second is OUNZ (VanEck Merk Gold ETF). XBFT has $19.2M in total net assets, while OUNZ has $600.4M. Interestingly, VanEck offers 65 EFT products and only 3 fall in the Commodities Asset Class. The other 62 are split between Fixed Income (Corporate, International, & Municipal Bonds, Rates products, etc.) and Equity ETFs. VanEck’s GDX has $9.4B in total net assets, while their ITM has 1,939 holdings (September 2, 2022). The XBFT has just $19.2M in total net assets and only 8 people holding it (September 2, 2022). Of the roughly $65B VanEck has in AUM, XBFT – a Bitcoin futures ETF – represents around .002% of their investment portfolio.

    Concisely, VanEck is a bigger, more established firm that has broader appeal to institutional investors already compared to Grayscale, who owns roughly 3.5% of all of Bitcoin and is purely a digital asset manager. They have the first SEC-approved Bitcoin Trust ETF with GBTC, trading on the NASDAQ. They are doing their best to bring digital assets to institutional investors. That’s why they’ve gone all out for a Bitcoin spot ETF, whereas VanEck seems to have strategically made a push when they’ve felt they had a compelling case.

    Does the SEC’s 45-Delay Mean VanEck has a Real Chance?

    I believe it means they have a better chance, but will ultimately suffer the same fate as Grayscale and Bitwise. I don’t even think it gives them much of a better chance; only if the SEC makes an unexpected blunder. Nothing has changed about their concerns related to GBTC that would warrant VanEck’s application to get approved.

    “The Commission [SEC] finds that it is appropriate to designate a longer period within which to take action on the proposed rule change so that it has sufficient time to consider the proposed rule change and the issues raised therein.”
    -SEC Spokesperson, in a letter to VanEck (August 2022)
    Tweet

    The verbiage in this quote seems to be hinting that the SEC is actually considering accepting VanEck’s argument. However, the SEC issuing a delay on a ruling isn’t exactly breaking news. They’ve shot down over a dozen attempts at a Bitcoin spot ETF in the last 12-month calendar year alone. There is no new information to indicate Bitcoin is any less susceptible to fraud – thereby posting inherent investor risk – than two months ago. The SEC is buying time in hopes of making a more compelling case regarding Bitcoin spot ETF’s in Canadian markets. What’s going to make more headlines in 45 days, the macroeconomic conditions from rising rates, inflation, and other recessionary indicators, or the SEC rejected the 15th (or so) Bitcoin spot ETF in the last year? After all, the SEC isn’t completely unaware of the current dynamics in financial markets.

    If VanEck is Ultimately Denied, What Does that Mean for Cryptocurrency?

    The overall impact is unlikely to be large, unless the SEC gets unpredictable here. Assuming they stay consistent with their rationale, this matter will go back to the DC Appellate Courts. But if you’re an institutional investor of SEC-approved Bitcoin assets, you’re not going to be majorly impacted by this. Inflation and rising interest rates? That will likely negatively impact at risk assets across the board and digital assets are certainly in that category. But the long-term ramifications for Bitcoin from this latest SEC ruling are likely to be very minimal.

    Just to end with a key point we just touched on, watch out for at risk assets considering this is very likely going to be the realest felt recession since 2008. There won’t be a major economic downturn because we’ve learned our lessons from 2008, but investors will sell off at-risk assets as soon as financial markets show signs of destabilization. Digital assets in an investor’s portfolio will be one of the first to go. Combined with the seasonality of Bitcoin slumps, expect the price to drop below 15,000 and who knows how much lower. How much lower would it take for the strongest crypto asset enthusiasts to wave the red flag? Would that ever happen? Only time will tell, but again, considering we have a lot of indications a recession is coming, taking a bullish position on Bitcoin in the short-term is unwise at best.
  • Why the SEC will Ultimately Deny VanEck’s Third Application for a Bitcoin Spot ETF and What it Means for Digital Assets

    Late last month, August 2022, the SEC announced a 45-day delay to rule on VanEck’s third Bitcoin Spot ETF application. This comes on the heels of the SEC denying Grayscale’s GBTC – an SEC backed Bitcoin Trust – conversion to a spot ETF, as well as Bitwise Asset Management’s application for a spot ETF, on the same day in late June 2022. VanEck currently has an SEC-backed Bitcoin futures ETF, the “VanEck Bitcoin Strategy ETF” (Cboe: XBTF). Their two previous applications for a Bitcoin spot ETF were rejected first in 2017, then late in 2021. VanEck is considered somewhat of an “investment giant”, with roughly $65B currently in AUM.

    Grayscale, with roughly $20M in AUM and a digital asset manager giant themselves, a subsidiary of Digital Currency Group (DCG) – who’s also the parent company of CoinDesk – sued the SEC immediately after they rejected the GBTC’s conversion from a SEC-backed Bitcoin Trust to a SEC-backed spot ETF. A ruling from a Federal Appellate Court is expected sometime in Q4 2023 or Q1 2024.

    Why Will the SEC Reject VanEck’s Application for a Bitcoin Spot ETF a Third Time?

    A better way to phrase the question is: why wouldn’t they? Has anything dramatically changed about either the SEC’s mandates, Bitcoin, market conditions, or is VanEck’s application unique? No, for all the above. VanEck’s Bitcoin spot ETF, which they’ve proposed to list on the Cboe BZX Exchange, would still create direct Bitcoin ownership for investors who purchased it. In my opinion, the SEC’s had to issue a 45-day delay because VanEck’s argument appears to differ from Grayscale’s. VanEck isn’t relying on a futures versus spot Exchanged Traded Fund [ETF] derivative comparison. Rather, they’re urging the SEC to reconsider because investors can access Bitcoin spot ETFs through our neighbors in Canada.

    They’re not wrong. As early as February 2021, Canada became one of the first countries in the world to place a Bitcoin spot ETF on one of their national exchanges. But given that was back in February 2021, the question remains: what’s changed? It’s completely unrealistic for the SEC to admit they weren’t aware of a Bitcoin spot ETF on a Canadian exchange. Hypothetically, it would very likely give Grayscale the green light to pursue further, more substantial legal action against the SEC.

    At the time Grayscale’s GBTC was rejected, many analysts cited the heightened potential for fraud and malpractice amongst digital assets being a key reason institutional investors, who generally purchase far more spot products than futures derivatives (as part of their traditional investment strategies), should not get access to an SEC-backed Bitcoin spot ETF yet. They said digital currency exchanges needed total transparency inside their marketplaces, like the DOW and NASDAQ. While this flies in the face of many reasons investors purchase digital assets and it’s not practical, it didn’t matter. That’s what the institutional investor community who was with the SEC just two months back demanded. VanEck is not purely a digital asset manager like Grayscale and in terms of AUM, they’re over 3 times larger.

    As another interesting reference point VanEck currently has 3 CO (Commodity) ETFs. The first is XBFT (Bitcoin Strategy ETF) and the second is OUNZ (VanEck Merk Gold ETF). XBFT has $19.2M in total net assets, while OUNZ has $600.4M. Interestingly, VanEck offers 65 EFT products and only 3 fall in the Commodities Asset Class. The other 62 are split between Fixed Income (Corporate, International, & Municipal Bonds, Rates products, etc.) and Equity ETFs. VanEck’s GDX has $9.4B in total net assets, while their ITM has 1,939 holdings (September 2, 2022). The XBFT has just $19.2M in total net assets and only 8 people holding it (September 2, 2022). Of the roughly $65B VanEck has in AUM, XBFT – a Bitcoin futures ETF – represents around .002% of their investment portfolio.

    Concisely, VanEck is a bigger, more established firm that has broader appeal to institutional investors already compared to Grayscale, who owns roughly 3.5% of all of Bitcoin and is purely a digital asset manager. They have the first SEC-approved Bitcoin Trust ETF with GBTC, trading on the NASDAQ. They are doing their best to bring digital assets to institutional investors. That’s why they’ve gone all out for a Bitcoin spot ETF, whereas VanEck seems to have strategically made a push when they’ve felt they had a compelling case.

    Does the SEC’s 45-Delay Mean VanEck has a Real Chance?

    I believe it means they have a better chance, but will ultimately suffer the same fate as Grayscale and Bitwise. I don’t even think it gives them much of a better chance; only if the SEC makes an unexpected blunder. Nothing has changed about their concerns related to GBTC that would warrant VanEck’s application to get approved.

    “The Commission [SEC] finds that it is appropriate to designate a longer period within which to take action on the proposed rule change so that it has sufficient time to consider the proposed rule change and the issues raised therein.”
    -SEC Spokesperson, in a letter to VanEck (August 2022)
    Tweet

    The verbiage in this quote seems to be hinting that the SEC is actually considering accepting VanEck’s argument. However, the SEC issuing a delay on a ruling isn’t exactly breaking news. They’ve shot down over a dozen attempts at a Bitcoin spot ETF in the last 12-month calendar year alone. There is no new information to indicate Bitcoin is any less susceptible to fraud – thereby posting inherent investor risk – than two months ago. The SEC is buying time in hopes of making a more compelling case regarding Bitcoin spot ETF’s in Canadian markets. What’s going to make more headlines in 45 days, the macroeconomic conditions from rising rates, inflation, and other recessionary indicators, or the SEC rejected the 15th (or so) Bitcoin spot ETF in the last year? After all, the SEC isn’t completely unaware of the current dynamics in financial markets.

    If VanEck is Ultimately Denied, What Does that Mean for Cryptocurrency?

    The overall impact is unlikely to be large, unless the SEC gets unpredictable here. Assuming they stay consistent with their rationale, this matter will go back to the DC Appellate Courts. But if you’re an institutional investor of SEC-approved Bitcoin assets, you’re not going to be majorly impacted by this. Inflation and rising interest rates? That will likely negatively impact at risk assets across the board and digital assets are certainly in that category. But the long-term ramifications for Bitcoin from this latest SEC ruling are likely to be very minimal.

    Just to end with a key point we just touched on, watch out for at risk assets considering this is very likely going to be the realest felt recession since 2008. There won’t be a major economic downturn because we’ve learned our lessons from 2008, but investors will sell off at-risk assets as soon as financial markets show signs of destabilization. Digital assets in an investor’s portfolio will be one of the first to go. Combined with the seasonality of Bitcoin slumps, expect the price to drop below 15,000 and who knows how much lower. How much lower would it take for the strongest crypto asset enthusiasts to wave the red flag? Would that ever happen? Only time will tell, but again, considering we have a lot of indications a recession is coming, taking a bullish position on Bitcoin in the short-term is unwise at best.
  • How CRE Investors Can Still Create Value Amidst Rising Rates

    As we’ve covered in the last couple weeks, the current trend seems to be moving towards the buyer’s direction. Rising rates and other consequences from inflation are certainly a motivating factor. However, that does not mean there is no room for the average investor to make money. This is particularly true for CRE (Commercial Real Estate) investors. There’s always money to be made in the real estate market, that is, if you’re a seasoned and skilled buyer.

    “You can’t add value to bonds — and unless you own a VC firm or you’re Warren Buffett or Elon Musk, you really can’t create value by owning stocks. Other than owning a company or a franchise, only real estate allows investors to roll up their sleeves, either physically or metaphorically, and create value in an investment.”
    -John Chang, Marcus & Millichap
    Tweet

    Not only that, but in the CRE marketplace specifically, investors have so many options. From REITs, REIGs, non-traded REIT sponsors, mini-tender offers, all the way to even direct CRE property management. The latter is what Chang illuded to in his quote above. Having a “do it yourself” attitude in real estate can allow to you avoid hiring FTE’s. Thus, you’re much more likely to have room for a positive return. What will every intelligent macroeconomist suggest to businesses when monetary policy is geared towards inflationary times, or a potential recession? Minimize business costs (Wan, CloserIQ). That applies directly to CRE investors too. If you can minimize your business cost, by acting as your own property manager for example, you are undoubtably more likely to succeed irrespective of turbulent financial times.

    With an official from the Fed quoted as saying he sees the Fed raising rates through the end of 2023, investors should prepare for a tightening economy (Saphir & Dunsmuir, Reuters). Rising prices with relatively unchanged labor market conditions. If you invest in FX, that likely means the dollar will be disadvantaged. But in CRE, as in the whole real estate asset class, positive returns are always on the table. To reiterate, investors who are willing to cut costs will make out well in a recessionary economic period.

  • Is India’s UPI (Unified Payments Interface) Technology Worth Selling Overseas and to Western Countries?

    The Unified Payments Interface (UPI) was created by the National Payments Corporation of India (NPCI) for purposes of “enabling digital payments and settlement systems in India, is an initiative of RBI and IBA”. As announced in Bloomberg in June 2022, the NPCI is looking to take UPI to overseas markets. This implies that a) the technology has been tested thoroughly and successfully in Indian markets and b) there is currently no real competitor to UPI in overseas markets. At one point, NPCI CEO Ritesh Shukla compared it to a “home-grown alternative to SWIFT”. For those who aren’t familiar, SWIFT is a Belgium-based cross-border payments system operator.

    Has the Product [UPI] been Thoroughly Tested in Indian Markets?

    Based on our research, yes UPI has been tested both rigorously and successfully in Indian markets.

    “We have displaced cash in India to a large extent and are now looking to repeat the success in cross-border corridors. Overseas Indians can use our rails to remit money inwards straightway into their bank accounts, and for the markets where Indians travel frequently, we will build acceptance for our instruments.”
    – NPCI CEO, Ritesh Shukla
    Tweet

    Not only has the technology behind UPI been proven and tested, but the methodology has also succeeded. At least that’s the quantitative claim Shukla’s making. The World Bank data seems to support the analysis too. Indians overseas remitted $87 billion in 2021; the biggest inflow for any country that was tracked by the World Bank.

    Under the RBI’s “Liberalized Remittance Scheme”, all resident individuals (including minors) are allowed to freely remit up to USD $250,000 per year. This is from April-March, for any permissible current or capital account transaction, or a combination of both. Further, resident individuals can avail of the foreign exchange facility, for specific purposes within the limit of USD $250,000 only. The RBI’s “Scheme” was introduced on February 4, 2004, with a limit of USD $25,000 (BusinessDesk, Bloomberg). Since then, the LRS limit has been revised in stages consistent with prevailing macro and micro economic conditions. Notably, the “Scheme” is not available to corporates, partnership firms, HUF, Trusts etc.

    Are there Any Notable Comparisons to India’s UPI Abroad (not factoring in SWIFT)?

    Of the $87 million in remittances India received in 2021, the US was the biggest source (World Bank). According to the World Bank, US remittances to India accounted for over 20% of the $87 million in 2021.

    “Flows to India (the world’s largest recipient of remittances) are expected to reach $87 billion, a gain of 4.6 per cent with the severity of COVID-19 caseloads and deaths during the second quarter (well above the global average) playing a prominent role in drawing altruistic flows (including for the purchase of oxygen tanks) to the country”.
    – World Bank Spokesperson, World Bank Migration and Development Brief, 2022
    Tweet

    In terms of total global remittances, India is followed by China, Mexico, the Philippines, and Egypt (World Bank). In India, remittances are projected to grow 3% in 2022 to $89.6 billion. This is reflective of a drop in overall migrant stock, as a large proportion of returnees from Middle Eastern countries are still awaiting return (World Bank).

    Remittances in low-and-middle-income countries are projected to have grown a strong 7.3% to reach $589 billion in 2021 (World Bank). This “return to growth” is far more robust than earlier estimates. Following the same resilience of flows in 2020, when remittances declined by only 1.7% despite a severe global recession due to COVID-19, according to estimates from the World Bank’s Migration and Development Brief. Lastly, the brief in its entirety can be found here, from the World Bank’s website.

    Outside of evaluating the micro-differences to SWIFT, there are no current notable competitors to India’s UPI we could find. Without any doubt, no possible comparisons would come close in terms of size or scale.

  • Is there a Difference Between a ‘Buyer’s Market’ and a ‘Market that’s Rapidly Getting Less Advantageous Towards Seller’s’?

    The vast majority of latest prognostications point to a shift in the housing market, in favor of buyers over sellers. It’s about time. America’s housing market has been brutal on homebuyer’s, renters, and those looking to lease in prime locations for years now. There is a lot of qualitative and quantitative analysis to suggest that despite rising rates, buyers currently have the advantage.

    Realtor’s Weekly Housing Market: “The Four Big Bellwethers”

    Realtor has a weekly column called “How’s the Housing Market This Week?”. Realtor’s real estate economists are some of the most trusted in the industry. Weekly, Realtor delivers the most up-to-date statistics on what they coined “the four big bellwethers of the housing market”. These include home prices, # of new listings, total days on market, and of course, mortgage rates (Dutton, Realtor).

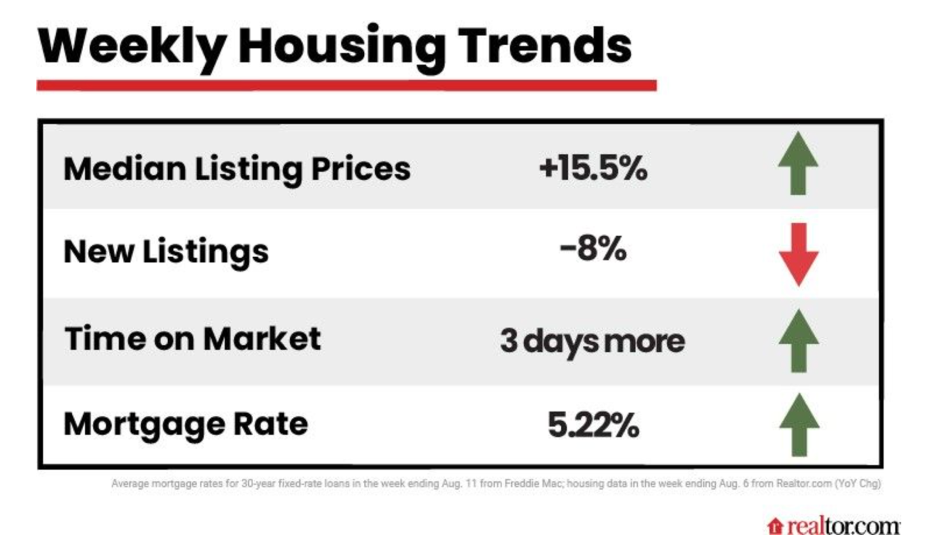
    “The housing market is resetting in a buyer-friendly direction,” notes Realtor Chief Economist Danielle Hale in her evaluation. We’d be remised if we didn’t note a “buyer-friendly direction” is certainly not the same as a true buyer’s market. While the same analysis notes the obvious, historic seller’s market that’s raged since COVID-19 began, it points out that the window for sellers is closing, rapidly. Below are the previously mentioned Realtor weekly housing trends, for week-end August 6th, 2022.

    -Realtor.com – Weekly Housing Trends, August 6th, 2022

    What jumps out to me are the top two statistics. A 15.5% median listing price increase, coupled with 8% fewer listing than the week before (Realtor.com). Hale has a unique and thought-provoking perspective on this phenomenon.

    Is There Surprisingly Good News in a 15.5% Increase in Median Listing Price?

    According to Hale, yes, this number is good news for prospective buyers. The last data from July 2022 shows a median nationwide listing price of $449,000. For the week ending August 6th, a 15.5% listing price increase means the new median was $518.595. While this marks the 34th straight week of double-digit price growth, Hale points out it’s also the “second consecutive week of deceleration” (Dutton, Realtor). The previous two weeks – at the end of July 2022 – median listing prices rose by 16.6% and 15.6%, respectively. This third ‘relatively temperate’ hike offers buyers hope home price growth will finally continue steadily dwindling.

    “The improvement has been substantial”, confirms Hale. She’s just as quick to add, “buyers in today’s market may still face meaningful affordability challenges as the typical home listing price remains near a record high”. But there’s little long-term evidence to suggest sticker price is a major deterrent for buyers (Dutton, Realtor). Hale reaffirms, “Persistent [homebuyers] may still continue to find success”. She goes on to add, “Second quarter data showed that homeownership rates increased from a year ago, both overall and for nearly every age and racial and ethnic group”.

    Given that homeownership rates have surged — amid rampant inflation, rising mortgage rates, and other deterrents — strongly signals that buyers who are willing to have some flexibility will ultimately win. Participants who are been willing to purchase somewhere they may not have considered pre-pandemic have largely become homebuyers. It’s a true testament to the lengths that homebuyers are willing to go today, provided sellers meet them halfway.

    Are Sellers Undermining the ‘Buyer Friendly’ Market?

    Anything positive for homebuyers is a negative for home sellers and of course, vice versa. Many sellers with properties on the market are panicking they ‘missed the mark’ by not closing a sale on their property during the COVID-19 real estate boom. For week-end July 30th, 2022, the number of new listings dropped by 8%, year-over-year (Dutton, Realtor).

    “New listings fell from a year ago for a fourth week. This is looking more and more like sellers may be wary of current market conditions, which have shifted substantially, even though they remain quite favorable to sellers who have owned for just about any length of time.”

    – Danielle Hale, Chief Economist, Realtor

    Hale appears to be hesitant to commit to buyer-friendly market conditions. However, she does definitively comment that conditions are becoming less and less favorable for sellers. The same message seems to be resonating across the board: if you’re a seller, the longer your property stays on the market, the worse-off your position will be.

    “While overall inventory [of new and old listings] grew by 28% over this same week last year, the active listings count still trails its 2020 and 2019 levels by more than 15% and 45%, respectively. More improvement in active inventory is likely needed to bring balance, but the recent trend may be at risk if homeowner attitudes toward selling now continue to deteriorate.”

    – Danielle Hale, Chief Economist, Realtor

    Once again, Hale seems to reemphasize the same underlying position. ‘We’re not in a pro-buyer’s market, we’re in a market that’s rapidly growing less favorable to sellers.’

    Are Rising Mortgage Rates to Blame for Homebuyers not Rushing to Close a Deal?

    The last question Realtor’s frequented market assessment addresses is why buyer’s aren’t rushing to close the deal. We are in a market that’s getting less and less favorable towards sellers, after all. What happens when we hit that market floor and conditions start to change against homebuyers. That has been the case – at a staggering rate – for well over two years now (Dutton, Realtor).

    In July 2022, listings lingered on the market a mere 34 days before getting snapped up. That’s nearly half the time it took two years earlier (Dutton, Realtor). Conversely, after having entered August 2022, it seems homebuyers are pumping the breaks and not feeling in such a rush. Hale’s prediction? Expect more of the same. She stated, “We expect more slowing ahead as the housing market reset”. The question remains, why?

    According to data provided by Freddie Mac, rising mortgage rates are a good place to start. For week-end August 11th, 2022, the average 30-year fixed mortgage rate increased to 5.22%. That’s considered a significantly steep spike from the previous week’s 4.99% (Mortgage Rates, Freddie Mac). Realtor predicts the future will hinge on how large corporations will view the potentially looming recession.

    “The big question for consumers is whether companies will over-react to the recession concerns and start trimming payrolls. A sharp pullback in hiring could have a direct impact on people’s ability to keep spending, especially with today’s high inflation.”

    – George Ratiu, Senior Economist, Realtor

    Realtor ultimately winds up agreeing. Prospective homebuyers should take full advantage of this buyer-friendly market while it lasts (Dutton, Realtor).

  • Is the US Real Estate Market Finally Starting to Cool Off?

    According to recent trends witnessed primarily in California, but largely nationwide, the supply in the housing market appears to be growing, while the demand is shrinking. This is what experts are counting on leading to a “cool off” period in real estate prices. “Today, week after week, we see more and more inventory come on the market and demand is down,” said broker Justin Itzen. He added, “Buyers have more to choose from, they can be more selective” (Moscufo, ABC News). Taylor Marr, chief economist of Redfin, echoed a very similar narrative. Marr made a distinguishment between expensive coastal markets and cheaper, rural housing markets. As Itzen’s remarks indicated, Marr concurs coastal cities located in California, New York, etc. will witness most of the impact.

    But that still leaves the larger question unanswered; are we looking at a nationwide real estate cooling period? According to an investors report Redfin released at the very start of August 2022, the share of home listings that have been on the market for more than 30 days has increased more than 12% from 2021. Due to inflationary effects, interest rates for average mortgages were between 5-6% in July 2022, compared to 2-3% July 2021. Inflation and rising prices (or rates) go hand-in-hand, but this increase is steep enough to leave tangible impressions. With more listings, dropping prices, and definite near future housing market uncertainty, we’re hopefully finally entering a buyer’s market.

    Importantly, Iesha McTier-Whyte, a broker selling middle to high-end homes in Newark, NJ advised she’s seen the same pattern. However, she doesn’t view it as a bad thing. “It’s nice to see [the market] cool down and kind of go back to the basics,” McTier-Whyte said. “What we experienced last year was like no other”. Itzen’s partner, Gio Helou, remarked “buyers are [now] able to actually go through the natural home buying process”. Assumingely, Helou meant that buyer’s now have the luxury of options. They no longer have to make the same kind of extraordinary sacrifices to simply purchase a family home.

    At one point, “homes were going within days for way over the asking price,” said Tim Sherman, a prospective homebuyer. When he and his wife found a home in Huntington Beach, CA, they began considering liquidating investments to purchase it. Not only “15% over the asking price,” commented Sherman, “but it was now over the market estimates of what the property was worth” (Moscufo, ABC News).

    The end to Sherman’s story really ties into the underlying assertion of this article. That first house fell through, but he and his wife did wind up purchasing a home. As soon as they saw the photos their broker sent them, they put in an immediate offer. Their former home in Dallas then sold in just one day (Moscufo, ABC News). If that’s any indication of the market dynamics moving forward, expect lower prices, more supply, and increased quality listings. A true win-win, both for individual homeowners and for real estate investors. As for the critics who continue to say there’s somewhat of a 2008-like “housing bubble” getting ready to pop, there’s little quantitative evidence to support the theory. Yet even the critics concede:

    “There is now a huge supply of new houses for sale, in all stages of construction, over 9 months’ supply in total, according to the Census Bureau. In terms of the number of houses, by June [2022], there were 463,000 new single-family houses at all stages of construction for sale, the highest since May 2008, and up by over 30%, from a year ago.”

    -Wolf Richter, The Wolf Street Report

    Their perspective is investors need to remain patient, as market conditions are continuing to return to their equilibrium. After what we’ve witnessed with the COVID-19 global pandemic, anything is possible, but conceptually, our economy isn’t close to the same state it was in heading into the 2008 financial collapse. We have far more restrictions on speculative investments, strict leverage ratios, mandatory reporting requirements, etc. The lessons of 2008 essentially taught us how to avoid widespread economic fragility when a significant market starts looking vulnerable. Additionally, the credit worthiness, financial disclosures, and ability to repay have all tightened considerably for buyers. Time will only tell whether we are in the midst of a “cooling off” period, or if we’re about to witness about bubble bursting. From our research and observations, we see it as more of a buyer’s market than a ‘fragile’ housing market.  

  • Are CRE Investors Impacting Environmental Social Governance (ESG)?

    Many experts are confirming the number of commercial real estate (CRE) investors who are considering environmental, social, and governance (ESG) standards when looking at potential investment opportunities is significantly increasing. A staggering 60 percent of respondents to brokerage CBRE’s 2021 Global Investor Intentions Survey stated that they had already adopted ESG criteria as part of their investment strategies. In other words, 3 out of every 5 CRE investors have factored ESG into their investment portfolio’s strategy. That’s an extremely significant number.

    What’s The Impact?

    This will force real estate investment firms to start catering to ESG conscious investors if they want to remain competitive. According to the same 2021 CBRE report, some CRE firms have committed to net-zero carbon emissions: Heitman by 2030, Nuveen by 2040, and Brookfield Properties by 2050. Overall, that seems like a win-win in the end. Commercial real estate properties will be built to be more eco-friendly and investors will continue to profit. What’s not to like?

    Industry executives, primarily, in the CRE property construction industry have been frustrated by increased scrutiny. This seems to be common in amongst senior executives, for the most part, and especially in an industry like construction. Anytime there’s increased regulation, that always leads to greater frustration. More tensions regarding profit margins, income statements, investor reports. Increased regulation almost always results in greater costs for corporations. What does that result in, in turn? Layoffs, a decrease in quality, a decrease in work/life balance, etc. Another way to look at it is when executives become worse off, employees under them are sure to suffer too. The same is true in the CRE market, both for companies on the demand and supply side.

    What Will Happen to the “Other” 40%?

    What about the other 40%; the investors who haven’t considered ESG as part of their investment strategy. Perhaps they don’t care about climate change, or they don’t believe factoring in ESG is a winning investment position. Either way, 40% of a group is still an extremely significant number. It’s not like those 40% can be forgotten or neglected. It’s basically the same situation as the other side of the coin: real estate investment firms will have to carry products that cater to ESG negligent investors too. This could include (amongst other things) REITs that hedge against heavily ESG driven CRE investment properties.

    What’s The Ultimate Outcome?

    Investors and investment firms that nail down the perfect balance of ESG conscious investments will prosper. Ultimately, with names in the CRE space like Heitman, Nuveen, and Brookfield Properties all committing to net-zero carbon emissions, you can expect “greener” CRE properties to be built in the future. That’s surely a win-win for everyone, political agenda, or affiliation notwithstanding. For investors, it means being more mindful of the ESG impact of a given CRE construction project. For example, if you’re in a REIG, or even more importantly as an individual investor, much like the 60% of current CRE investors who factored ESG into their CRE investment portfolio, you must do the same. With a REIG, you benefit from economies of scale where investors can collaboratively think of the best long-term approach. When you’re on your own, you must be certain you’re cognizant of all variables that may cause you to potentially get into the red on an investment. The research from this article shows that for CRE specifically, ESG will be included in prospective long-term plans.

    Be sure to take note!

  • Grayscale Investments, LLC Presents: Grayscale Bitcoin Trust (GBTC), Bitcoin’s First Spot ETF?

    Amongst the latest “hot topics” in the Financial Technology (FinTech) space is a cryptocurrency product aimed at changing the receptiveness of the international investment community to cryptocurrencies. Grayscale Investments, LLC has created the GBTC (Grayscale Bitcoin Trust), in an attempt to make a cryptocurrency product more marketable to institutional investors, pension funds, and other more traditional investment vehicles. Whether this approach will work in the long-term seems to be very hotly contested at the moment, for a number of reasons.

    The Grayscale Bitcoin Trust (GBTC)

    Surprisingly – though maybe not to many in the crypto community – Grayscale largely markets the GBTC for its “robust security and storage”. You would think that as an asset manager, even a crypto asset manager, Grayscale would be more excited about presenting numbers that investors are typically hungry for. However, they lead by offering the following:

    “Grayscale Bitcoin Trust’s assets are stored in offline or “cold” storage with Coinbase Custody Trust Company, LLC, as Custodian. The Custodian is a fiduciary under § 100 of the New York Banking Law and a qualified custodian for purposes of Rule 206(4)-2(d)(6) under the Investment Advisers Act of 1940, as amended.”

    Grayscale Investments, LLC (2022)

    Additional benefits, advertised by Grayscale, to purchase the GBTC include tax-advantaged account eligibility, “titled, auditable ownership [of a crypto asset] through a traditional investment vehicle”, publicly quoted price (OTCQX®: GBTC), and support from a network of trusted providers (this is where they let you know they have hired global financial services legal tycoon Davis Polk & Wardwell LLP). Why is that relevant?

    The SEC’s Ruling on Grayscale’s Bitcoin Spot ETF

    At the top of Grayscale’s website, you’ll see a banner with a hyperlink stating, “We’ve received a decision in our application to convert GBTC to an ETF”. That’s the real storyline here. It’s not the GBTC, it’s the fact that the SEC has disallowed Grayscale to convert the GBTC into a Bitcoin spot ETF. The concise version of the SEC’s 86-page decision can be captured in the following paragraph:

    “This order disapproves the proposed rule change, as modified by Amendment No. 1. The Commission concludes that NYSE Arca has not met its burden under the Exchange Act and the Commission’s Rules of Practice to demonstrate that its proposal is consistent with the requirements of Exchange Act Section 6(b)(5), which requires, in relevant part, that the rules of a national securities exchange be ‘designed to prevent fraudulent and manipulative acts and practices’ and ‘to protect investors and the public interest.’’’

    SEC, Release No. 34-95180; File No. SR-NYSEArca-2021-90 (July 22, 2022)

    Grayscale immediately responded by hiring former U.S. Solicitor General, Donald B. Verrilli, Jr. – best known for arguing President Obama’s ACA (Affordable Care Act) successfully before the US Supreme Court – who filed an appeal of the SEC’s ruling. Grayscale says they had no choice but to escalate the matter, given the “SEC’s arbitrary and capricious actions and discriminatory treatment of issuers”. The appeal seems to be almost exclusively relying on the argument that the SEC has allowed multiple Bitcoin futures ETFs into the marketplace. Furthermore, since their treatment of futures and spots of derivatives is generally similar, they are unjustly denying investors access to a new marketplace: Bitcoin spot ETFs. GBTC has the potential to become the first Bitcoin spot ETF to be approved by the SEC.

    A High-Level Look at GBTC’s Financials

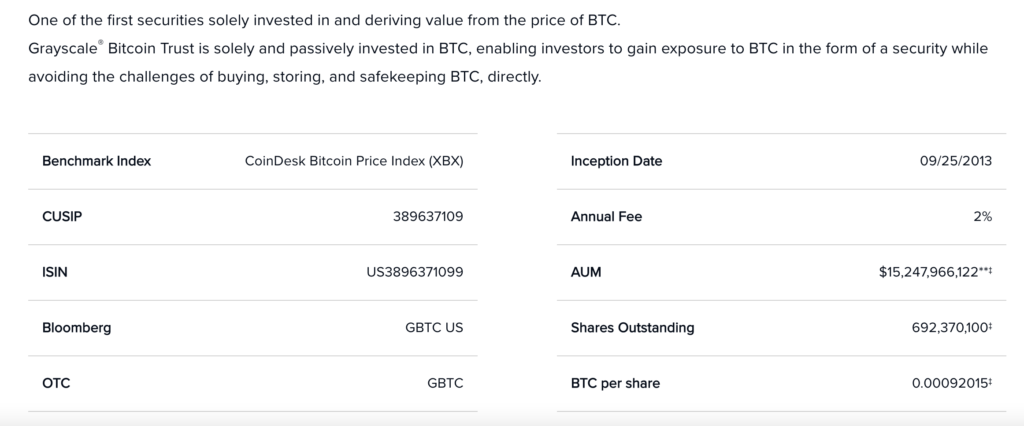
    Below you can see some basic financials on GBTC from Grayscale’s website. They include the CUSIP (389637109), where we’ll use Bloomberg to investigate GBTC’s high-level financials.

    Source: Grayscale Investments, LLC (August 2022)

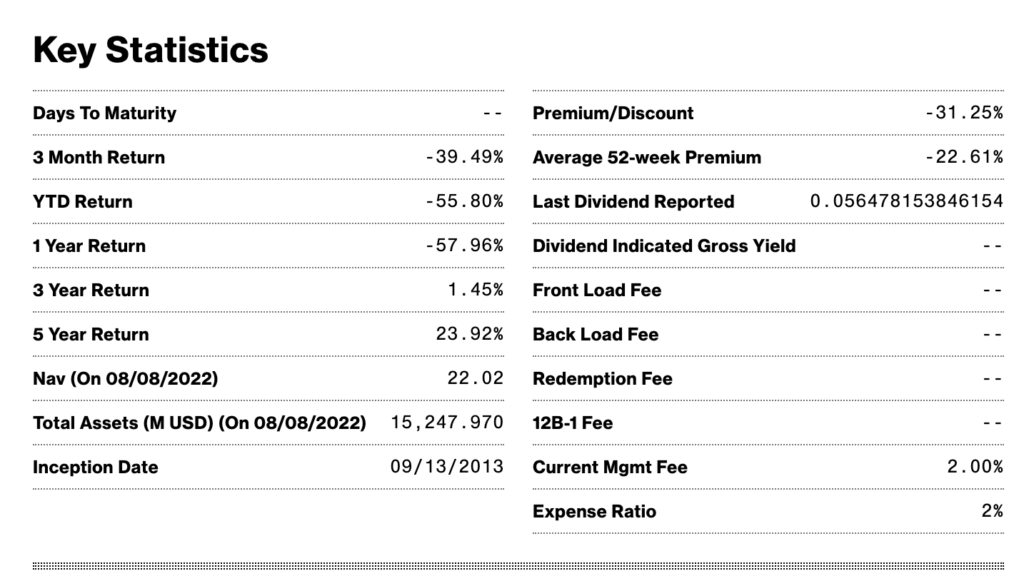
    The “Key Statistics” from Bloomberg for CUSIP 389637109 as of Tuesday August 9th, 2022 (GBTC US) are below.

    Source: Bloomberg L.P. (August 2022)

    Looking at the YTD, 1-year, 3-year, and 5-year average returns, in the context of converting this Bitcoin asset to a spot ETF, is the SEC wrong when they say Grayscale is breaking an SEC rule that “requires, in relevant part, that the rules of a national securities exchange be ‘designed to prevent fraudulent and manipulative acts and practices’ and ‘to protect investors and the public interest’”? In other words, is introducing a Bitcoin spot ETF into the marketplace more dangerous than a Bitcoin futures ETF?

    Bitcoin Futures ETFs vs. Bitcoin Spot ETFs

    While we’re not opining on a question that’s currently an open legal issue, perhaps understanding the difference would help. A spot Bitcoin ETF brings many (almost all) of the benefits of a futures ETF. Some include investing in Bitcoin without using an exchange, paying less in fees than on a crypto exchange, and streamlining the overall process (Moeller, Cointelegraph). However, a spot ETF invests in Bitcoin on the spot.

    With a Bitcoin spot ETF, you invest in Bitcoin at its spot price, meaning buyers will be holding Bitcoin within their portfolio. In practice, it’d be very much like buying a stock. Crypto enthusiasts view a spot ETF as a more legitimate method of investment, therefore Bitcoin would become more legitimized with a SEC-approved Bitcoin spot ETF product.

    Futures are defined as “derivative financial contracts that obligate parties to buy or sell an asset at a predetermined future date and price” (Investopedia, 2022). So, what’s the key difference? With a Bitcoin spot ETF, you have immediate ownership of Bitcoin. When you purchase a Bitcoin futures ETF, you’re effectively just betting on the market, depending on if you choose to take a long or short position. But purchasing a Bitcoin futures ETF by no means entails immediate ownership of Bitcoin as an asset. If you’re going to purchase a SEC-approved Bitcoin spot ETF in the future, as one does not exist today, it’s critical to understand you’ll immediately add Bitcoin to your asset portfolio.

    GBTC’s Primary Differentiator: Security

    That seems to circle back to Grayscale’s initial pitch of the GBTC having “robust security and storage”. The SEC appears to be making less of a comment on the GBTC than they are about Bitcoin in general. A Bitcoin spot ETF can only be rejected for the reasons given by the SEC if they felt that Bitcoin was too susceptible to “fraudulent and manipulative acts”. Through strategic marketing, Grayscale is looking to differentiate their potential Bitcoin spot ETF product as completely secure. Furthermore, they’ve had the longest and most hopeful petition to the SEC for a Bitcoin spot ETF, with initial efforts dating back to 2016 (Moeller, Cointelegraph). Over six years later, Grayscale remains just as committed to convert the GBTC to Bitcoin’s first SEC-approved spot ETF. Whether or not they’ll be successful is still very much an open question. It’s worth noting that Grayscale’s Bitcoin Trust (GBTC) is the world’s only SEC-approved, publicly traded “Bitcoin Trust”. A “Bitcoin Trust” can be very closely compared to a private-placement trust. It trades just like a stock over the counter. That existing confidence, along with potential first-mover market advantage, would certainly give Grayscale a huge reason to seek to overturn the SEC’s latest official ruling.

    For reference, if you want to investigate a few of the best-known Bitcoin futures ETFs, they include ProShares BITO Bitcoin futures ETF, Valkyrie Bitcoin Strategy ETF, and VanEck Bitcoin Strategy ETF. The ProShares BITO Bitcoin futures ETF currently holds around $1B in investments (Moeller, Cointelegraph). For a look closer at information and BITO’s financials, they’re listed on the New York Stock Exchange (NYSE: Arca). For additional information on Grayscale Investments or the GBTC, their website can be found here.