Tag: Real Estate Investor Tips

  • PropTech: What is it and Who Are the Primary Investors?

    Property Technology, commonly known as PropTech, refers to the use of Information Technology (IT) to assist both individuals and companies buy, sell, research, and manage real estate. While still a relatively new field, the convergence of technologies, cloud, and digital transformation are key forces driving PropTech forward. The goals of PropTech include: minimizing the cost and resources associated with real estate transactions, maximizing efficiency, saving time, and personalizing property management. This concept is similar to FinTech, where the focus is on the use of technology in finance. PropTech utilizes digital innovation and other technologies to address real estate market participants’ needs in the property industry.

    Efficient PropTech is specifically devised to streamline processes and connect market participants in all aspects of real estate. Therefore, PropTech directly impacts buyers, sellers, brokers, lenders, landlords, as well as others. One of the most popular current PropTech technology is virtual reality software, which allows prospective buyers to virtually walk through properties, construction sites, and more. Additional well-known PropTech technologies include software for reporting repairs, splitting rent payments, and crowdfunding new real estate projects.

    At this time, PropTech consists of three major market segments: (1) smart home, (2) sharing real estate, and (3) real estate FinTech.

    Smart Home

    A smart home is equipped with digital platforms that monitor, manage, or operate specific property assets. Amazon Echo’s Alexa is an example of something in a smart home. Generally, they are comprised of digital platforms that monitor, manage or operate specific property assets. Other examples could be something a security surveillance system that warns property owners of a threat, a smart thermostat that regulates the temperature of uninhabited units, or smart light bulbs that can be turned on by a smartphone app or digital assistant.

    Sharing Real Estate

    This refers to technology that facilitates the processes involved with sharing or renting real estate assets, such as land, offices, storage, apartments, parking lots, and more. For example, there could be a software that facilitates automatic online payments for retail spaces occupied in a building owned by a property management company.

    Real Estate FinTech

    This segment of PropTech includes applications that involve buying and selling real estate assets. A platform that reduces the amount of physical paperwork and documentation involved in a home purchase can be thought of as an example. Stay tuned for a deeper conversation regarding the relationship between PropTech and FinTech.

    With PropTech still being a relatively new field, the investors are largely comprised of wealthy, seasoned real estate investing experts (or at least those with a real estate investing background). In addition to being backed by some of the world’s largest real estate giants, it would be fair to say most of the individuals behind the world’s biggest tech companies, agree that future technology is pushing towards digital transformation (Donati, Forbes). Therefore, you’ll find investors that are interested in a sort of ‘futuristic’ technology category when it comes to financial investments. For example, PropTech investors would be very likely to also be interested in FinTech and Cryptocurrency. While the latter two seem to be more popular at the moment, PropTech is definitely something well worth looking into, especially if you have a specific interest in real estate investing.
  • Homebuyers: Five Tips for Financing and Budgeting

    When it comes to home buying, there’s a well-known critical rule: Avoid purchasing more house than you can afford. However, what represents “affordable” will differ between homebuyers. Therefore, one of the most important things for a first-time home buyer to do is plan and budget in advance. Diving into a potential multi-decade financial commitment is one of the most daunting experiences for an individual (or a couple, for that matter) in their lives. It is also highly probable that it will be your most expensive purchase. Before doing so, strategically allocating your money is essential. Otherwise the costs are steep. Before you know it, you may quickly find yourself getting buried in financial hardship, or the ultimate worst nightmare: foreclosure. To avoid this, we recommend the following five tips for first-time homebuyers.

    1. Strongly consider getting started with the “28 Percent Rule”

    The “28 Percent Rule” dictates that your mortgage shouldn’t be more than 28% of your gross income each month. While the Federal Housing Administration (FHA) recommends a slightly more generous allowance of 31%, first-time homebuyers in particular ought to air on the side of caution, considering they are likely repaying some other forms of debt. Additionally, there are the normal monthly expenses (food, transportation, healthcare, etc.) that any working-class individuals would have to account for.

    2. Your down payment should dictate your home’s budget

    Generally, lenders will look for homebuyers to put at least 20% of the property’s purchase price in cash. Though you can utilize other resources to obtain an approval, such as private mortgage insurance (PMI), this will inflate your monthly mortgage payment by roughly 1% (Fuscaldo, Investopedia). It’s important to note that the PMI depends significantly on the size of the property, your credit score, and the potential for the value of the home to increase over time. It’s equally important to note that it is in your long-term best interest to avoid these kinds of instruments, as they’ll tie up more and more of your monthly disposable income in interest repayment. On top of everything else, it’s critical to remember closing costs, as they’ll cost you anywhere from 2-5% of the home’s purchasing price, depending on what state you live in (Fuscaldo, Investopedia). Avoid over-leveraging yourself. Put as much money down as you can afford to, but certainly aim for higher than the bare minimum 10%.

    3. Precisely track your debt-to-income ratio

    It’s a very well-known fact that mortgage lenders will look at a prospective homeowner’s debt-to-income ratio when determining if they will extend a loan to the borrower. Therefore, keeping track of this ratio on a monthly basis is a good benchmark for prospective homeowners to calculate themselves, in order to ultimately decide if a home they’re interested in is affordable. Suppose your gross monthly income is $5,000. Then, if your mortgage payment is $1,500 and the total of your other monthly financial obligations is $1,000, this puts your debt-to-income ratio at 50%. Qualified mortgage lenders very rarely will approve a borrower with a debt-to-income ratio above 43%. Thus, in the above example the hopeful homeowner would unlikely to get approved and even if they did, it’s probable they would be setting themselves up for failure.

    4. Don’t forget all homeowner expenses, not just the monthly mortgage

    There’s no question getting approved for a home loan is an essential step in the process, yet this is only one obligation (though it’s by far the largest). The tough reality is your monthly mortgage payment will not be your only reoccurring expense as a homeowner. Consider additional monthly homeowners’ insurance, utilities, repairs, and maintenance costs. Depending on the season, the snow will need to be shoveled, or the lawn will need to be mowed, or the shrubs will need to be trimmed. Many find that over time, the list just keeps growing. When you calculate the affordability of a home, you may find that an affordable $1,500 monthly mortgage payment is no longer palatable when you factor in an additional $1,000 in monthly expenses. This is a large reason behind the idea of putting a considerable downpayment on the home; it frees up money for those other monthly costs, rather than irresponsibly squandering it on interest.

    5. Settle on a property you can handle managing

    Not only are the additional monthly homeowner expenses important to factor in, but you also need to be mindful of the condition and size of the property. In a situation when you’re concerned about a large utility bill from heating or cooling, less is more. A 4,000-square-foot property that needs serious repair may be a tempting proposition, until it breaks the budget. You may find you’re better off financially with more of a picturesque small home on a quaint hill, in a quiet neighborhood instead. For your own benefit, have a construction or homeowner expert look into the homes specifications to ensure you haven’t missed anything vitally wrong.

    The bottom line is that to many, home ownership is still considered to be the American Dream. In reality, it can quickly turn into a financial nightmare when you miscalculate your monthly expenditures. First-time buyers in particular often want more than they can take on at that moment. Without taking the time to properly prepare for the single biggest purchase of one’s life, they can find themselves house-rich and cash-poor, leading to ultimate financial misery. We urge any future homebuyers to take the necessary preparation steps. Do not sign up for a dream you are not exceptionally confident you can afford.

  • NYC Real Estate Market Mid-2021: Are You Better Off Buying or Renting?

    Since New York City’s (NYC) real estate market is still experiencing a fresh post-COVID effect, you are better off buying if you have the money (and credit score). However, as is often the case, it greatly depends on your financial situation. Living in arguably the most desirable and expensive part of the world presents a financial burden to many younger adults, who are still working lower paying, entry level jobs.

    The majority of real estate property owners in New York City are of older age and in the highest income brackets (NYU Furman Center). Additionally, they are more likely to have permanent ownership of property in other locations (Goldstein, Property Nest).

    Many people view renting as ‘wasteful’ because you don’t have the benefit of acquiring equity in your property. However, the reality is for most young or middle-aged professionals, the economic opportunities – combined with the cost of living in New York City – don’t allow them to acquire enough requisite disposable income to put a down payment on a desirable apartment unit. This brings up a primary obstacle many residents of New York City see with buying a permanent unit: most people don’t view New York City as their ‘final destination’, long-term residence. In other words, when most people think about taking out a mortgage and buying a home, they’re thinking about a serious long-term commitment (emphasis on long-term). Raising kids, settling down in a permanent work situation, and finally retiring. The suburbs or a quiet town; not the most densely populated, most popular tourist destination in the world.

    While there are plenty of mechanisms available to individuals looking to get out of a 20 or 30-year mortgage after only a few years, logically, it would make sense for most to still prefer not to take on that kind of serious financial responsibility without the intent of staying in that location for a while.  

    With that being said, from the perspective of someone simply asking: “hey, would I be better off buying or renting in New York City?”, I would advise them to not be hesitant and buy if they have the money saved.

    The reason is two-fold. If you are going to live in the unit, at least initially, you’ll acquire equity simultaneously. If you find that NYC is not for you in a few years – as many inevitably do – current market prices and historic trends, combined with current rates and incentives, suggest one would be able to see a positive cash flow from subleasing or subletting their own property. Meaning, renters are consistently earning more monthly rent than their monthly mortgage payments. Alternatively, if you have no desire of becoming a landlord, contrary to ordinary homeowner’s beliefs, there is the ability to sell your mortgaged property and earn a profit. It’s extremely difficult to look at the recent data without considering the COVID-19 situation, but over a 10-year period prior to that, real estate prices were significantly increasing year-over-year.

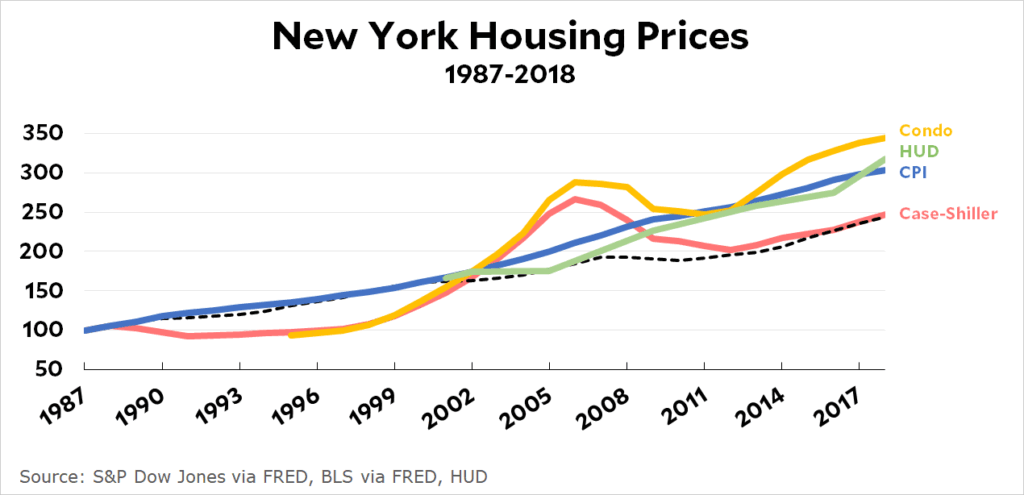
    That’s largely why real estate became viewed as a very popular investment vehicle for financial investors. The figure below illustrates an average of New York housing prices over a 30-year period, between 1987 and 2018, from different housing market segments.

    Figure 1 – New York (NYC) Housing Market Prices (1987-2018) Overview

    As one can see, prices went up across the board mostly every year, with the exception of a rocky period in the midst of the Great Recession of 2008. Therefore, having more ownership/equity in a property that’s also going to increase in value over time is a no brainer, even if you choose to move out of that property prior to paying off your mortgage.

  • CRE Investing Through CrowdStreet

    CrowdStreet™ is an up-and-coming type of crowdfunding website that’s tailored specifically to CRE (Commercial Real Estate) investors. Founded in 2013, the site pairs thousands of investors on their marketplace and pools their money to invest in different CRE properties. The benefits that CrowdStreet claims to provide are: low cost, institutional quality real estate investments that have lower fees than REITs and only include pre-vetted projects.

    As of June 19th, 2021, CrowdStreet has completed 488 deals, raised $1.9B in capital, and returned $197M of investor distributions (www.CrowdStreet.com). With new deals launching every week, the CrowdStreet marketplace is also unique because it gives prospective investors the following three (3) projections on each CRE investment: (1) Targeted Investor IRR, (2) Targeted Equity Multiple, and (3) Targeted Investment Period. Keeping in mind these are all pre-vetted projects, this allows prospective investors to pick from multiple properties based on the attributes that are geared towards their goals.

    Since there are many different types of real estate crowdfunding websites, CrowdStreet in particular distinguishes itself because they target CRE properties specifically. They then break-down individual prospective gains, equity multiples, and the period the investor will have their capital tied up. This allows investors to see a clearer overview of their investment return potential and the amount of time their capital will be utilized for the CRE investment, so they can make more informed decisions, as well as better manage the risk of their overall portfolio. But there’s a catch. While CrowdStreet is continuing to grow along with their user base, an investor account minimum must be $25,000 and the platform is only available to accredited investors. For seasoned CRE investors, that may not be as big of a problem. However, for the average qualifying CRE investor, CrowdStreet’s business model is viewed as highly illiquid.

    Overall, while CrowdStreet offers distinct advantages to CRE investors, its limitations prevent it from reaching a wider audience. Clearly that’s their intention, but perhaps some of the requirements limit the potential success of their offerings. For example, if a non-accredited investor has a higher risk tolerance and is willing to invest the minimum amount, the CRE project may not get financing because that investor wouldn’t be accepted on CrowdStreet. Similarly, if an accredited investor is more risk averse, or is not in a position to immediately invest $25,000 in a given project over a period of years, there is no middle-ground and again, the CRE project may not receive financing. Concisely, within the limited scope of their business model, there is more CrowdStreet can do to broaden their user base and thereby pave the way for more CRE projects to receive financing.

  • What is a REIG? The Pros and Cons

    A REIG (Real Estate Investment Group) is a group of private investors who invest almost exclusively in real estate by pooling money, knowledge, and/or time to acquire properties that generate income (Brummer, Millionacres). Investment strategies for REIGs will differ based on each group’s specific strengths. A REIG is not a real estate investment trust (REIT) or crowdfunding real estate venture, although superficially, they may appear similar. They both invest the majority of pooled funds in real estate or real estate debt, earn income primarily from real estate, and distribute most of the income back to the parties involved.

    Pros of a REIG

    A REIG is a way for you to have your investment funds backed by physical real estate while allowing you to leverage the collective buying power and experience of the group. Additionally, investing in real estate as a group can give you a less “hands on” approach to real estate investing, or more, depending on your desires and the strengths of your group. Furthermore, a REIG is a form of “diversification” in the sense that your thoughts about the financial incentives of an acquisition may be different than your partners in the group. Of course, this can be a negative if you are unable to persuade others investors in the group and the property turns out to be a successful investment. However if you surround yourself with like-minded investors, which is generally the case for most REIGs, this is unlikely to occur often. Going back to buying power, groups of investors can pool a very substantial amount of money together. This would in turn allow them to invest greater sums of cash and diversify their investments over a greater number of real estate properties. Conversely, an individual investor may only have enough capital to put into one – or a few – properties that may wind up taking an unexpected downturn. Finally, there’s a benefit to having fellow investors with the same stakes you do because you have the opportunity to learn from them. You would be able to potentially use some of those successful strategies in your own personal real estate investments.

    Cons of a REIG

    Many cons to a REIG can also be viewed as strengths, depending on the amount of weight you pull in it. For example, a more “hands-off” approach to investing through a REIG can turn detrimental if the individual(s) responsible for the “hands-on” tasks do a poor job. Additionally, since REIGs pool your investment money with others, you lose out on some profit prospective with it being shared throughout the group. To the contrast, this could be viewed as a way to mitigate your conceivable losses – as mentioned in the strengths – but skilled real estate investors rarely have a pessimistic view of investments they are willing to enter into. While some view this as insignificant, the tax structure and fees associated with REIGs similarly lower your bottom line profit. Along the same lines, due to regulations and commonplace agreements signed between the parties, pulling your money out of the REIG can be burdensome and costly. Finally, many investors are prone to different management styles, have different investment goals, and differ in many other germane ways. Conflicts arising from disagreements between members in a REIG can lead to not only unfavorable financial outcomes, but it can go as far as breaking up the REIG.

    Concisely, REIGs are a good fit for novice or expect real estate investors, as well as everything in between. From our perspective, the concept seems like it would be a better fit for those looking to enter the real estate market, rapidly expand their presence in that market, or if you have unique knowledge, but do not have the cash saved to personally invest in real estate yet. Reviewing the pros and cons alone, unfortunately, does not provide enough guidance as to whether or not this is the right investment vehicle for you. As with most financial investments, REIGs can be beneficial or detrimental for you, completely dependent on your financial situation, knowledge of the real estate market, and more. We do believe that an invaluable positive to REIGs is the knowledge potential from other investors in your group. Some of the most successful investors from different parts of the globe have said that intellectual capital can prove to be exponentially more valuable than simply having excess cash in a savings account, with no unique or constructive ideas on how to put that capital to use in order to maximize a positive return.