Tag: real estate market

  • Financial Markets Are Suffering, But What About Real Estate?

    As recent signals that the Fed’s “soft landing” recession isn’t going to come to fruition, financial markets responded accordingly. In addition to covering financial markets impact, we’re going to look into real estate. The DOW Jones and S&P 500 both dropped steadily Friday 10/7. The S&P has been on such a steady decline, the last 12 months of gains have officially completely canceled out. While some have speculated that we’re at a “bottoming out” in the equities market, which is supported by historic S&P 500 trends, market participants don’t seem to fully buy in. In fact, quantitatively the Top 5 stocks by market cap in the S&P 500 (Apple, Microsoft, Amazon, Tesla, and Alphabet Inc/Google, i.e., “Big Tech”) have been overpriced for years, compared to S&P 500 P/E [Price-to-Earnings] averages.

    Either way, turmoil is very likely to continue for capital markets and equities investors. Even if the net result is positive, there will be a lot of sleepless nights in the process. Let’s shift gears and take a look at a completely different, but critical (remember 2008) market: real estate.

    The Real Estate Market was Effectively COVID-proof; is it Recession-proof?

    This is the ultimate question for investors will look at real estate – both passive and active investments – in the longer-term. Foreign investors are already starting to see massive benefits to American real estate investments. That’s certainly one of the primary catalysts for steadily high real estate prices, while other assets are devalued. While we’re going to address the current and future state of the real estate market, the heading was rhetorical. Never forget 2008. That’s going to be a critical lesson investors takeaway from this coming recession, as well. 

    Real estate and related assets are certainly not recession, or even depression proof. It’s always good to be reminded of this fact: real estate is the world’s largest asset class. That means the most money (in all forms of currency, worldwide) is being spent in this market, as compared to any other segment in global finance. With real estate-related securities, we now know we must pay extra close attention to the value of the underlying assets. That goes back to a key differentiator when you’re discussing real estate in the context of an investment strategy. People and families will always need shelter. The landscape may have been altered due to COVID-19, but corporations still need office buildings.

    Physical Real Estate Will Always Have Some Value

    The critical point is real estate will continue to have some value, regardless of what happens in financial markets. Moving away from the combination of greed – both on the part of homeowners and lenders – that led up to the 2008 financial crisis, real estate is still something society will always need. Remember how truly heartbreaking some of the stories of families losing their homes during that 2008 recession was? When tangible assets that we get daily utility from as in the equation, it’s an entirely different scenario from an illiquid financial asset. The types of investors are different, their goals are different, their interests vary, etc. This is all to say that while there’s no doubt there’s a level of positive correlation between financial markets and real estate prices, by no means is it absolute. The dynamics are far too dissimilar.

    However, not being recession-proof is actually one of the common denominators that always holds true for the pair. 

    The Pandemic Housing Boom

    As we’ve recently shared, experts started questioning how long this “seller’s market” we’ve seen explode since COVID-19 will last. Since then, there have been major developments. First and foremost, from the Fed. In late September 2022, the Fed announced they are going to “reset” the real estate market through a ‘difficult’ correction. In June 2022, Fed Chair Jerome Powell said he sees spiking mortgages rates fizzling out the Pandemic Housing Boom as a “good thing”. During what’s referred to as the Pandemic Housing Boom, housing prices soared in growth by 42%. We’ll now certainly see some of those gains erased.

    With increased rates, we should expect to see a diminished potential buyer pool. In April 2022, prices peaked at 21% – according to Zillow’s home value index – however by this fall they fell to just 14%. According to Zillow senior economist Jeff Tucker, “it’s too soon to tell” how big of an impact the reset will have on home prices. In July 2022, the S&P Case-Shiller index, which measures house prices in 20 US cities, recorded its first monthly decline in a decade, dropping by 0.44%. Mortgage rates (30-year, fixed rate) are currently sitting at roughly 6.7%, according to guarantor Freddie Mae. Just a year ago however, the same 30-year, fixed rate mortgage was 2.99%.

    The Impact of the Current Correction in Housing Market Prices

    “The market is shifting, but a correction was needed”, said real estate agent Junior Torres. “It was not a sane market, what we were having in the pandemic”. This is causing sellers, who were driving the early 2020s pandemic market, to face a new reality. Fewer properties are receiving fewer offers. Sellers are going to continue getting more and more ‘desperate’ the longer the correction lasts. In other words, until we’ve reached a point where supply and demand is back at an equilibrium price, median selling prices will continue to decrease.

    Additionally, a correction in the housing market typically incentivizes homeowners to ‘stay put’. Investors and home flippers might feel pressure to sell quickly, however homeowners will simply keep their house. If we do reach that point sometime in 2023 – but more likely 2024 – they will then reassess their situation. However, when the Fed is verbally communicating that rates aren’t down – the opposite – homeowners have frankly no incentive to sell. According to the latest numbers from Zillow, the median stay in a US home is 12 years.

    Concisely, housing market prices are going to continue decreasing while rates remain at this level. From Fed statements, this is expected to continue through 2023. This should result in housing market prices continuing on the same trajectory. Committed sellers and investors will feel pressure to act quicker. Those not ‘forced’ to sell for unexpected reasons (new job, for example) will very likely remain in their homes. This will obviously decrease supply, but again primarily due to the current and expected mortgage rates in the short-term, we should expect to see below average demand.
  • Financial Markets Are Suffering, But What About Real Estate?

    As recent signals that the Fed’s “soft landing” recession isn’t going to come to fruition, financial markets responded accordingly. In addition to covering financial markets impact, we’re going to look into real estate. The DOW Jones and S&P 500 both dropped steadily Friday 10/7. The S&P has been on such a steady decline, the last 12 months of gains have officially completely canceled out. While some have speculated that we’re at a “bottoming out” in the equities market, which is supported by historic S&P 500 trends, market participants don’t seem to fully buy in. In fact, quantitatively the Top 5 stocks by market cap in the S&P 500 (Apple, Microsoft, Amazon, Tesla, and Alphabet Inc/Google, i.e., “Big Tech”) have been overpriced for years, compared to S&P 500 P/E [Price-to-Earnings] averages.

    Either way, turmoil is very likely to continue for capital markets and equities investors. Even if the net result is positive, there will be a lot of sleepless nights in the process. Let’s shift gears and take a look at a completely different, but critical (remember 2008) market: real estate.

    The Real Estate Market was Effectively COVID-proof; is it Recession-proof?

    This is the ultimate question for investors will look at real estate – both passive and active investments – in the longer-term. Foreign investors are already starting to see massive benefits to American real estate investments. That’s certainly one of the primary catalysts for steadily high real estate prices, while other assets are devalued. While we’re going to address the current and future state of the real estate market, the heading was rhetorical. Never forget 2008. That’s going to be a critical lesson investors takeaway from this coming recession, as well. 

    Real estate and related assets are certainly not recession, or even depression proof. It’s always good to be reminded of this fact: real estate is the world’s largest asset class. That means the most money (in all forms of currency, worldwide) is being spent in this market, as compared to any other segment in global finance. With real estate-related securities, we now know we must pay extra close attention to the value of the underlying assets. That goes back to a key differentiator when you’re discussing real estate in the context of an investment strategy. People and families will always need shelter. The landscape may have been altered due to COVID-19, but corporations still need office buildings.

    Physical Real Estate Will Always Have Some Value

    The critical point is real estate will continue to have some value, regardless of what happens in financial markets. Moving away from the combination of greed – both on the part of homeowners and lenders – that led up to the 2008 financial crisis, real estate is still something society will always need. Remember how truly heartbreaking some of the stories of families losing their homes during that 2008 recession was? When tangible assets that we get daily utility from as in the equation, it’s an entirely different scenario from an illiquid financial asset. The types of investors are different, their goals are different, their interests vary, etc. This is all to say that while there’s no doubt there’s a level of positive correlation between financial markets and real estate prices, by no means is it absolute. The dynamics are far too dissimilar.

    However, not being recession-proof is actually one of the common denominators that always holds true for the pair. 

    The Pandemic Housing Boom

    As we’ve recently shared, experts started questioning how long this “seller’s market” we’ve seen explode since COVID-19 will last. Since then, there have been major developments. First and foremost, from the Fed. In late September 2022, the Fed announced they are going to “reset” the real estate market through a ‘difficult’ correction. In June 2022, Fed Chair Jerome Powell said he sees spiking mortgages rates fizzling out the Pandemic Housing Boom as a “good thing”. During what’s referred to as the Pandemic Housing Boom, housing prices soared in growth by 42%. We’ll now certainly see some of those gains erased.

    With increased rates, we should expect to see a diminished potential buyer pool. In April 2022, prices peaked at 21% – according to Zillow’s home value index – however by this fall they fell to just 14%. According to Zillow senior economist Jeff Tucker, “it’s too soon to tell” how big of an impact the reset will have on home prices. In July 2022, the S&P Case-Shiller index, which measures house prices in 20 US cities, recorded its first monthly decline in a decade, dropping by 0.44%. Mortgage rates (30-year, fixed rate) are currently sitting at roughly 6.7%, according to guarantor Freddie Mae. Just a year ago however, the same 30-year, fixed rate mortgage was 2.99%.

    The Impact of the Current Correction in Housing Market Prices

    “The market is shifting, but a correction was needed”, said real estate agent Junior Torres. “It was not a sane market, what we were having in the pandemic”. This is causing sellers, who were driving the early 2020s pandemic market, to face a new reality. Fewer properties are receiving fewer offers. Sellers are going to continue getting more and more ‘desperate’ the longer the correction lasts. In other words, until we’ve reached a point where supply and demand is back at an equilibrium price, median selling prices will continue to decrease.

    Additionally, a correction in the housing market typically incentivizes homeowners to ‘stay put’. Investors and home flippers might feel pressure to sell quickly, however homeowners will simply keep their house. If we do reach that point sometime in 2023 – but more likely 2024 – they will then reassess their situation. However, when the Fed is verbally communicating that rates aren’t down – the opposite – homeowners have frankly no incentive to sell. According to the latest numbers from Zillow, the median stay in a US home is 12 years.

    Concisely, housing market prices are going to continue decreasing while rates remain at this level. From Fed statements, this is expected to continue through 2023. This should result in housing market prices continuing on the same trajectory. Committed sellers and investors will feel pressure to act quicker. Those not ‘forced’ to sell for unexpected reasons (new job, for example) will very likely remain in their homes. This will obviously decrease supply, but again primarily due to the current and expected mortgage rates in the short-term, we should expect to see below average demand.

  • Is there a Difference Between a ‘Buyer’s Market’ and a ‘Market that’s Rapidly Getting Less Advantageous Towards Seller’s’?

    The vast majority of latest prognostications point to a shift in the housing market, in favor of buyers over sellers. It’s about time. America’s housing market has been brutal on homebuyer’s, renters, and those looking to lease in prime locations for years now. There is a lot of qualitative and quantitative analysis to suggest that despite rising rates, buyers currently have the advantage.

    Realtor’s Weekly Housing Market: “The Four Big Bellwethers”

    Realtor has a weekly column called “How’s the Housing Market This Week?”. Realtor’s real estate economists are some of the most trusted in the industry. Weekly, Realtor delivers the most up-to-date statistics on what they coined “the four big bellwethers of the housing market”. These include home prices, # of new listings, total days on market, and of course, mortgage rates (Dutton, Realtor).

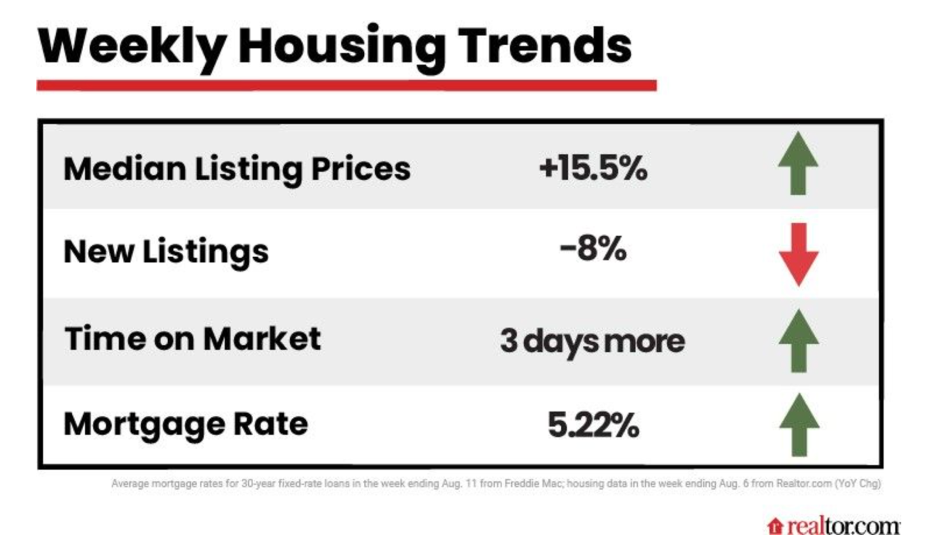
    “The housing market is resetting in a buyer-friendly direction,” notes Realtor Chief Economist Danielle Hale in her evaluation. We’d be remised if we didn’t note a “buyer-friendly direction” is certainly not the same as a true buyer’s market. While the same analysis notes the obvious, historic seller’s market that’s raged since COVID-19 began, it points out that the window for sellers is closing, rapidly. Below are the previously mentioned Realtor weekly housing trends, for week-end August 6th, 2022.

    -Realtor.com – Weekly Housing Trends, August 6th, 2022

    What jumps out to me are the top two statistics. A 15.5% median listing price increase, coupled with 8% fewer listing than the week before (Realtor.com). Hale has a unique and thought-provoking perspective on this phenomenon.

    Is There Surprisingly Good News in a 15.5% Increase in Median Listing Price?

    According to Hale, yes, this number is good news for prospective buyers. The last data from July 2022 shows a median nationwide listing price of $449,000. For the week ending August 6th, a 15.5% listing price increase means the new median was $518.595. While this marks the 34th straight week of double-digit price growth, Hale points out it’s also the “second consecutive week of deceleration” (Dutton, Realtor). The previous two weeks – at the end of July 2022 – median listing prices rose by 16.6% and 15.6%, respectively. This third ‘relatively temperate’ hike offers buyers hope home price growth will finally continue steadily dwindling.

    “The improvement has been substantial”, confirms Hale. She’s just as quick to add, “buyers in today’s market may still face meaningful affordability challenges as the typical home listing price remains near a record high”. But there’s little long-term evidence to suggest sticker price is a major deterrent for buyers (Dutton, Realtor). Hale reaffirms, “Persistent [homebuyers] may still continue to find success”. She goes on to add, “Second quarter data showed that homeownership rates increased from a year ago, both overall and for nearly every age and racial and ethnic group”.

    Given that homeownership rates have surged — amid rampant inflation, rising mortgage rates, and other deterrents — strongly signals that buyers who are willing to have some flexibility will ultimately win. Participants who are been willing to purchase somewhere they may not have considered pre-pandemic have largely become homebuyers. It’s a true testament to the lengths that homebuyers are willing to go today, provided sellers meet them halfway.

    Are Sellers Undermining the ‘Buyer Friendly’ Market?

    Anything positive for homebuyers is a negative for home sellers and of course, vice versa. Many sellers with properties on the market are panicking they ‘missed the mark’ by not closing a sale on their property during the COVID-19 real estate boom. For week-end July 30th, 2022, the number of new listings dropped by 8%, year-over-year (Dutton, Realtor).

    “New listings fell from a year ago for a fourth week. This is looking more and more like sellers may be wary of current market conditions, which have shifted substantially, even though they remain quite favorable to sellers who have owned for just about any length of time.”

    – Danielle Hale, Chief Economist, Realtor

    Hale appears to be hesitant to commit to buyer-friendly market conditions. However, she does definitively comment that conditions are becoming less and less favorable for sellers. The same message seems to be resonating across the board: if you’re a seller, the longer your property stays on the market, the worse-off your position will be.

    “While overall inventory [of new and old listings] grew by 28% over this same week last year, the active listings count still trails its 2020 and 2019 levels by more than 15% and 45%, respectively. More improvement in active inventory is likely needed to bring balance, but the recent trend may be at risk if homeowner attitudes toward selling now continue to deteriorate.”

    – Danielle Hale, Chief Economist, Realtor

    Once again, Hale seems to reemphasize the same underlying position. ‘We’re not in a pro-buyer’s market, we’re in a market that’s rapidly growing less favorable to sellers.’

    Are Rising Mortgage Rates to Blame for Homebuyers not Rushing to Close a Deal?

    The last question Realtor’s frequented market assessment addresses is why buyer’s aren’t rushing to close the deal. We are in a market that’s getting less and less favorable towards sellers, after all. What happens when we hit that market floor and conditions start to change against homebuyers. That has been the case – at a staggering rate – for well over two years now (Dutton, Realtor).

    In July 2022, listings lingered on the market a mere 34 days before getting snapped up. That’s nearly half the time it took two years earlier (Dutton, Realtor). Conversely, after having entered August 2022, it seems homebuyers are pumping the breaks and not feeling in such a rush. Hale’s prediction? Expect more of the same. She stated, “We expect more slowing ahead as the housing market reset”. The question remains, why?

    According to data provided by Freddie Mac, rising mortgage rates are a good place to start. For week-end August 11th, 2022, the average 30-year fixed mortgage rate increased to 5.22%. That’s considered a significantly steep spike from the previous week’s 4.99% (Mortgage Rates, Freddie Mac). Realtor predicts the future will hinge on how large corporations will view the potentially looming recession.

    “The big question for consumers is whether companies will over-react to the recession concerns and start trimming payrolls. A sharp pullback in hiring could have a direct impact on people’s ability to keep spending, especially with today’s high inflation.”

    – George Ratiu, Senior Economist, Realtor

    Realtor ultimately winds up agreeing. Prospective homebuyers should take full advantage of this buyer-friendly market while it lasts (Dutton, Realtor).

  • As Fall 2021 Approaches, Will the Housing Market Cool Off?

    Today’s hot housing market is one of the peculiar outliers to the pandemic (Campisi, Forbes). Housing supply was already low before COVID-19, however it was even further hampered, as lockdowns took place, enticing people to begin looking for new homes. Experts have attributed this to a desire to leave populated cities for better home offices during the pandemic.

    The Federal Reserve’s steps in 2020 to keep financial markets liquid and ensure mortgage rates stayed low have continued. The Federal Reserve really deserves tremendous credit for keeping the housing market solidly afloat, virtually throughout the entire pandemic.

    Housing prices nationwide, including distressed sales, grew by 17.2% in June 2021 compared with June 2020 (CoreLogic). According to the latest CoreLogic housing market report, that’s a record high. While there have undoubtedly been “hot seller’s markets” in the past, experts argue they don’t quite compare to the current market, where more than 50% of homes for sale have fetched over the asking price (Campisi, Forbes).

    “We’ve been tracking housing prices for over 20 years, and we’ve never seen anything like this.”


    – Frank Nothaft, Chief Economist at CoreLogic

    Historically, the fall ushers in less competition and thereby better deals, as children return to school and the holidays overtake schedules. But the pandemic altered that trend last year, and many cities are going through double-digit percentage increases in housing prices (Campisi, Forbes).

    Are Housing Prices Starting to Slow Down?

    While a full-fledged celebration might be too easy, prospective homebuyers can breathe a little easier. Based on predictions from real estate experts, prices are beginning to decelerate in some areas. As more inventory of single-family homes becomes available, investors can expect consumer prices to decrease further. According to the National Association of Realtors (NAR), unsold homes rose 3.3% to 1.25 million from May to June this year (National Association of Realtors). Marginally increased inventory isn’t enough to handle demand; it might give buyers hope and potentially buying leverage with more options.

    “Mortgage applications have dropped to an 18-month low, and we are seeing some real buyer fatigue in the market. Sellers are responding to lower buyer enthusiasm with price reductions.”


    – Tamar Asken, Real Estate Agent at Avenue 8, Los Angeles

    In Northern Virginia, housing prices increased 10.9% year-over-year (YOY) in June 2021, compared to the same time last year. The more affordable areas of Northern Virginia, like Fairfax City, saw a sharper rise in YOY median housing price gains like 15.1%, compared to their more expensive nearby areas like Falls Church, which experienced a significantly smaller rise of just 3.2% (Andrews, Virginia Business).

    “The market in Northern Virginia has slowed significantly during the past month, with fewer offers and longer days on market. While this would be a normal pattern in a typical year, given the intensity of the spring market, it is surprising. It could well be due to an uptick in travel as pandemic restrictions eased.”


    –Ryan McLaughlin, CEO at the Northern Virginia Association of Realtors (NVAR)

    Buyer Behavior is Becoming More Predictable and Rationale

    Succinctly, consumers flocked out to the real estate market last year (Lake, Forbes). As demand for houses picked up, interested buyers have pulled out all the stops to outbid the competition.

    This caused all sorts of strange and certainly even reckless behavior, including buyers forgoing contingencies in the sales contract meant to protect themselves and their earnest money, which can amount to thousands of dollars (Treece, Forbes). Some buyers were using retirement savings, while others were getting loans, so they could appear to be all-cash buyers.

    The good news is that experts seem to agree this “go-for-broke” approach could be declining. Whether it’s because inventory is beginning to ramp up or home prices are flattening, some buyers realize that they might be putting too much on the line. Even Asken says she is noticing that more buyers are now proceeding with caution. Keep in mind she works at a real estate company based in Los Angeles, a notoriously expensive and competitive market.

    “I do not see the same level of desperation and urgency we saw a few months ago. After large price increases, many properties just don’t feel like such a good deal anymore.”


    – Tamar Asken, Real Estate Agent at Avenue 8, Los Angeles

    Mortgage Rates and Housing Price Forecasts for Fall 2021

    While history generally indicates that during a fall is when you can get a better deal on real estate, last year contested all trends with enormous housing market sales growth recorded in the fall season. So, are we likely to see a repeat later this year? Some experts claim demand will go back to its usual cooling-off period in the fall, noting the recent expansion of inventory and retreating home prices (Ralph B. McLaughlin, Chief Economist & SVP of Analytics, Haus, Inc.).

    “I think it’s absolutely likely that price growth will slow throughout the end of the year, as they’re already slowing from their peak in June. We expect price growth to moderate to the mid-high single digits by December.”


    – Ralph B. McLaughlin, Chief Economist & SVP of Analytics, Haus, Inc.

    Nevertheless, McLaughlin added that he doesn’t expect inventory to recover fully until next spring. This is instructive specifically for current, prospective buyers. The best course of action for patiently waiting buyers is to start getting their finances in order now. Waiting to do that until a deal comes along often means you’ll be too late. This is a good time to work on your credit score. A higher score means lower interest rates, which extends to a lower monthly payment. Keep in mind that as home prices rise, so does your down payment requirement. While we’re yet to see a true “cool off” in the housing market, there is plenty of reason to suspect it will continue to slow down substantially.