Author: mperiaswamy@gmail.com

  • Key Players in the CRE Market

    Many property types within the Commercial Real Estate (CRE) market are generally agreed to have had a poor performance the past few years, largely due to the COVID-19 pandemic restrictions. Particularly, office and retail property types. The real question investors are asking themselves is whether or not it has the potential for an emphatic return, or if a commercial real estate focus is not likely to be a great long-term investing strategy. The opportunities for successful CRE investments are still there. There are still plenty of marketplaces exclusively geared towards CRE investment, which have uniquely positioned themselves in the broader real estate investing market.

    Before committing your resources to a given investment strategy, new investors should understand who the market players are for a CRE deal. Below is a thoroughly compiled list of the key players (roles) in the commercial real estate market, which then goes onto provide an additional link to a description of each role.

    Key Players in CRE :
    • Buyer & Seller
    • Brokers: Buy-side and Sell-side
    • Legal Counsel: Buy-side, Sell-side, and Lender Counsel
    • Mortgage Broker
    • Lender/Loan Officer
    • Title Company
    • Capital Partners/Investors
    • Property Management
    • Insurance Provider
    • Appraiser & Surveyor
    • Environmental Consultant
    • Accountant: Buy-side and Sell-side

    The following article shares a useful and detailed look at the key players in CRE. Refer to the link below. It provides key details about the key players in CRE’s marketplace.

    What Are The Key Players And What Are Their Roles In A Commercial Real Estate Transaction

    As a commercial real estate investor, either as a buyer or as a seller, you work with multiple parties to move a deal from discovery through to closing. To manage a deal process efficiently, it is of utmost importance to understand all of the key players in a commercial real estate transaction.

    GerCNergy.com (Administrator)
    https://getcnergy.com/knowledge-base/key-players-in-a-commercial-real-estate-transaction/
    Summary

    The above players all comprise parts of the CRE deal. It is important for a sophisticated investor to be familiar with the various players as they can understand the dynamics of a deal and align with the sponsors who will work with most of the players mentioned.

  • What’s Holding Back PropTech?

    While PropTech has seen some growth in recent years, more so before the COVID-19 pandemic, we still haven’t seen the manifestation of the scale of technological revolution in the property industry we were once promised. The vast majority of buildings we come across in our daily lives are still operating in traditional ways, using outdated but proven equipment. Let’s dive into why we are yet to see the kind of transformative innovation we were expecting on a broader scale.

    Real estate is widely recognized as the world’s largest financial asset class. However, in today’s world, we often see companies rise to prominence before crashing and burning in a matter of a few short years. Most of the biggest corporations in the world today didn’t have a trace of existence 30 years ago. The real estate asset class could not be categorized more differently. It’s not only the largest asset class (by far), it’s also the oldest asset class (Hagerty, Propmodo). Historically, the property industry is a very slow, cautious sector. Unlike an App, such as Uber for example, buildings and other construction projects take many years from the design process to the completion of the physical structure. This is attributed partially to the reality that protecting buildings and the occupants inside them is paramount. In both the residential and commercial real estate sub-sectors, moving too fast and making a mistake that may lead to a potential building collapse is simply out of the question. Due to real estate’s conservative business model, even the most sophisticated PropTech products are having a difficult time gaining broad, large-scale traction (Hagerty, Propmodo).

    Ernst & Young’s Comprehensive PropTech Study

    An Ernst & Young (E&Y) survey recently found that 43% of those who provide PropTech products are majorly struggling with widespread adoption across a given client’s business. Additionally, the same research discovered that 35% of PropTech providers are seeing a very sizable lack of scaling, as a direct result of their application being adopted. Perhaps the biggest shock from this study is 39% of respondents are yet to adopt even a single PropTech tool.

    In addition to safety concerns, the attitude of business managers has been noted as a key opponent to PropTech’s success. Value in real estate is most frequently determined by three factors: 1) location, 2) size, and 3) finishes [amenities]. Reducing costs and increasing efficiency plays a major role in the construction industry, but we don’t typically see those same levels of concern in asset management. PropTech is actually attempting to change that. With the right technology, savings from efficiency, integration, and automation can start to pile up (Hagerty, Propmodo). Having the ability to tap into data generated by buildings is providing actionable insights that are too big of a potential game-changer to ignore. For individuals or companies that already have a real estate strategy in place, implementing innovative PropTech is only putting them further ahead of the pack. Executives, board members, and direct real estate investors alike clearly understand the need for PropTech. The biggest challenge remains in implementation.

    Conclusions Drawn From Ernst & Young’s Study

    We can conclude from the E&Y study that the remedy starts with ensuring the right people are in place. E&Y found 53 percent of real estate owners don’t feel they have the in-house talent to successfully adopt new technology. It’s worth taking a moment to let that sink in. More than half of executives, or very senior personnel in a position to make these decisions, are not confident in their own teams’ implementation ability. Without technology-minded talent and leadership, it’s hard to see the light at the end of the tunnel. Traditional real estate leadership has often been hesitant – or perhaps more precisely, even negligent – in scrapping outdated systems and processes they’ve relied on for decades. Again, PropTech aims to alter that mindset entirely. Leveraging technology is about focusing on future potential, rather than cost. There are undoubtedly sizable upfront costs associated with widespread PropTech adoption across a portfolio. What makes executives and board members in particular hesitant with implementing PropTech is the mindset about their obligation to stakeholders being centered around cost cutting. Why bother spending money “fixing something” that isn’t broken? Buildings are operating just fine without the need for any sweeping, technological overhaul. That’s the position traditional real estate leadership has taken; they are extremely hesitant to tolerate large capital expenditures on risky, bold technologies that don’t have a clear trajectory of return on investment. Succinctly, from the E&Y analysis we can clearly deduce that executives and board members need to ensure there are enough personnel focused on technology to help senior management understand there in fact is a return on investment from implementing various PropTech products. It’s not as clear-cut, but the long-term financial benefits are there.

    Again, referring back to the same E&Y data, almost 60% of real estate companies surveyed responded that they find new systems difficult to integrate with existing platforms. This is viewed as a further hinderance for executives because this translates to times and resources in order to get things set up, further disincentivizing them by piling on additional costs and additionally clouding the potential return on investment. The rapid pace of development and deployment is leading to piecemeal technology strategies instead of full end-to-end solutions, which is easier for leadership to recognize. As the PropTech industry matures, consolidations, acquisitions, and a wider array of products to service every aspect of portfolios could help solve some of those problems (Hagerty, Propmodo).

    “As investors begin to see the benefit of companies adopting technology, we believe they will help drive the industry forward more rapidly in the same way that investor pressure has encouraged companies to do more and report more on ESG related issues”.

    Mark Grinis, Ernst & Young Global Real Estate, Hospitality, & Construction Leader

    Perhaps an unpopular opinion, but some have compelling arguments that growing pains in PropTech industry is actually a good thing. The real estate industry was stagnating for decades, perhaps centuries. In a few short years, technology has worked its way into practically every executive conversation or board member meeting. With that being said, retrofitting existing buildings will not be a viable solution for every – or most – property owners.  Building technology into the bedrock of the property industry is a ground-up exercise, literally, which makes taking stock of progress that’s been made that much more important. That’s where PropTech comes in. There’s plenty of obstacles in the industry slowing down PropTech at the moment, but there’s no stopping it, especially it in the long-term as we’ve seen companies rapidly expand cloud and digital transformation technologies.  

  • How the Green New Deal Would Impact Real Estate Investors

    Depending on your views on climate change, the Green New Deal framework will either conjure up enthusiasm, anxiety, or perhaps a combination of the two. The proposed bill, which has since been explained as a framework towards what we ought to work towards, calls for “maximum energy efficiency”. Based on scientific research, which concludes climate change is imminent and potentially disastrous, the proposal aims for net-zero emissions in the United States by 2050. As part of the plan to get there, this means every building in the country would need to be upgraded for maximal energy efficiency, water efficiency, safety, affordability, comfort, and durability.

    As of the start of 2020, approximately 40% of the United States’ carbon monoxide emissions come from either commercial or residential real estate buildings (Neiditch, Forbes). Many of the political proponents of the Green New Deal were pushing it behind the idea that up to $1 trillion of infrastructure and coastal real estate could be damaged by global warming by 2050. According to the Energy Information Administration (EIA), currently, there are approximately 5.6 million commercial real estate buildings in the United States. Specifically in New York City, as part of an ongoing effort to combat climate change, legislation was passed to force buildings that are larger than 25,000 square feet to make energy efficient alterations. The legislation mandates cutting down greenhouse gas emissions 40% by 2030 and 80% by 2050. While the parameters for smaller, residential buildings aren’t as explicit, it’s estimated 95 million homes will be impacted and the cost to owners will be in excess of $400 billion (Neiditch, Forbes).

    While the Green New Deal did not come close to passing as it was originally written and there is unlikely to be sweeping legislation on a national level to overhaul climate change, many cities and states are finding a balance between clean air and economic productivity. Unfortunately, a lot of this conversation tends to be intertwined with politics, but the reality is a rural area in Kentucky (as an example) is not going to have the same availability of economic or human capital resources as a metropolis, like New York or Los Angeles. The lack of availability of these resources puts constraints on the ability of certain regions to advance their technological capabilities, thereby making the real estate investment opportunities unattractive to potential investors.

    Though preparations to meet the 2030 and 2050 targets have begun, there are some more immediate upgrades property owners can make that aren’t as long-term oriented, including switching out lightbulbs for “smart” lighting, upgrading HVAC systems, installing remote-controlled window shades, painting roofs with light-reflecting paint, planting trees, and installing photovoltaics. Additionally, preparation for weatherization is key to having a more energy efficient property. Windows, doors, and insulation can all be switched out and there is legislation to include different types of incentives for property owners to make these changes. Upgrading electric and plumbing systems, as well as installing solar panels can make homes more marketable, considering these changes are becoming more prevalent to the point of necessity. Finally, the Green New Deal framework focuses heavily on “green spaces” – or lawns – that cover more than 40 million acres of land in the United States. Lawns limit biodiversity and encourage pesticide usage and emissions from lawnmowers. The Green New Deal supporters encourage the conversion of these spaces to victory gardens and the expansion of green landscape architecture practices. An example of this is xeriscaping, or sustainable, easy-to-maintain landscaping first used in arid regions, which uses native plants and limits turf areas. This can reduce outdoor water use by as much as 50%, saving water as well as the environment (Neiditch, Forbes).

    So, what does the ambitious Green New Deal framework and the implications it will have on commercial and residential real estate mean for investors? Firstly, investors should focus on high-tech, climate-resilient opportunities in the real estate market. Secondly, residential real estate owners who are not under pressure from legislators to make climate change friendly adjustments to their properties should do so anyway, otherwise they will be far less attractive to prospective investors. Finally, commercial real estate investors, who are under pressure to begin implementing climate change measures mandated by signed legislation, are going to face major hurdles with regards to cost cutting. This legislation poses further challenges to commercial real estate investors, who are already in a difficult position coming out of the pandemic, in addition to facing the necessity to transform their assets to handle the push towards digital transformation. One thing is for sure: the conversation will continue. Being prepared for change is the best way to not only save the environment, but your long-term financial stability as well.

  • CRE PropTech: How Will it be Affected by the Aftermath of COVID-19

    COVID-19 will forever change the landscape of CRE (Commercial Real Estate), especially for firms who are used to operating almost exclusively in a brick and mortar, office environment. The aftermath of COVID-19 will almost undoubtedly include more “smart” CRE. To put it another way, as software like Zoom has become a household name – whereas prior to COVID-19 it was largely known to the white-collar working class – you can expect firms to invest less in physical property. Consequently, the data shows that in every sector, at least in the short-term, PropTech investment has slowed down (Abuelsamid, Forbes).

    Intuitively, successful long-term investors tend to be heavily data driven, which has been a big reason for the slowdown in PropTech. Investors within the real estate sector are exercising caution with regards to their portfolios, as well as towards new deals for CRE projects. A great deal of this is attributed to the initial concept of this piece (which Forbes agrees with): corporations and startup firms alike are showing an increased interest in technology, which allowed them to work “smart” (i.e. Zoom) despite the pandemic (Abuelsamid, Forbes). With decreased overhead being a large incentive for startups and pressure from shareholders to cut costs being a large incentive for big corporations, many are realizing that the way they were forced to do business is perhaps a more efficient way than they were prior to the COVID-19 pandemic.

    With that being said, as we mentioned in a previous piece, PropTech is still a relatively new field to most investors. The CRE investing subsector of PropTech is even smaller, so there’s definitely still plenty of opportunity for successful PropTech investment vehicles. Even with the current data showing there’s slowed growth in the PropTech CRE subsector, that’s not to say you shouldn’t keep an eye out for solid investment opportunities, as they are still out there and can definitely be lucrative. This is the main reason you’ll typically find seasoned, experienced investors in the CRE PropTech space. There is opportunity for large returns, but it is definitely slim.

    In the longer-term, there’s no reason right now to believe firms will switch back to investment in more physical property, especially when that money can be spent on human capital. Therefore, if you’re interested in PropTech investment strategies, you should not expect to see consistent positive performance from PropTech CRE investments. On the other hand – while this subject deserves a complete discussion on its own – residential PropTech is definitely on the rise (Aramati, Forbes). With a major push coming from cloud technologies and digital transformation, there’s a lot more investment in “smart” residential real estate as opposed to commercial real estate. Generally speaking, investments in “smart” technology have gained a tremendous amount of traction and thereby very large returns for earlier stage investors. Again, as we discussed in a previous article regarding PropTech, technological advancement is the future and investors who are looking for the next Amazon or Google in the real estate market ought to look into residential PropTech options with a more favorable outlook than commercial PropTech.

  • PropTech: What is it and Who Are the Primary Investors?

    Property Technology, commonly known as PropTech, refers to the use of Information Technology (IT) to assist both individuals and companies buy, sell, research, and manage real estate. While still a relatively new field, the convergence of technologies, cloud, and digital transformation are key forces driving PropTech forward. The goals of PropTech include: minimizing the cost and resources associated with real estate transactions, maximizing efficiency, saving time, and personalizing property management. This concept is similar to FinTech, where the focus is on the use of technology in finance. PropTech utilizes digital innovation and other technologies to address real estate market participants’ needs in the property industry.

    Efficient PropTech is specifically devised to streamline processes and connect market participants in all aspects of real estate. Therefore, PropTech directly impacts buyers, sellers, brokers, lenders, landlords, as well as others. One of the most popular current PropTech technology is virtual reality software, which allows prospective buyers to virtually walk through properties, construction sites, and more. Additional well-known PropTech technologies include software for reporting repairs, splitting rent payments, and crowdfunding new real estate projects.

    At this time, PropTech consists of three major market segments: (1) smart home, (2) sharing real estate, and (3) real estate FinTech.

    Smart Home

    A smart home is equipped with digital platforms that monitor, manage, or operate specific property assets. Amazon Echo’s Alexa is an example of something in a smart home. Generally, they are comprised of digital platforms that monitor, manage or operate specific property assets. Other examples could be something a security surveillance system that warns property owners of a threat, a smart thermostat that regulates the temperature of uninhabited units, or smart light bulbs that can be turned on by a smartphone app or digital assistant.

    Sharing Real Estate

    This refers to technology that facilitates the processes involved with sharing or renting real estate assets, such as land, offices, storage, apartments, parking lots, and more. For example, there could be a software that facilitates automatic online payments for retail spaces occupied in a building owned by a property management company.

    Real Estate FinTech

    This segment of PropTech includes applications that involve buying and selling real estate assets. A platform that reduces the amount of physical paperwork and documentation involved in a home purchase can be thought of as an example. Stay tuned for a deeper conversation regarding the relationship between PropTech and FinTech.

    With PropTech still being a relatively new field, the investors are largely comprised of wealthy, seasoned real estate investing experts (or at least those with a real estate investing background). In addition to being backed by some of the world’s largest real estate giants, it would be fair to say most of the individuals behind the world’s biggest tech companies, agree that future technology is pushing towards digital transformation (Donati, Forbes). Therefore, you’ll find investors that are interested in a sort of ‘futuristic’ technology category when it comes to financial investments. For example, PropTech investors would be very likely to also be interested in FinTech and Cryptocurrency. While the latter two seem to be more popular at the moment, PropTech is definitely something well worth looking into, especially if you have a specific interest in real estate investing.

  • Homebuyers: Five Tips for Financing and Budgeting

    When it comes to home buying, there’s a well-known critical rule: Avoid purchasing more house than you can afford. However, what represents “affordable” will differ between homebuyers. Therefore, one of the most important things for a first-time home buyer to do is plan and budget in advance. Diving into a potential multi-decade financial commitment is one of the most daunting experiences for an individual (or a couple, for that matter) in their lives. It is also highly probable that it will be your most expensive purchase. Before doing so, strategically allocating your money is essential. Otherwise the costs are steep. Before you know it, you may quickly find yourself getting buried in financial hardship, or the ultimate worst nightmare: foreclosure. To avoid this, we recommend the following five tips for first-time homebuyers.

    1. Strongly consider getting started with the “28 Percent Rule”

    The “28 Percent Rule” dictates that your mortgage shouldn’t be more than 28% of your gross income each month. While the Federal Housing Administration (FHA) recommends a slightly more generous allowance of 31%, first-time homebuyers in particular ought to air on the side of caution, considering they are likely repaying some other forms of debt. Additionally, there are the normal monthly expenses (food, transportation, healthcare, etc.) that any working-class individuals would have to account for.

    2. Your down payment should dictate your home’s budget

    Generally, lenders will look for homebuyers to put at least 20% of the property’s purchase price in cash. Though you can utilize other resources to obtain an approval, such as private mortgage insurance (PMI), this will inflate your monthly mortgage payment by roughly 1% (Fuscaldo, Investopedia). It’s important to note that the PMI depends significantly on the size of the property, your credit score, and the potential for the value of the home to increase over time. It’s equally important to note that it is in your long-term best interest to avoid these kinds of instruments, as they’ll tie up more and more of your monthly disposable income in interest repayment. On top of everything else, it’s critical to remember closing costs, as they’ll cost you anywhere from 2-5% of the home’s purchasing price, depending on what state you live in (Fuscaldo, Investopedia). Avoid over-leveraging yourself. Put as much money down as you can afford to, but certainly aim for higher than the bare minimum 10%.

    3. Precisely track your debt-to-income ratio

    It’s a very well-known fact that mortgage lenders will look at a prospective homeowner’s debt-to-income ratio when determining if they will extend a loan to the borrower. Therefore, keeping track of this ratio on a monthly basis is a good benchmark for prospective homeowners to calculate themselves, in order to ultimately decide if a home they’re interested in is affordable. Suppose your gross monthly income is $5,000. Then, if your mortgage payment is $1,500 and the total of your other monthly financial obligations is $1,000, this puts your debt-to-income ratio at 50%. Qualified mortgage lenders very rarely will approve a borrower with a debt-to-income ratio above 43%. Thus, in the above example the hopeful homeowner would unlikely to get approved and even if they did, it’s probable they would be setting themselves up for failure.

    4. Don’t forget all homeowner expenses, not just the monthly mortgage

    There’s no question getting approved for a home loan is an essential step in the process, yet this is only one obligation (though it’s by far the largest). The tough reality is your monthly mortgage payment will not be your only reoccurring expense as a homeowner. Consider additional monthly homeowners’ insurance, utilities, repairs, and maintenance costs. Depending on the season, the snow will need to be shoveled, or the lawn will need to be mowed, or the shrubs will need to be trimmed. Many find that over time, the list just keeps growing. When you calculate the affordability of a home, you may find that an affordable $1,500 monthly mortgage payment is no longer palatable when you factor in an additional $1,000 in monthly expenses. This is a large reason behind the idea of putting a considerable downpayment on the home; it frees up money for those other monthly costs, rather than irresponsibly squandering it on interest.

    5. Settle on a property you can handle managing

    Not only are the additional monthly homeowner expenses important to factor in, but you also need to be mindful of the condition and size of the property. In a situation when you’re concerned about a large utility bill from heating or cooling, less is more. A 4,000-square-foot property that needs serious repair may be a tempting proposition, until it breaks the budget. You may find you’re better off financially with more of a picturesque small home on a quaint hill, in a quiet neighborhood instead. For your own benefit, have a construction or homeowner expert look into the homes specifications to ensure you haven’t missed anything vitally wrong.

    The bottom line is that to many, home ownership is still considered to be the American Dream. In reality, it can quickly turn into a financial nightmare when you miscalculate your monthly expenditures. First-time buyers in particular often want more than they can take on at that moment. Without taking the time to properly prepare for the single biggest purchase of one’s life, they can find themselves house-rich and cash-poor, leading to ultimate financial misery. We urge any future homebuyers to take the necessary preparation steps. Do not sign up for a dream you are not exceptionally confident you can afford.
  • NYC Real Estate Market Mid-2021: Are You Better Off Buying or Renting?

    Since New York City’s (NYC) real estate market is still experiencing a fresh post-COVID effect, you are better off buying if you have the money (and credit score). However, as is often the case, it greatly depends on your financial situation. Living in arguably the most desirable and expensive part of the world presents a financial burden to many younger adults, who are still working lower paying, entry level jobs.

    The majority of real estate property owners in New York City are of older age and in the highest income brackets (NYU Furman Center). Additionally, they are more likely to have permanent ownership of property in other locations (Goldstein, Property Nest).

    Many people view renting as ‘wasteful’ because you don’t have the benefit of acquiring equity in your property. However, the reality is for most young or middle-aged professionals, the economic opportunities – combined with the cost of living in New York City – don’t allow them to acquire enough requisite disposable income to put a down payment on a desirable apartment unit. This brings up a primary obstacle many residents of New York City see with buying a permanent unit: most people don’t view New York City as their ‘final destination’, long-term residence. In other words, when most people think about taking out a mortgage and buying a home, they’re thinking about a serious long-term commitment (emphasis on long-term). Raising kids, settling down in a permanent work situation, and finally retiring. The suburbs or a quiet town; not the most densely populated, most popular tourist destination in the world.

    While there are plenty of mechanisms available to individuals looking to get out of a 20 or 30-year mortgage after only a few years, logically, it would make sense for most to still prefer not to take on that kind of serious financial responsibility without the intent of staying in that location for a while.  

    With that being said, from the perspective of someone simply asking: “hey, would I be better off buying or renting in New York City?”, I would advise them to not be hesitant and buy if they have the money saved.

    The reason is two-fold. If you are going to live in the unit, at least initially, you’ll acquire equity simultaneously. If you find that NYC is not for you in a few years – as many inevitably do – current market prices and historic trends, combined with current rates and incentives, suggest one would be able to see a positive cash flow from subleasing or subletting their own property. Meaning, renters are consistently earning more monthly rent than their monthly mortgage payments. Alternatively, if you have no desire of becoming a landlord, contrary to ordinary homeowner’s beliefs, there is the ability to sell your mortgaged property and earn a profit. It’s extremely difficult to look at the recent data without considering the COVID-19 situation, but over a 10-year period prior to that, real estate prices were significantly increasing year-over-year.

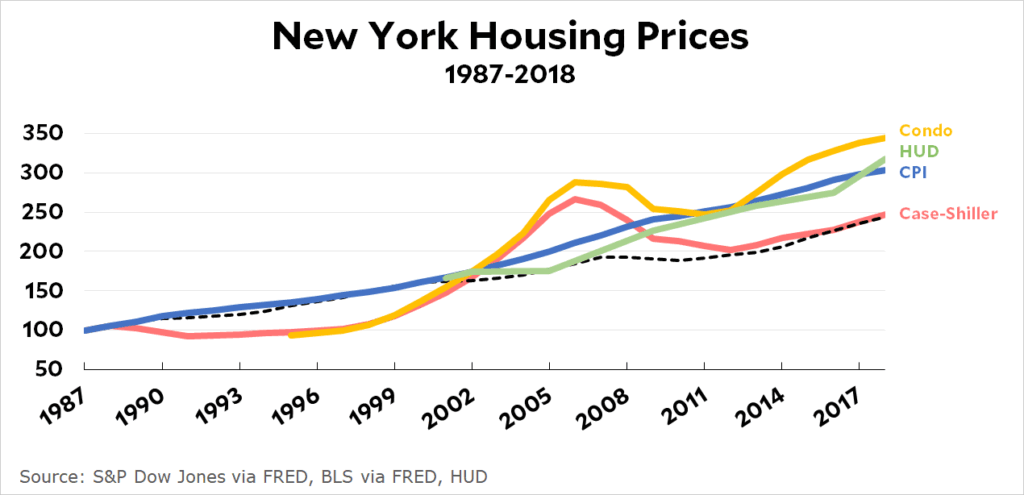
    That’s largely why real estate became viewed as a very popular investment vehicle for financial investors. The figure below illustrates an average of New York housing prices over a 30-year period, between 1987 and 2018, from different housing market segments.

    Figure 1 – New York (NYC) Housing Market Prices (1987-2018) Overview

    As one can see, prices went up across the board mostly every year, with the exception of a rocky period in the midst of the Great Recession of 2008. Therefore, having more ownership/equity in a property that’s also going to increase in value over time is a no brainer, even if you choose to move out of that property prior to paying off your mortgage.

  • Why Real Estate Investors Refer to Real Estate as an I.D.E.A.L. Investment

    Many real estate investors are familiar with the acronym ‘I.D.E.A.L. Investment’ in the context of real estate investing (Chad Carson, Coach Carson). This acronym is a great, succinct explanation for why real estate is preferred by many investors to other vehicles like dividend stocks, bonds, small businesses, index funds, bank certificate of deposits, annuities, and more.

    Income

    Real estate properties provide excellent cash flow on a regular (typically a monthly) basis and the income size can be quite substantial, depending on your properties’ interest rate, unpaid principal, and property value. This is the primary objective of any investor, which makes real estate a top choice for many. If you aren’t seeing much or any cash flow from an investment, especially after a lengthy period of time, typically it’s not a very successful one.

    Depreciation

    Another big advantage to real estate investing was actually made widely known by Donald Trump in the 2016 presidential campaign; depreciation. Depreciation occurs because for residential buildings, the U.S. government requires real estate investors to spread out most of the cost of real estate purchases over 27.5 years. This creates an annual depreciation expense, which can provide incredible tax benefits. This ‘expense’ doesn’t come out of your bank account, like purchasing materials to sell products, or insurance/maintenance costs. Instead it’s absorbed ‘on paper’ and you see real financial benefits in the form of tax relief.

    Equity

    Generally for real estate investors, as time goes on the more equity they’ll acquire in their own properties by repaying loans, which is directly linked to greater overall wealth. The shorter it takes you to pay off your own financial obligations on a property, the larger your ROI will be. Additionally, you’ll be able to optimize the length of time you’ll see financial benefits from that investment. While it may depend on your financial situation and the real estate market climate, real estate investing is a great way to acquire equity and see positive cash flow simultaneously.

    Appreciation

    Appreciations refers to the idea that your property value is supposed to increase each year. As we’ve seen in recent years, this may not necessarily be the case (primarily due to unpredictable circumstances). However, long-term investors (who comprise a very large segment of real estate investors) are satisfied with the long-term average of property values visibly pointing towards an upward trajectory.

    Leverage

    Leverage can refer to two distinct advantages of real estate investing. Firstly, some indicate this means the initial incurrence of debt leading to equity growth over time (this appears to be covered by ‘Appreciation’). Secondly, leverage can more commonly refer to the idea of using other people’s money (OPM) to earn a positive cash flow. This gives investors the opportunity to use relatively small amounts of cash upfront to gain control over multiple investment properties and earn returns on cash invested. This method isn’t typically used by passive investors, who would be concerned with over-leveraging and what could happen if there was a steep decline in the housing market.  

  • What is a Tri-Party Repo (TREPS)and How Did the Market Operate?

    What is a Tri-Party Repo (TREPS)and How Did the Market Operate?

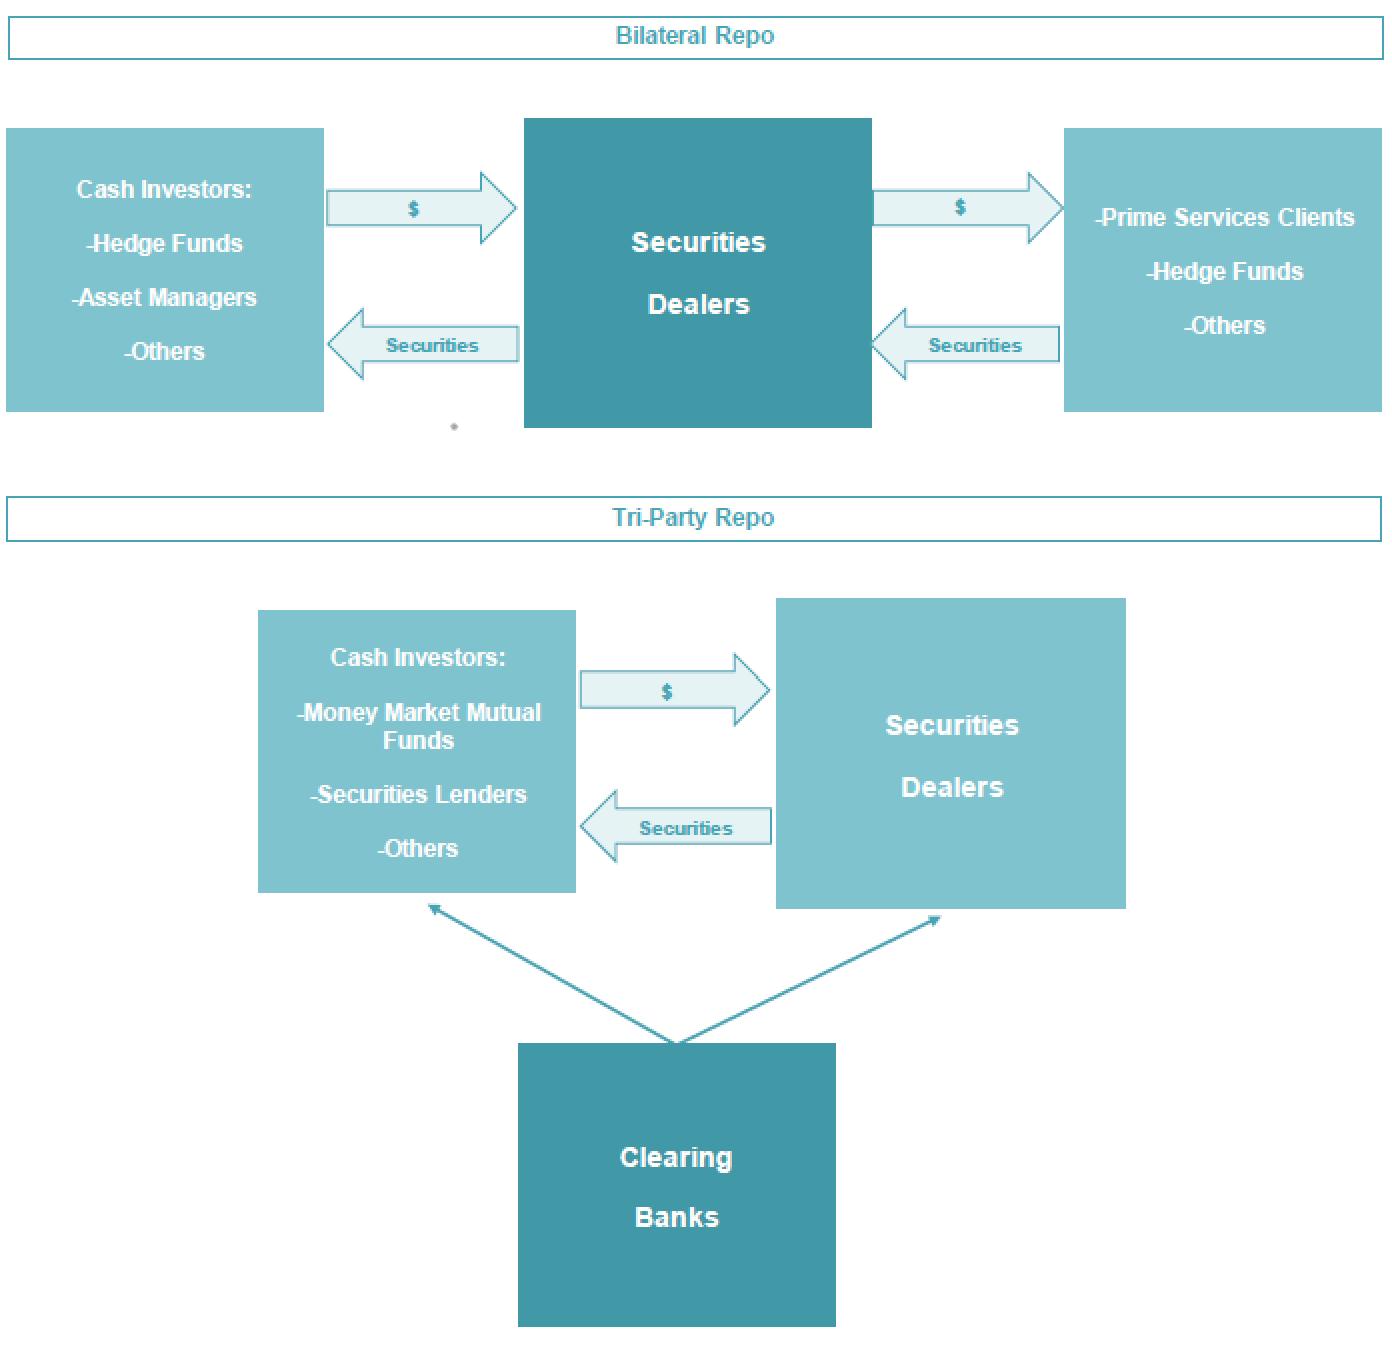
    The simplest way to understand a tri-party repo (TREPS) is to think of it as a simple repurchase agreement between two parties, where a third-party – historically a very large and reputable bank (only JPM Chase or BNY Mellon, during the time these transactions were widely common) – processes administrative work and even guarantees the cash provided by Company A to Company B and the collateral Company B secures the cash from Company A with. These third parties, commonly referred to as clearing banks, also performed valuation services to ensure the collateral put up by Company B was within the approximate fair market value of the cash lent by Company A.

    Tri-Party Repos in the Derivative Era

    These transactions actually became popular at the “boom” of the derivative trading era – even though they had a comparatively low-yield percentage for both companies – mainly because of mechanics of how these transactions occurred. They were typically cleared and settled overnight, so the investment banker would have the cash available in the morning when the trading day began. The “unwinding” process of this repo would also happen after the trading day was complete; the dealer (Company B) would finance the broker (Company A) with cash and the third-party clearing bank would take care of the rest for a small fee.

    To be clear, the responsibilities of the clearing banks weren’t minuscule, they were tasked with: taking custody of the securities involved in the repo, valuing the securities and making sure that the specified margin is applied, settling the transaction on their books, and offer services to help dealers optimize the use of their collateral. However as mentioned, to give dealers access to their securities during the day, the clearing banks settle all repos very early each day, returning cash to cash investors and collateral to dealers. This would lead to a delay in real-time settlement, therefore in reality the clearing banks wind up extending hundreds of billions of intraday credit to the dealers until new repos are settled in the evening.

    Role in 2008 Financial Crisis

    It’s argued by many to have played an underscored role in the 2008 US Financial Crisis, primarily because between 2007-2009 these repurchase agreements became a common daily routine for almost all of the largest brokers and dealers in the world. This was for several logical reasons. Firstly, it made sense for securities brokers to engage in because they have access to cash immediately, the second the daily trading day begins.

    It equally makes sense for dealers. They are receiving a profit from lending cash and they have the comfort of knowing their cash is backed by collateral that was signed off on by either JPMC or BNYM. Finally, it makes sense for the clearing bank to use their economies of scale and human resources to make a couple percentage points. At the time this was thought to be routine administrative clearing bank procedure. However, it turned out to be a much bigger nightmare than ever imagined.

    The nightmare catch is best described by the following scenario. Contemplate what happens if you have a very large and highly levered broker, like Bear Sterns as the famous example. You then encounter a situation where financial markets they have heavy exposure in drop sharply. The collateral a broker like Bear Sterns would put up would be in the form of a portfolio of securities. They wouldn’t contribute any physical assets, or guaranteed/risk-less investments (like T-Notes).

    Where Systemic Financial Fragility and Potential Crisis Begins

    Now you have a situation where the dealer (Company B) may not feel as comfortable providing liquid cash financing to Bear Sterns anymore. Then you essentially have the clearing bank – JPM Chase or BNY Mellon – incurring the loss because the process was done so hastily. They almost certainly never took the time to deeply look into whether the collateral put up by Bear Sterns was equal in liquid valuation to the cash provided by their various dealers (who by the way would usually be institutions like secondary education private schools, or institutions in a medical (or other) field with a surplus of cash), so the settlement process only occurred on paper for them.

    When things went south, even though the clearing banks do not match dealers with cash investors. Nor do they play the role of broker in that market. They had to settle disproportionately valued securities with the most liquid form of financial currency: cash. Looking at Bear Sterns, they would’ve used dozens of cash lenders to diversify. Even more so the clearing banks would be incentivized to not look too closely at their spotted collateral. Picture what happens if you have Lehman Brothers, Goldman Sachs, and Morgan Stanley incurring the same scenarios. The same day, as well. Of course Goldman Sachs and Morgan Stanley are two of the most prestigious investment banks in the world. Likely not enough of their total portfolio was invested in the tri-party repo market to cause them to fail.

    Conclusion

    However when that market did ultimately fail, things went that route for Lehman and Bear Sterns. Concisely, while on the surface a tri-party repo is a simple repurchase agreement where a third party provides administrative surfaces at a small fee for the two companies engaged in the repo, understanding the mechanics of it are invaluable to appreciating how some financial markets collapsed so rapidly in late 2008.

  • What the COVID-19 Vaccine Means for NYC’s Real Estate Market (May 2021)

    What the COVID-19 Vaccine Means for NYC’s Real Estate Market (May 2021)

    As of the beginning of May 2021, in New York City 48.9% of New Yorkers have received one dose of the COVID-19 vaccine, while 37% have been fully vaccinated. This coverts to 7.19 million people fully vaccinated, compared to approximately 106 million nationwide, or 32.3% of America’s total population. Though the vaccinations have slowed down from their initial surge in NYC, their apparent effects on the real estate market were what sellers and renters were hoping for.

    The relatively mass availability of vaccinations seemed to provide a sense of stability to the real estate market in NYC; renters and sellers appear to now be able to gauge price and demand more easily. Additionally, according to Realtors, both average prices for rentals and sales in NYC have continued to rise these first five months of 2021, as the COVID-19 vaccinations became more and more available. In almost all prestigious NYC locations, studio apartments are now consistently renting for over $2500 per month and 1-bedroom apartments are averaging close to $3500 per month. These are more like the numbers we witnessed prior to the COVID-19 pandemics and prior to the moratoriums issued by the State of New York and City of Manhattan, which undoubtedly temporarily created downward pricing in the NYC real estate rental market.

    Other housing statistics from Realtors offer the same conclusion: the stability of real estate prices in NYC have certainly increased by an upward trajectory. Steven James, President and CEO of Douglas Elliman, said there will be an immediate increase in activity once the vaccine is approved. He hinted that the best “opportunity is now” for prospective real estate investors because prices will only continue to increase proportionate to the amount of New Yorkers and Americans who get fully vaccinated. George Ratiu, a senior economist at Realtors, echoed Steven’s point by predicting “a gradual shift over the next six to eight months” in rising real estate prices in NYC.