Tag: real estate investing

  • Why bother to invest in Commercial Real Estate?

    Investing in stocks or bonds has become so easy and widespread with advances in technology, with the likes of Robinhood. It also makes us wonder why invest in other asset classes like Commercial Real Estate (CRE) in the first place? In this article, we will attempt to answer this question. Along the way, we will also try to appreciate the risk profile and pros and cons of the three major asset classes – stocks, bonds, and real estate.

    As we look into the three major asset classes – stocks, bonds, and real estate – we will review the basis for portfolio diversification to manage risk. We will also look into the performance of the major asset classes in the past 15 years to see how they have performed relatively. Finally, we’ll see the relative tax and other advantages of the various asset classes as that will affect the bottom line to the investors.

    Portfolio diversification among asset classes

    You must have heard the oft-repeated phrase “don’t put all your eggs in one basket”. Though cliched, it is the idea behind portfolio diversification. In financial terms, the intent of portfolio diversification is to reduce overall volatility and enhance risk-adjusted returns. As we have seen in previous FinYork articles, investing is all about having an investment strategy in accordance with one’s risk tolerance and executing on that strategy. Hence, portfolio diversification is a key tenet of investment strategy.

    Here’s a chart from Savills on how much the world is worth divided into various asset classes. Real estate refers to residential real estate and CRE market size is $32 Trillion. It comes after Debt (Bonds) and Equities (Stocks) and only growing. Essentially, CRE is a major asset class globally.
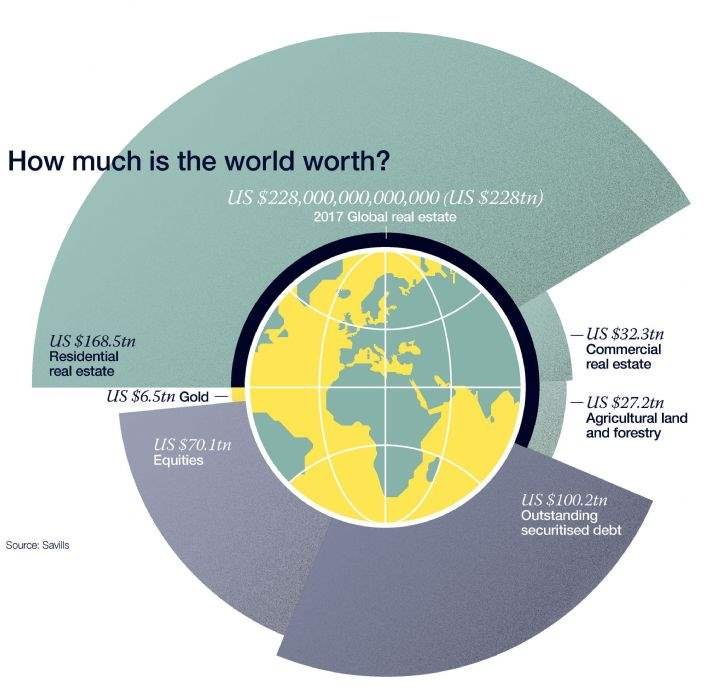
    How much is the world worth
    Source: Savills

    When added to a stock and bond portfolio, real estate can provide diversification benefits as real estate has historically shown a low correlation to stocks or bonds. There have been a couple of instances when all asset classes move together as in the Great Financial Crisis (GFC). Still, it is fair to say that the addition of real estate to a mixed-asset portfolio may lower overall volatility and enhance risk-adjusted returns.

    Real estate is likely the first asset class that we got exposed to whether it is to live, study, play, or work. Even if everything falls apart, humans need people need built space to sleep, live, and work. Simply put, humans cannot live without real estate. This provides a powerful argument for the longevity of the asset class and why a portfolio must have exposure to an asset class that meets the basic needs of humans.

    Long-term investment returns

    As of Feb 2021, stock markets are at all-time highs even though it has not been a good year for certain real estate property types like retail or hotels. Let us rewind a bit and look at asset class returns over a longer period. We found the following chart from Novel Investor that compares asset class performance since 2006. As it turns out, REITs (real estate securities) came out on top the most in 6 of the 15 years tracked. Including the 2007-2008 great financial crisis (GFC), which was triggered by real estate, REITs have performed well.
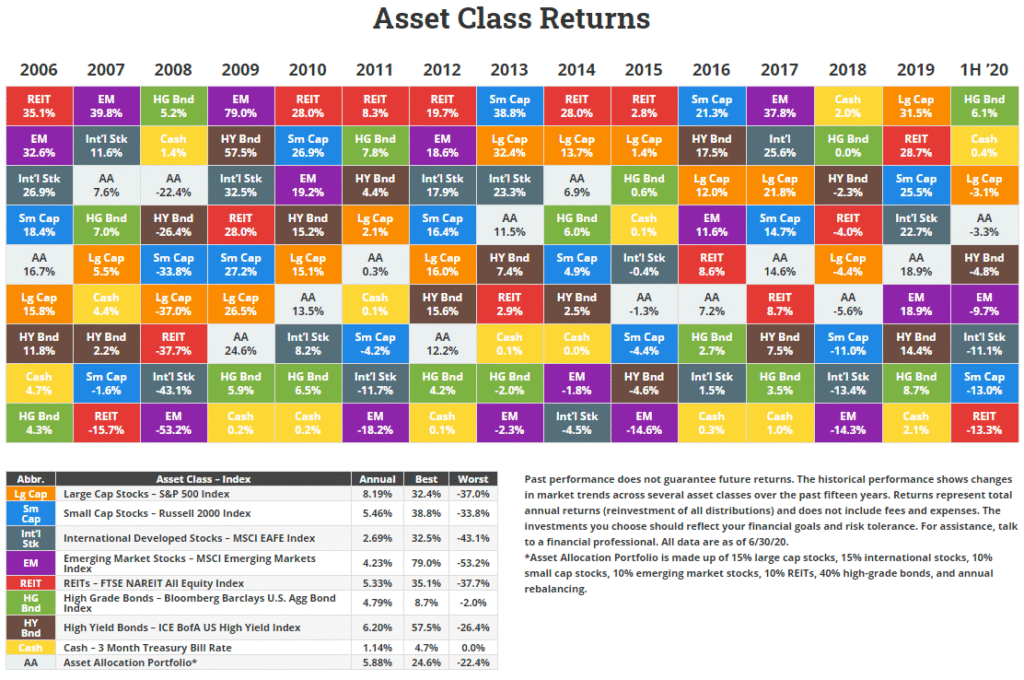
    Asset Class Returns 
2006 
35.1% 
Int'l Stk 
Sm Cap 
16.7% 
Lg Cap 
HY end 
11.8% 
HG end 
4.3% 
Abbr. 
Int'l 
end 
2007 
Int'l Stk 
11.6% 
7.6% 
HG end 
Lg Cap 
Cash 
HY end 
Sm Cap 
-15.7% 
2008 
HG end 
1.4% 
-22.4% 
HY end 
Sm Cap 
Lg Cap 
Intl Stk 
-411% 
2009 
HY end 
57.5% 
Intl Stk 
Sm Cap 
Lg Cap 
HG end 
2010 
Sm Cap 
HY end 
Cap 
15.1% 
13.5% 
Int'l Stk 
8.2% 
HG end 
0.2% 
2011 
8.3% 
HG end 
HY end 
Cap 
2.1% 
0.3% 
Cash 
Sm Cap 
Intl Stk 
-11.7% 
-18.2% 
Annual 
8.19% 
5.46% 
2.69% 
4.23% 
5.33% 
4.79% 
6.20% 
1.14% 
5.88% 
2012 
19.7% 
Intl Stk 
17.9% 
Sm Cap 
Lg Cap 
HY end 
12.2% 
HG end 
0.1% 
2013 
Sm Cap 
Lg Cap 
Int'l Stk 
11.5% 
HY end 
7.4% 
HG end 
2014 
Lg Cap 
13.7% 
HG end 
Sm Cap 
HY end 
Intl Stk 
2015 
2.8% 
Lg Cap 
1.4% 
HG end 
Int'l Stk 
-0.4% 
Sm Cap 
HY end 
-14.6% 
2016 
Sm Cap 
21.3% 
HY end 
17.5% 
Lg Cap 
11.6% 
REIT 
7.2% 
HG end 
Stk 
1.5% 
2017 
Int'l 
25.6% 
Lg Cap 
21.8% 
Sm Cap 
14.6% 
REIT 
HY end 
3.5% 
2018 
Cash 
HG end 
HY end 
REIT 
Lg Cap 
Sm Cap 
-11.0% 
Int'l Stk 
-13.4% 
-143% 
2019 
Lg Cap 
31.5% 
REIT 
28.7% 
Sm Cap 
Int'l Stk 
22.7% 
18.9% 
18.9% 
HY end 
2.1% 
IH '20 
HG end 
6.1% 
Lg Cap 
-3.1% 
HY end 
Stk 
-11.1% 
Sm Cap 
-13.0% 
REIT 
-13.3% 
Asset Class - Index 
Large Cap Stocks - S&P 500 Index 
Small Cap Stocks - Russell 2000 Index 
International Developed Stocks - MSCI EAFE Index 
Emerging Market Stocks - MSCI Emerging Markets 
Index 
REITs - FTSE NAREIT All Equity Index 
Hi h Grade Bonds - Bloomberg Barclays U.S. Agg Bond 
In ex 
High Yield Bonds - ICE BofA US High Yield Index 
Cash -3 Month Treasury Bill Rate 
Asset Allocation Portfolio* 
Best 
32.4% 
38.8% 
32.5% 
79.0% 
35.1% 
8.7% 
57.5% 
4.7% 
24.6% 
Worst 
-37.0% 
-33.8% 
-43.1% 
-53.2% 
-37.7% 
-2.0% 
-26.4% 
0.0% 
-22.4% 
Past performance does not guarantee future returns. The historical performance shows changes 
in market trends across several asset classes over the past fifteen years. Returns represent total 
annual returns (reinvestment of all distributions) and does not include fees and expenses. The 
investments you choose should reflect your financial goals and risk tolerance. For assistance, talk 
to a financial professional. All data are as of 6/30/20. 
*Asset Allocation Portfolio is made up of 15% large cap stocks, 15% international stocks, 10% 
small cap stocks, 10% emerging market stocks, 10% REITs, 40% high-grade bonds, and annual 
rebalancing.
    Source: Novel investor Asset Class Returns

    Income Potential

    Real estate is in many ways different than a popular high-tech stock that may have doubled over a couple of years. For e.g. real estate offers investors relatively steady and recurring quarterly or monthly income that comes from operations. Many property types in real estate historically involved multi-year lease agreements (e.g. office leases) and hence the cash flow also tends to be relatively predictable and long-term in nature.

    On the other end, an investor may be getting zero returns in her savings accounts. Relatively speaking, real estate offers higher yields for such investors. When the cash and equivalents produce close to zero interests. A lot of people (e.g. retirees) need steady and stable cash flows.

    Inflation hedge and tax advantages

    The fourth benefit real estate provides – inflation hedge and tax advantages. This is very powerful because it can make a big difference to how much money you can actually pocket. Compared to other asset classes, CRE provides a level of inflation protection. How does it provide protection? Real estate leases for the most part incorporate rent increases based on inflation. You may be familiar with your annual house or office rent increase based on inflation. In addition, property values also appreciate based on input costs. If the cost of input like construction material or amenities increase due to inflation, so does the property price and value. The above also doesn’t take into account inflation i.e. it assumes the dollar value is the same in 2006 as it is in 2020. We know that a dollar can buy less of gas or milk than before.

    Investing directly in hard assets provides tax advantages in most countries. Tax policies favor real estate investing in many countries including the USA. For stocks and bonds, you’d have to pay taxes on interests, dividends, and capital gain. Depreciation and other treatment can lead to a paper loss when filing corporate or individual taxes. Hence, your tax burden may actually be very less. This deserves in-depth treatment and we will cover it in the future, but let us remember that many countries have historically provided very favorable treatment to the real estate sector.

    Investor takeaways

    We looked at the major asset classes and the role real estate can play in a portfolio to provide diversification. Real estate can help some investors meet their diversification strategy according to their risk tolerance. Looking at the long-term investment returns of various asset classes securities, Real Estate performance has actually been good in the long run. Scars of the Global Financial Crisis remain and COVID-19 will continue to be a challenge for many real estate property types.

    We also compared the asset classes using inflation and a tax lens. Of all the asset classes, real estate provides the most inflation hedge and tax advantages due to real estate advantageous tax policies in many countries.

    In summary, it may be worth investing in Real Estate as an asset class. We at FinYork believe all asset classes have a role to play in a portfolio, though we’ll be the first to admit we’re biased towards the real estate asset class. We also believe the real estate asset class is going to become more available and accessible to investors in the years to come. We want all investors to learn and benefit from this asset class. We plan to have a corresponding article on why NOT to invest in real estate. We encourage you to read both the articles and come to your own conclusions.
  • Sources and Uses of Funds

    Sources and Uses of Funds

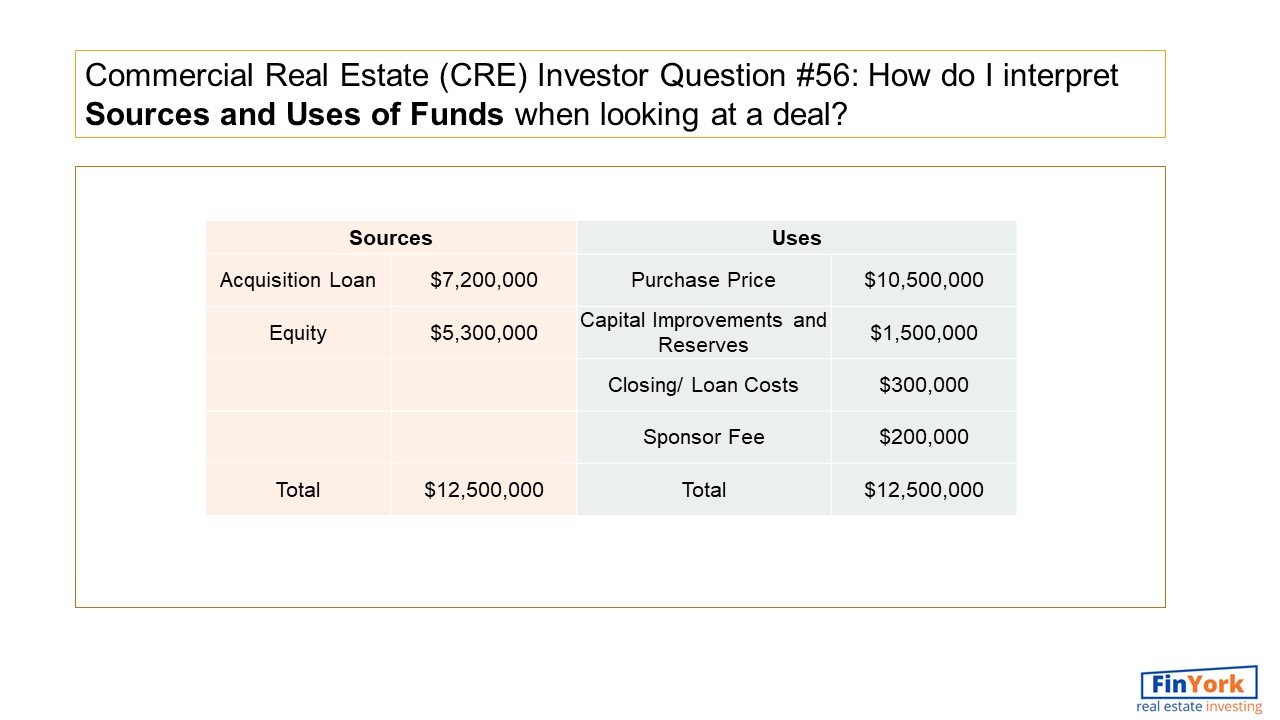
    Commercial Real Estate (CRE) Investor Question #56: I am looking at a CRE deal. Can you explain the sources and uses of funds?

    Sources and uses of funds is a summary view of capital needs of the deal (uses) and how the capital will be raised (sources). This should be a key part of any pitch of the sponsor and should give a high level idea of the capital stack (debt vs. equity) and the overall costs including fees to close the deal. An example snapshot is provided in the featured image.

  • General Partner & Limited Partner

    Commercial Real Estate (CRE) Investor Question #55: I am looking at a real estate syndicated / private placement / private equity deal. Who is a General Partner(GP) and who is a Limited Partner(LP)?

    General Partner is typically the sponsor or operator responsible for finding the deal, setting up the deal, handling the transaction, securing the financing, managing the investment, and eventually selling it.

    Limited Partners are passive investors and they contribute capital to the syndicate to earn a return on their investment. LPs benefit from having limited liability in the investment.

    For a more detailed treatment, check out the article.

    #finyork #100crequestions #cre #commercialrealestate #investing #creinvesting #alternativeinvestments

  • Where to put your assets to work?

    We looked at how understanding our risk tolerance and setting goals is the first stage of investing in a previous post. What do we do once we understand our risk tolerance and the goals are set? The next step is to have a basic idea of the investing universe and determine the areas to put investment dollars to work.

    Many individual investors have a typical journey when it comes to investing. We would have started with savings accounts or CDs and then moved to dabbling in stocks and bonds. It is also very likely that many were forced to manage our retirement portfolios when we started working and got introduced to mutual funds and index funds. Along the way, some may have got exposed to real estate, commodities, or derivatives.

    In essence, many individual investors do not have the opportunity to look at their portfolio holistically. After all, most of our time is consumed with our daily job and family commitments. The purpose of this article is to provide a holistic picture of investing. We will go through the various investment options available for investors to put their assets to work. We’ll get some ideas from top institutional investors who have performed well in the long run.

    Myriad of Investing options

    An investor has a myriad of investments to choose from these days. We may have heard about many of these investments, but we may have just invested in one or two of them. It can sometimes be confusing and sometimes daunting.

    Unfortunately, investing is not taught for many in school or college and hence we don’t have any structured approach or framework for investing to follow. Let us first understand the myriad of investment options available. In the financial world, the various investment options are also called asset classes.

    An asset class is a grouping of investments that exhibit similar characteristics and are subject to the same laws and regulations.

    https://www.investopedia.com/terms/a/assetclasses.asp

    The major asset classes are depicted below. Historically, the  popular asset classes have been stocks, bonds, cash-equivalent, commodities and real estate as depicted below. This misses some of the relatively newer investing options like private equity, hedge fund, derivatives and cryptocurrencies.

    https://www.franklintempletonindia.com/investor/investor-education/video/understanding-asset-classes-io04og31

    If you’re interested further in evaluating the various asset classes, nerdwallet has a detailed review of major asset classes.

    How do you allocate the assets?

    Understanding asset classes provide a lay of the land or big picture that will help you chose the asset classes that you can invest in. Understanding various characteristics of the asset classes helps you diversify your assets (the often used “don’t put all your eggs in one basket”).

    The key is to understand the characteristics of an asset class, whether you invest in it or not. For e.g. when one thinks of transportation, one intuitively understands the difference between various modes of transportation – cars, trucks, trains, buses, planes, etc, and their characteristics. Assets classes are similar when it comes to characteristics between the various asset classes.

    There are various traditional asset allocation calculators available to help allocate the assets. Many of them only consider traditional assets – stocks, bonds, and cash – only. We’ll see in the upcoming section, why investors should also consider diversifying beyond these traditional assets.

    Yale University’s Asset Allocation

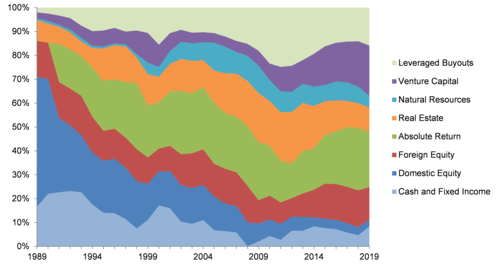
    Let us look at industry leaders when it comes to investment performance. We can look at enterprises with a good record of investment returns. Yale University is one of them. Yale University is known for its portfolio performance as it has performed better than many peers and many college endowments compare themselves to Yale’s endowment performance. Let us take a look at Yale’s portfolio below.

    AA FY19.png
    Source: Yale Investments Office

    As we can see, Yale has allocated amongst many asset classes, some available to individual investors and some that aren’t (except for those with high net worth). Yale does invest in cash and fixed income, equities, and real estate that are available to individual investors. It also invests in private equity, venture capital, etc. that may not be available to individual investors.

    California Pension Fund’s Asset Allocation

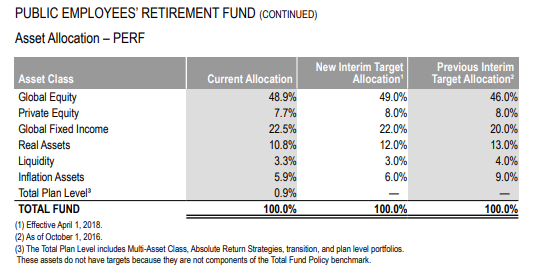
    Let us look at another institution that manages many people’s money – Calpers. Calpers is California’s pension fund and manages the pension funds of its 1.9 million members. They are a leading institution when it comes to investment portfolio management. Let us take a look at Calpers portfolio below.

    PUBLIC EMPLOYEES' RETIREMENT FUND (CONTINUED) 
Asset Allocation - PERF 
Asset Class 
Global Equity 
Private Equity 
Global Fixed Income 
Real Assets 
Liquidity 
Total Plan Level' 
TOTAL FUND 
1.2018 
Current Allocation 
489% 
225% 
108% 
100.0% 
New Interim Target 
Allocation' 
12.0% 
100.0% 
Previous Interim 
Target Allocation• 
46 
80% 
20 
130% 
9.0% 
100.0% 
(3) Tots 
Tt— wts do ttE TctS
    Source: Calper’s Investment Report

    Essentially, Calpers has major allocation to cash equivalents (liquidity, inflation assets), fixed income, real estate and equities.

    Personal Asset Allocation

    Looking at Yale and Calpers has given us an idea of how a couple of leading institutions are allocating between assets. We can draw some lessons for our personal portfolio from them though some asset classes may be out of reach for many individual investors.

    Thinking through risk tolerance and portfolio asset allocation is a key pillar of investing. For a majority of us, the investment universe may just consist of cash and fixed income, equities, and real estate. The exact percentage allocation for your portfolio would be based on your risk tolerance and your goals. The traditional calculators and thinking behind asset allocation is undergoing a big change.

    • Traditional Assets
      • Cash
      • Bonds
      • Stocks – Domestic and Foreign
    • Alternative Assets
      • Real Estate – REITs, crowdfunding, direct ownership, or private placements
      • Private Equity
      • Venture Capital
      • Commodities
    • Your Business

    If you need more ideas on the % allocation, check out articles that address the various asset classes described above. We highly recommend you do this exercise on a regular basis. Here’s some advice from US SEC for investors.

    If you understand your time horizon and risk tolerance – and have some investing experience – you may feel comfortable creating your own asset allocation model. “How to” books on investing often discuss general “rules of thumb,” and various online resources can help you with your decision.

    For example, although the SEC cannot endorse any particular formula or methodology, the Iowa Public Employees Retirement System (www.ipers.org) offers an online asset allocation calculator. In the end, you’ll be making a very personal choice. There is no single asset allocation model that is right for every financial goal. You’ll need to use the one that is right for you.

    Some financial experts believe that determining your asset allocation is the most important decision that you’ll make with respect to your investments – that it’s even more important than the individual investments you buy….

    Source: US SEC’s Investor Beginner’s Guide

    Investor Takeaways

    Coming up with a personal asset allocation model is the biggest decision an investor can make. An investor should devote significant time and attention to this effort and get trusted financial advice as needed. After taking a risk tolerance assessment and understanding your risk profile, the next step is to understand the major asset classes and allocate them amongst your portfolio.

    We’ve seen some examples of leading institutional investors and how they invest in both traditional and alternative asset classes. Leverage calculators and modern thinking around asset allocation. Write down your asset allocation model and visit it on a periodic basis. This exercise is in itself worth your time in Gold.