Tag: real estate investments

  • What is a Prime Brokerage and Who Uses Their Services?

    A prime brokerage is a bundled group of services offered by investment banks and other financial institutions. Investment banks may offer these services to hedge funds and other large investment clients that have a need to be able to borrow securities (or cash), in order to engage in “netting” to achieve “absolute returns”.

    What is Netting?

    Netting refers to offsetting the value of multiple positions, or payments, due to be exchanged between two or more parties. Typically, it’s used to determine which party is owed compensation in a multiparty contract.  Additionally, utilized as a method of reducing risks in financial contracts by combining or aggregating multiple financial obligations to arrive at a net obligation amount. Netting reduces settlement, credit, and other financial risks between two or more parties.

    What is an Absolute Return?

    An absolute return indicates the return an asset receives over a specific period. This measure looks at the appreciation/depreciation that an asset – such as a stock or mutual fund – has achieved over time. Absolute returns differ from relative returns in that there’s no benchmark comparison. The absolute return is concerned with the return of that specific asset over a period of time. An easier way to think of an absolute return is by its other reference, total return. Therefore, the gain or loss of an asset or portfolio is measured independent of any other standard. Absolute returns may be positive or negative and they may also bear no correlation to other market activities.

    Who Typically Utilizes Prime Brokerage Services and Who Provides Them?

    Hedge funds would amongst the first category of prime brokerage clients. Legally, clients may not access prime brokerage services for less than $500,000 in equity, even though it’s typical for clients to have over $50M in equity. High net worth private investors are another popular category of prime brokerage clients.

    On the other hand, prime brokerage services are generally offered by large investment banks. These institutions benefit from economies of scale to bundle multiple financial service offerings with more efficiency, at a cheaper cost. Some of the most notable firms who offer prime brokerage services include Goldman Sachs, BAML, JPMC, Citigroup, and BNY Mellon. Services bundled include largely “back office” tasks like asset custody, financial reporting, cash/securities lending, investor introductions, and risk consulting.

    Historically, Goldman Sachs has been known as the most reputable prime brokerage. However, their prime brokerage agreements are such that smaller hedge funds would have difficulty meeting their expected capital requirements. More recently, Pershing – an elite BNY Mellon subsidiary – has become the backbone of the prime brokerage street business. Combining the custodial services BNY Mellon is renowned for, with Pershing’s uniquely skilled investments and alternatives specialists, gives the duo a unique marketing position within the prime brokerage business. Pershing’s “prime services” are highlighted by risk management consulting. Additional offerings include securities lending, financing solutions, trade execution, technology, liquid alternative investments, and more. Within the alternative investment niche, which is extremely frequently accessed by hedge funds, Pershing has built an impeccable reputation.

  • Financial Markets Are Suffering, But What About Real Estate?

    As recent signals that the Fed’s “soft landing” recession isn’t going to come to fruition, financial markets responded accordingly. In addition to covering financial markets impact, we’re going to look into real estate. The DOW Jones and S&P 500 both dropped steadily Friday 10/7. The S&P has been on such a steady decline, the last 12 months of gains have officially completely canceled out. While some have speculated that we’re at a “bottoming out” in the equities market, which is supported by historic S&P 500 trends, market participants don’t seem to fully buy in. In fact, quantitatively the Top 5 stocks by market cap in the S&P 500 (Apple, Microsoft, Amazon, Tesla, and Alphabet Inc/Google, i.e., “Big Tech”) have been overpriced for years, compared to S&P 500 P/E [Price-to-Earnings] averages.

    Either way, turmoil is very likely to continue for capital markets and equities investors. Even if the net result is positive, there will be a lot of sleepless nights in the process. Let’s shift gears and take a look at a completely different, but critical (remember 2008) market: real estate.

    The Real Estate Market was Effectively COVID-proof; is it Recession-proof?

    This is the ultimate question for investors will look at real estate – both passive and active investments – in the longer-term. Foreign investors are already starting to see massive benefits to American real estate investments. That’s certainly one of the primary catalysts for steadily high real estate prices, while other assets are devalued. While we’re going to address the current and future state of the real estate market, the heading was rhetorical. Never forget 2008. That’s going to be a critical lesson investors takeaway from this coming recession, as well. 

    Real estate and related assets are certainly not recession, or even depression proof. It’s always good to be reminded of this fact: real estate is the world’s largest asset class. That means the most money (in all forms of currency, worldwide) is being spent in this market, as compared to any other segment in global finance. With real estate-related securities, we now know we must pay extra close attention to the value of the underlying assets. That goes back to a key differentiator when you’re discussing real estate in the context of an investment strategy. People and families will always need shelter. The landscape may have been altered due to COVID-19, but corporations still need office buildings.

    Physical Real Estate Will Always Have Some Value

    The critical point is real estate will continue to have some value, regardless of what happens in financial markets. Moving away from the combination of greed – both on the part of homeowners and lenders – that led up to the 2008 financial crisis, real estate is still something society will always need. Remember how truly heartbreaking some of the stories of families losing their homes during that 2008 recession was? When tangible assets that we get daily utility from as in the equation, it’s an entirely different scenario from an illiquid financial asset. The types of investors are different, their goals are different, their interests vary, etc. This is all to say that while there’s no doubt there’s a level of positive correlation between financial markets and real estate prices, by no means is it absolute. The dynamics are far too dissimilar.

    However, not being recession-proof is actually one of the common denominators that always holds true for the pair. 

    The Pandemic Housing Boom

    As we’ve recently shared, experts started questioning how long this “seller’s market” we’ve seen explode since COVID-19 will last. Since then, there have been major developments. First and foremost, from the Fed. In late September 2022, the Fed announced they are going to “reset” the real estate market through a ‘difficult’ correction. In June 2022, Fed Chair Jerome Powell said he sees spiking mortgages rates fizzling out the Pandemic Housing Boom as a “good thing”. During what’s referred to as the Pandemic Housing Boom, housing prices soared in growth by 42%. We’ll now certainly see some of those gains erased.

    With increased rates, we should expect to see a diminished potential buyer pool. In April 2022, prices peaked at 21% – according to Zillow’s home value index – however by this fall they fell to just 14%. According to Zillow senior economist Jeff Tucker, “it’s too soon to tell” how big of an impact the reset will have on home prices. In July 2022, the S&P Case-Shiller index, which measures house prices in 20 US cities, recorded its first monthly decline in a decade, dropping by 0.44%. Mortgage rates (30-year, fixed rate) are currently sitting at roughly 6.7%, according to guarantor Freddie Mae. Just a year ago however, the same 30-year, fixed rate mortgage was 2.99%.

    The Impact of the Current Correction in Housing Market Prices

    “The market is shifting, but a correction was needed”, said real estate agent Junior Torres. “It was not a sane market, what we were having in the pandemic”. This is causing sellers, who were driving the early 2020s pandemic market, to face a new reality. Fewer properties are receiving fewer offers. Sellers are going to continue getting more and more ‘desperate’ the longer the correction lasts. In other words, until we’ve reached a point where supply and demand is back at an equilibrium price, median selling prices will continue to decrease.

    Additionally, a correction in the housing market typically incentivizes homeowners to ‘stay put’. Investors and home flippers might feel pressure to sell quickly, however homeowners will simply keep their house. If we do reach that point sometime in 2023 – but more likely 2024 – they will then reassess their situation. However, when the Fed is verbally communicating that rates aren’t down – the opposite – homeowners have frankly no incentive to sell. According to the latest numbers from Zillow, the median stay in a US home is 12 years.

    Concisely, housing market prices are going to continue decreasing while rates remain at this level. From Fed statements, this is expected to continue through 2023. This should result in housing market prices continuing on the same trajectory. Committed sellers and investors will feel pressure to act quicker. Those not ‘forced’ to sell for unexpected reasons (new job, for example) will very likely remain in their homes. This will obviously decrease supply, but again primarily due to the current and expected mortgage rates in the short-term, we should expect to see below average demand.

  • What’s Next for Cryptocurrencies and Digital Assets, Post-2020s Recession

    The macroeconomic outlook for the cryptocurrency/digital asset market is definitely not looking good, at this time. There are a multitude of reasons. I think this is largely because Cryptocurrencies are considered “trendy” in financial services, however I’ve recently been asked for my take on specific Crypto’s (Bitcoin primarily) and what I’ve come to refer to as “Complex Crypto’s” (ETFs, other Exchange Traded Crypto Securities, Crypto IRA’s, etc.). Of course, at the center of this conversation is Cryptocurrency mining and trading. As most who follow this market even casually know, the two are intimately related.

    Standpoint on Cryptocurrency and Digital Assets Throughout the Recession

    Disclaimer: Pro-crypto enthusiasts will not be happy. This is how I’d put it, favorably. I see the cryptocurrency market, coming out of the recession – assuming it does – with entirely new technologies, marketing strategies, market dynamics, etc. To elaborate, let’s take what we can all agree to be true about the cryptocurrency fan base today, largely speaking. They’re a) not long-term strategists, b) very weak (or completely incoherent) when it comes to basic knowledge of financial markets and even more complex financial instruments, and c) the composition of cryptocurrency investors is not one you’d generally – or ever – consider “cash rich” compared to other investors (both individual and institutional).

    We’re looking at a market with the majority of participants being short-term, stubborn and perhaps unqualified thinkers, with little to no savings to boot. Market dynamics aside, Bitcoin has been religiously dropping for quite a while now. If conceptually it doesn’t make sense and the numbers aren’t there, investors are in deep trouble.

    Fast forward a few months. The Fed continues their ongoing strategy of “deflating the inflation” with historically “aggressive” rate hikes. The participants in the market described above would generally be considered high in terms of price elasticity. Meaning, their sensitivity to pricing changes is above average. In prices rise, they are more likely to sell quicker than someone who is more price inelastic, perhaps because they have a larger savings (as an example). On average, the same cryptocurrency enthusiasts who decided to invest in a Crypto ITF are the ones who will be forced to sell off their digital asset portfolio the quickest.

    When the average cryptocurrency enthusiast starts to get more and more burdened by everyday essentials, their digital wallet’s intrinsic value will diminish rapidly. Are you willing to struggle to pay rent to hold onto Bitcoin at the price you bought it? If you’re already a short-term thinker, the answer is more or less common sense. No. Nor are you willing to sell your house to maintain a bullish position on Bitcoin (if you’ll be in one of the unfortunate groups that lose their job in the recession).

    The Cryptocurrency Enthusiasts with Never-ending Dedication

    Cryptocurrency enthusiasts will undoubtably disagree with the short-term thinking narrative, but it’s respectfully backwards. There’s no other asset in financial markets you’ve analyzed as a better bet for the long-term. Really? Not the S&P 500 Index? US Treasuries that have never defaulted? If you’re looking for enhanced potential for extravagant short-term returns, cryptocurrency is an area for you. But that’s a complete contradiction to the long-term value proposition. There is none.

    Their last standing argument: Blockchain Technology. This is debated in part, but the general consensus among the Crypto community appears to be along the lines of, “Blockchain technology is considered a commodity and regulated by the CFTC that we simply cannot live without as a society. Therefore, Bitcoin will survive and prosper through any recession, since we have propriety technology that will revolutionize the world” [I’m paraphrasing]. This technology is by no means universally accepted in traditional financial markets. Bill Murray’s Ethereum wallet was recently infamously hacked. This will no doubt bolster the SEC’s position against institutionalizing digital assets.

    It’s relied on even less so by traditional financial investors. Let’s not forget, the SEC is still unwilling to budge on a Bitcoin spot ETF with the number one concern being lack of technological innovation to eliminate jacking and market manipulation. If the SEC says it’s too dangerous, where do you think institutional investors will fall with the current macroeconomic trajectory? Why is Bill Murray’s Ethereum wallet suddenly the focus of all the daily financial newsletters?

    Near and Long-Term Cryptocurrency and Digital Assets Outlook

    In the near term (3-4 months), look for prices to continue dropping steadily. This goes across the board for all digital assets. In the long term (1.5-2+ years), that becomes a very complicated question when you dig into potential hypotheticals. Digital assets and cryptocurrencies are almost completely unregulated. There are no remotely serious regulatory requirements or disclosures of any information about holdings reports, portfolio allocation, investor reports, or any other typically standard financial accounting. That was part of the initial pitch: anonymity.

    Now, when purely digital asset portfolio managers like Grayscale want to get through to institutional investors, they start to create SEC approved Bitcoin Trusts, strategically push for Bitcoin spot ETFs, make it publicly known they own roughly 4% of all of Bitcoin, etc. That goes back to an original point. Bitcoin and cryptocurrencies may not get completely cratered like the dinosaurs did, but will we have thousands – or tens of thousands – of different cryptocurrencies, trading on infinite different platforms, with an unlimited amount of different marketed benefits? I don’t see it.

    Are Cryptocurrencies and Digital Assets Going to Crash from the Recession?

    To the more interesting question, can digital assets become the modern-day dinosaurs? It’s vaguely possible, but unlikely. This is where global politics, luck, and irrational/unconventional investor behavior tend to make the largest impacts. Let’s say Bitcoin drops below $5,000 and Grayscale, owning roughly 4%, assesses a further drop to $3,000 by next month. What does Grayscale do? Every financial product they sell is a digital asset and they’ve marketed Bitcoin as the obvious face. They get absolutely no protections from bankruptcy and neither do their investors. Yet, with the amount of Bitcoin they own, could they theoretically have backdoor discussions that would lead to the price of Bitcoin artificially being propped up? It’s a definite theoretical possibility.

    Again, we don’t know who Grayscale would be in the room and how much bargaining power they’d have. To the cryptocurrency enthusiasts who think it’s “cool” to invest in cryptocurrencies specifically because executives at traditional investment institutions are known for appeasing shareholders (in other words, doing their jobs) and “throwing investors under the bus”, well what do you think will happen to you? Will the CEO responsible for making those decisions that has the potential to change investors lives do the “ethical” thing because they don’t have shareholders to protect? I think the fair and impartial response is that remains to be seen. That’s the truth.

    Let’s face it: cryptocurrencies and digital assets are in for the fight for their existence. This is newfound territory for this comparatively new market. It will absolutely shed so much more light than we have today about investors true perspectives and feelings on digital assets. At the end of the day, in a world where quantitative data leads investment decisions, rather than personal belief and alleged loyalty, we’ll have to see what executives and cryptocurrency holders alike do on a broad scale.

    The Bottom Line and What to Do

    The “correct” decision – meaning the decision statistically likely to have the most favorable outcome – would be to reinvest your holdings elsewhere. The risk is way too big, while the reward is way too small or nonexistent. Of the at-risk assets on the chopping block, digital assets are first in line. There is no remotely likely scenario where cryptocurrency supporters get to say “I told you so” anytime soon.

    In reality, what you do is listen to the experts, at least in this case. No one’s saying you need to get your IRA, or any other investment vehicle out for that matter, but you can’t think of a more prudent investment given the economic climate you’re being explained? What about real estate? You have the benefit of a physical asset, upside to earn capital gains if market prices increase, and at the simplest level, housing is essential. Individuals will never not need housing. If the recession impact results in a catastrophic scenario, you have an asset with no real danger of going to zero.

    If you’re going to hunker down and stay invested in digital assets until the end, you can still diversify and reduce your exposure. There are Bitcoin futures ETFs, like the VanEck Bitcoin Strategy ETF we discussed last time. There is the SEC-backed Bitcoin Trust; Grayscale’s GBTC. You can invest in hard currencies that would offset your exposure to digital currencies.

    There’s a plethora of options of the astute investor, but the question in my mind continues to be, why? Why go through an agonizing recession, where you’ll make difficult financial choices just to maintain your current cryptocurrency holdings? Again, if you’re so over-the-top for Blockchain technology, it will be available for purchase at a lower price in the future. But the near future? No chances from the present. Bitcoin will continue to systematically drop daily until there is major turnaround. There’s no telling what that will look like yet.

    The Warren Buffett Philosophy

    Consider this quote from Warren Buffett and how it applies to this debate. Buffett is universally known as the most intelligent and disciplined value-based investor of our generation.

    “People should only [make investments] in companies that exhibit solid fundamentals, strong earnings power, and the potential for continued growth.”

    -Warren Buffett, Unpublished

    Does the cryptocurrency market currently a) exhibit solid fundamentals, b) has strong earnings power, or c) has a solid potential for future growth? The answer to all three is no. That’s likely why Buffet has always remained a staunch opponent to digital assets. Buffet’s average holdings are somewhere from 10-34 years. It’s more than fair to say he views investing as a marathon, not a race.

    Concisely, as all other major financial news agree, the cryptocurrency market is at a crucial testing point, at bare minimum. We know crypto products aren’t going to gain market value during a recession, for sure. However, the extent of the damages digital assets will take compared to other “at-risk” assets remains to be seen. Time, Forbes, CNBC, and Reuters all predicted major cryptocurrency market tumbles during the recession just this week. Again, a lot of it will depend on luck and how things play out, but there are actions you can take as an investor to mitigate your exposure to the bullish side of the crypto/digital asset market during a recession.

    I’ll end with one final argument against cryptocurrencies and digital assets. Ironically, this goes against Warren Buffett’s main investing principle (at least in part). I believe he’s said that during a recession, his investment philosophy changes, but I was unable to find that quote.

    “Over the long term, the stock market news will be good. In the 20th century, the United States endured two world wars and other traumatic and expensive military conflicts; the Depression; a dozen or so recessions and financial panics; oil shocks; a fly epidemic; and the resignation of a disgraced president. Yet the Dow rose from 66 to 11,497.”

    -Warren Buffett, Unpublished

    The Secret Behind Buffett’s Legacy: Some Deals are Simply too Risky

    Whether you agree with the risks to digital assets now or not, Buffett is spot on as usual. He has more famous quotes regarding investing in the stock market for the long-term, which is what he starts with. Buffett has held AXP (American Express) since 1964, KO (Coca-Cola) since 1988, and Wells Fargo (WFC) since 1989. Buffett’s outlook on the stock market is almost exclusively dependent on his analysis of that specific business. He’ll look at the financials in extensive detail, but he’ll also study the business model. How the company generates profits, what kinds of costs they incur. He’s the third richest person in the world off investments alone. Warren Buffett – rather than major investment banks or cash lenders – is known to have plenty of available cash during a recession or financial panic.

    Why? He hedges anywhere he’s far too overexposed and to boot, he has a knack for taking good bets on massively successful companies. In the context of cryptocurrency and digital assets, are they going to withstand all those arduous times? WWI & WWII, Vietnam, the Great Depression, over a dozen recessions and financial panics, oil shocks, a fly epidemic, and a political catastrophe? That wasn’t just an ego-trip; Buffett lived through those eras and more so, he prospered through them. Very few, if any, can say the same. Buffett stays away from a certain level of risk, period. No matter what the potential or hypothetical reward is, Buffett doesn’t execute the deal unless it’s met his standards.

    In Conclusion…

    With the way Blockchain was initially pitched, then repurposed, and gained little traction since is worrisome to me. The bottom line is cryptocurrency and digital assets have nowhere to go but down during an impactful recession. What you should do, in full sincerity, depends almost exclusively on your investing goals and available capital. In common, everyday situations – for example purchasing an overpriced digital currency – you should still mitigate your losses.

    You don’t want to be taking a bigger loss because you were too stubborn to take a much smaller one initially. I believe we’ll wind up seeing a lot of cryptocurrency investors in that boat. At what point will they be willing to toss it in and accept this investment just didn’t work out? Will they get to that point? Time will tell. What’s certain is the magnitude the recession’s impact will have on the cryptocurrencies and digital assets markets.
  • What’s Next for Cryptocurrencies and Digital Assets, Post-2020s Recession

    The macroeconomic outlook for the cryptocurrency/digital asset market is definitely not looking good, at this time. There are a multitude of reasons. I think this is largely because Cryptocurrencies are considered “trendy” in financial services, however I’ve recently been asked for my take on specific Crypto’s (Bitcoin primarily) and what I’ve come to refer to as “Complex Crypto’s” (ETFs, other Exchange Traded Crypto Securities, Crypto IRA’s, etc.). Of course, at the center of this conversation is Cryptocurrency mining and trading. As most who follow this market even casually know, the two are intimately related.

    Standpoint on Cryptocurrency and Digital Assets Throughout the Recession

    Disclaimer: Pro-crypto enthusiasts will not be happy. This is how I’d put it, favorably. I see the cryptocurrency market, coming out of the recession – assuming it does – with entirely new technologies, marketing strategies, market dynamics, etc. To elaborate, let’s take what we can all agree to be true about the cryptocurrency fan base today, largely speaking. They’re a) not long-term strategists, b) very weak (or completely incoherent) when it comes to basic knowledge of financial markets and even more complex financial instruments, and c) the composition of cryptocurrency investors is not one you’d generally – or ever – consider “cash rich” compared to other investors (both individual and institutional).

    We’re looking at a market with the majority of participants being short-term, stubborn and perhaps unqualified thinkers, with little to no savings to boot. Market dynamics aside, Bitcoin has been religiously dropping for quite a while now. If conceptually it doesn’t make sense and the numbers aren’t there, investors are in deep trouble.

    Fast forward a few months. The Fed continues their ongoing strategy of “deflating the inflation” with historically “aggressive” rate hikes. The participants in the market described above would generally be considered high in terms of price elasticity. Meaning, their sensitivity to pricing changes is above average. In prices rise, they are more likely to sell quicker than someone who is more price inelastic, perhaps because they have a larger savings (as an example). On average, the same cryptocurrency enthusiasts who decided to invest in a Crypto ITF are the ones who will be forced to sell off their digital asset portfolio the quickest.

    When the average cryptocurrency enthusiast starts to get more and more burdened by everyday essentials, their digital wallet’s intrinsic value will diminish rapidly. Are you willing to struggle to pay rent to hold onto Bitcoin at the price you bought it? If you’re already a short-term thinker, the answer is more or less common sense. No. Nor are you willing to sell your house to maintain a bullish position on Bitcoin (if you’ll be in one of the unfortunate groups that lose their job in the recession).

    The Cryptocurrency Enthusiasts with Never-ending Dedication

    Cryptocurrency enthusiasts will undoubtably disagree with the short-term thinking narrative, but it’s respectfully backwards. There’s no other asset in financial markets you’ve analyzed as a better bet for the long-term. Really? Not the S&P 500 Index? US Treasuries that have never defaulted? If you’re looking for enhanced potential for extravagant short-term returns, cryptocurrency is an area for you. But that’s a complete contradiction to the long-term value proposition. There is none.

    Their last standing argument: Blockchain Technology. This is debated in part, but the general consensus among the Crypto community appears to be along the lines of, “Blockchain technology is considered a commodity and regulated by the CFTC that we simply cannot live without as a society. Therefore, Bitcoin will survive and prosper through any recession, since we have propriety technology that will revolutionize the world” [I’m paraphrasing]. This technology is by no means universally accepted in traditional financial markets. Bill Murray’s Ethereum wallet was recently infamously hacked. This will no doubt bolster the SEC’s position against institutionalizing digital assets.

    It’s relied on even less so by traditional financial investors. Let’s not forget, the SEC is still unwilling to budge on a Bitcoin spot ETF with the number one concern being lack of technological innovation to eliminate jacking and market manipulation. If the SEC says it’s too dangerous, where do you think institutional investors will fall with the current macroeconomic trajectory? Why is Bill Murray’s Ethereum wallet suddenly the focus of all the daily financial newsletters?

    Near and Long-Term Cryptocurrency and Digital Assets Outlook

    In the near term (3-4 months), look for prices to continue dropping steadily. This goes across the board for all digital assets. In the long term (1.5-2+ years), that becomes a very complicated question when you dig into potential hypotheticals. Digital assets and cryptocurrencies are almost completely unregulated. There are no remotely serious regulatory requirements or disclosures of any information about holdings reports, portfolio allocation, investor reports, or any other typically standard financial accounting. That was part of the initial pitch: anonymity.

    Now, when purely digital asset portfolio managers like Grayscale want to get through to institutional investors, they start to create SEC approved Bitcoin Trusts, strategically push for Bitcoin spot ETFs, make it publicly known they own roughly 4% of all of Bitcoin, etc. That goes back to an original point. Bitcoin and cryptocurrencies may not get completely cratered like the dinosaurs did, but will we have thousands – or tens of thousands – of different cryptocurrencies, trading on infinite different platforms, with an unlimited amount of different marketed benefits? I don’t see it.

    Are Cryptocurrencies and Digital Assets Going to Crash from the Recession?

    To the more interesting question, can digital assets become the modern-day dinosaurs? It’s vaguely possible, but unlikely. This is where global politics, luck, and irrational/unconventional investor behavior tend to make the largest impacts. Let’s say Bitcoin drops below $5,000 and Grayscale, owning roughly 4%, assesses a further drop to $3,000 by next month. What does Grayscale do? Every financial product they sell is a digital asset and they’ve marketed Bitcoin as the obvious face. They get absolutely no protections from bankruptcy and neither do their investors. Yet, with the amount of Bitcoin they own, could they theoretically have backdoor discussions that would lead to the price of Bitcoin artificially being propped up? It’s a definite theoretical possibility.

    Again, we don’t know who Grayscale would be in the room and how much bargaining power they’d have. To the cryptocurrency enthusiasts who think it’s “cool” to invest in cryptocurrencies specifically because executives at traditional investment institutions are known for appeasing shareholders (in other words, doing their jobs) and “throwing investors under the bus”, well what do you think will happen to you? Will the CEO responsible for making those decisions that has the potential to change investors lives do the “ethical” thing because they don’t have shareholders to protect? I think the fair and impartial response is that remains to be seen. That’s the truth.

    Let’s face it: cryptocurrencies and digital assets are in for the fight for their existence. This is newfound territory for this comparatively new market. It will absolutely shed so much more light than we have today about investors true perspectives and feelings on digital assets. At the end of the day, in a world where quantitative data leads investment decisions, rather than personal belief and alleged loyalty, we’ll have to see what executives and cryptocurrency holders alike do on a broad scale.

    The Bottom Line and What to Do

    The “correct” decision – meaning the decision statistically likely to have the most favorable outcome – would be to reinvest your holdings elsewhere. The risk is way too big, while the reward is way too small or nonexistent. Of the at-risk assets on the chopping block, digital assets are first in line. There is no remotely likely scenario where cryptocurrency supporters get to say “I told you so” anytime soon.

    In reality, what you do is listen to the experts, at least in this case. No one’s saying you need to get your IRA, or any other investment vehicle out for that matter, but you can’t think of a more prudent investment given the economic climate you’re being explained? What about real estate? You have the benefit of a physical asset, upside to earn capital gains if market prices increase, and at the simplest level, housing is essential. Individuals will never not need housing. If the recession impact results in a catastrophic scenario, you have an asset with no real danger of going to zero.

    If you’re going to hunker down and stay invested in digital assets until the end, you can still diversify and reduce your exposure. There are Bitcoin futures ETFs, like the VanEck Bitcoin Strategy ETF we discussed last time. There is the SEC-backed Bitcoin Trust; Grayscale’s GBTC. You can invest in hard currencies that would offset your exposure to digital currencies.

    There’s a plethora of options of the astute investor, but the question in my mind continues to be, why? Why go through an agonizing recession, where you’ll make difficult financial choices just to maintain your current cryptocurrency holdings? Again, if you’re so over-the-top for Blockchain technology, it will be available for purchase at a lower price in the future. But the near future? No chances from the present. Bitcoin will continue to systematically drop daily until there is major turnaround. There’s no telling what that will look like yet.

    The Warren Buffett Philosophy

    Consider this quote from Warren Buffett and how it applies to this debate. Buffett is universally known as the most intelligent and disciplined value-based investor of our generation.

    “People should only [make investments] in companies that exhibit solid fundamentals, strong earnings power, and the potential for continued growth.”

    -Warren Buffett, Unpublished

    Does the cryptocurrency market currently a) exhibit solid fundamentals, b) has strong earnings power, or c) has a solid potential for future growth? The answer to all three is no. That’s likely why Buffet has always remained a staunch opponent to digital assets. Buffet’s average holdings are somewhere from 10-34 years. It’s more than fair to say he views investing as a marathon, not a race.

    Concisely, as all other major financial news agree, the cryptocurrency market is at a crucial testing point, at bare minimum. We know crypto products aren’t going to gain market value during a recession, for sure. However, the extent of the damages digital assets will take compared to other “at-risk” assets remains to be seen. Time, Forbes, CNBC, and Reuters all predicted major cryptocurrency market tumbles during the recession just this week. Again, a lot of it will depend on luck and how things play out, but there are actions you can take as an investor to mitigate your exposure to the bullish side of the crypto/digital asset market during a recession.

    I’ll end with one final argument against cryptocurrencies and digital assets. Ironically, this goes against Warren Buffett’s main investing principle (at least in part). I believe he’s said that during a recession, his investment philosophy changes, but I was unable to find that quote.

    “Over the long term, the stock market news will be good. In the 20th century, the United States endured two world wars and other traumatic and expensive military conflicts; the Depression; a dozen or so recessions and financial panics; oil shocks; a fly epidemic; and the resignation of a disgraced president. Yet the Dow rose from 66 to 11,497.”

    -Warren Buffett, Unpublished

    The Secret Behind Buffett’s Legacy: Some Deals are Simply too Risky

    Whether you agree with the risks to digital assets now or not, Buffett is spot on as usual. He has more famous quotes regarding investing in the stock market for the long-term, which is what he starts with. Buffett has held AXP (American Express) since 1964, KO (Coca-Cola) since 1988, and Wells Fargo (WFC) since 1989. Buffett’s outlook on the stock market is almost exclusively dependent on his analysis of that specific business. He’ll look at the financials in extensive detail, but he’ll also study the business model. How the company generates profits, what kinds of costs they incur. He’s the third richest person in the world off investments alone. Warren Buffett – rather than major investment banks or cash lenders – is known to have plenty of available cash during a recession or financial panic.

    Why? He hedges anywhere he’s far too overexposed and to boot, he has a knack for taking good bets on massively successful companies. In the context of cryptocurrency and digital assets, are they going to withstand all those arduous times? WWI & WWII, Vietnam, the Great Depression, over a dozen recessions and financial panics, oil shocks, a fly epidemic, and a political catastrophe? That wasn’t just an ego-trip; Buffett lived through those eras and more so, he prospered through them. Very few, if any, can say the same. Buffett stays away from a certain level of risk, period. No matter what the potential or hypothetical reward is, Buffett doesn’t execute the deal unless it’s met his standards.

    In Conclusion…

    With the way Blockchain was initially pitched, then repurposed, and gained little traction since is worrisome to me. The bottom line is cryptocurrency and digital assets have nowhere to go but down during an impactful recession. What you should do, in full sincerity, depends almost exclusively on your investing goals and available capital. In common, everyday situations – for example purchasing an overpriced digital currency – you should still mitigate your losses.

    You don’t want to be taking a bigger loss because you were too stubborn to take a much smaller one initially. I believe we’ll wind up seeing a lot of cryptocurrency investors in that boat. At what point will they be willing to toss it in and accept this investment just didn’t work out? Will they get to that point? Time will tell. What’s certain is the magnitude the recession’s impact will have on the cryptocurrencies and digital assets markets.

  • How CRE Investors Can Still Create Value Amidst Rising Rates

    As we’ve covered in the last couple weeks, the current trend seems to be moving towards the buyer’s direction. Rising rates and other consequences from inflation are certainly a motivating factor. However, that does not mean there is no room for the average investor to make money. This is particularly true for CRE (Commercial Real Estate) investors. There’s always money to be made in the real estate market, that is, if you’re a seasoned and skilled buyer.

    “You can’t add value to bonds — and unless you own a VC firm or you’re Warren Buffett or Elon Musk, you really can’t create value by owning stocks. Other than owning a company or a franchise, only real estate allows investors to roll up their sleeves, either physically or metaphorically, and create value in an investment.”
    -John Chang, Marcus & Millichap
    Tweet

    Not only that, but in the CRE marketplace specifically, investors have so many options. From REITs, REIGs, non-traded REIT sponsors, mini-tender offers, all the way to even direct CRE property management. The latter is what Chang illuded to in his quote above. Having a “do it yourself” attitude in real estate can allow to you avoid hiring FTE’s. Thus, you’re much more likely to have room for a positive return. What will every intelligent macroeconomist suggest to businesses when monetary policy is geared towards inflationary times, or a potential recession? Minimize business costs (Wan, CloserIQ). That applies directly to CRE investors too. If you can minimize your business cost, by acting as your own property manager for example, you are undoubtably more likely to succeed irrespective of turbulent financial times.

    With an official from the Fed quoted as saying he sees the Fed raising rates through the end of 2023, investors should prepare for a tightening economy (Saphir & Dunsmuir, Reuters). Rising prices with relatively unchanged labor market conditions. If you invest in FX, that likely means the dollar will be disadvantaged. But in CRE, as in the whole real estate asset class, positive returns are always on the table. To reiterate, investors who are willing to cut costs will make out well in a recessionary economic period.

  • Is India’s UPI (Unified Payments Interface) Technology Worth Selling Overseas and to Western Countries?

    The Unified Payments Interface (UPI) was created by the National Payments Corporation of India (NPCI) for purposes of “enabling digital payments and settlement systems in India, is an initiative of RBI and IBA”. As announced in Bloomberg in June 2022, the NPCI is looking to take UPI to overseas markets. This implies that a) the technology has been tested thoroughly and successfully in Indian markets and b) there is currently no real competitor to UPI in overseas markets. At one point, NPCI CEO Ritesh Shukla compared it to a “home-grown alternative to SWIFT”. For those who aren’t familiar, SWIFT is a Belgium-based cross-border payments system operator.

    Has the Product [UPI] been Thoroughly Tested in Indian Markets?

    Based on our research, yes UPI has been tested both rigorously and successfully in Indian markets.

    “We have displaced cash in India to a large extent and are now looking to repeat the success in cross-border corridors. Overseas Indians can use our rails to remit money inwards straightway into their bank accounts, and for the markets where Indians travel frequently, we will build acceptance for our instruments.”
    – NPCI CEO, Ritesh Shukla
    Tweet

    Not only has the technology behind UPI been proven and tested, but the methodology has also succeeded. At least that’s the quantitative claim Shukla’s making. The World Bank data seems to support the analysis too. Indians overseas remitted $87 billion in 2021; the biggest inflow for any country that was tracked by the World Bank.

    Under the RBI’s “Liberalized Remittance Scheme”, all resident individuals (including minors) are allowed to freely remit up to USD $250,000 per year. This is from April-March, for any permissible current or capital account transaction, or a combination of both. Further, resident individuals can avail of the foreign exchange facility, for specific purposes within the limit of USD $250,000 only. The RBI’s “Scheme” was introduced on February 4, 2004, with a limit of USD $25,000 (BusinessDesk, Bloomberg). Since then, the LRS limit has been revised in stages consistent with prevailing macro and micro economic conditions. Notably, the “Scheme” is not available to corporates, partnership firms, HUF, Trusts etc.

    Are there Any Notable Comparisons to India’s UPI Abroad (not factoring in SWIFT)?

    Of the $87 million in remittances India received in 2021, the US was the biggest source (World Bank). According to the World Bank, US remittances to India accounted for over 20% of the $87 million in 2021.

    “Flows to India (the world’s largest recipient of remittances) are expected to reach $87 billion, a gain of 4.6 per cent with the severity of COVID-19 caseloads and deaths during the second quarter (well above the global average) playing a prominent role in drawing altruistic flows (including for the purchase of oxygen tanks) to the country”.
    – World Bank Spokesperson, World Bank Migration and Development Brief, 2022
    Tweet

    In terms of total global remittances, India is followed by China, Mexico, the Philippines, and Egypt (World Bank). In India, remittances are projected to grow 3% in 2022 to $89.6 billion. This is reflective of a drop in overall migrant stock, as a large proportion of returnees from Middle Eastern countries are still awaiting return (World Bank).

    Remittances in low-and-middle-income countries are projected to have grown a strong 7.3% to reach $589 billion in 2021 (World Bank). This “return to growth” is far more robust than earlier estimates. Following the same resilience of flows in 2020, when remittances declined by only 1.7% despite a severe global recession due to COVID-19, according to estimates from the World Bank’s Migration and Development Brief. Lastly, the brief in its entirety can be found here, from the World Bank’s website.

    Outside of evaluating the micro-differences to SWIFT, there are no current notable competitors to India’s UPI we could find. Without any doubt, no possible comparisons would come close in terms of size or scale.

  • Is there a Difference Between a ‘Buyer’s Market’ and a ‘Market that’s Rapidly Getting Less Advantageous Towards Seller’s’?

    The vast majority of latest prognostications point to a shift in the housing market, in favor of buyers over sellers. It’s about time. America’s housing market has been brutal on homebuyer’s, renters, and those looking to lease in prime locations for years now. There is a lot of qualitative and quantitative analysis to suggest that despite rising rates, buyers currently have the advantage.

    Realtor’s Weekly Housing Market: “The Four Big Bellwethers”

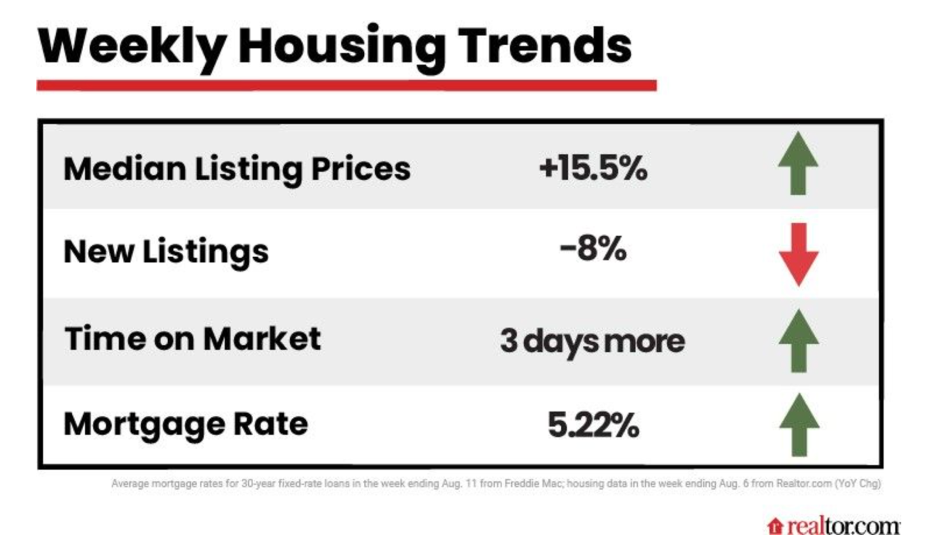
    Realtor has a weekly column called “How’s the Housing Market This Week?”. Realtor’s real estate economists are some of the most trusted in the industry. Weekly, Realtor delivers the most up-to-date statistics on what they coined “the four big bellwethers of the housing market”. These include home prices, # of new listings, total days on market, and of course, mortgage rates (Dutton, Realtor).

    “The housing market is resetting in a buyer-friendly direction,” notes Realtor Chief Economist Danielle Hale in her evaluation. We’d be remised if we didn’t note a “buyer-friendly direction” is certainly not the same as a true buyer’s market. While the same analysis notes the obvious, historic seller’s market that’s raged since COVID-19 began, it points out that the window for sellers is closing, rapidly. Below are the previously mentioned Realtor weekly housing trends, for week-end August 6th, 2022.

    -Realtor.com – Weekly Housing Trends, August 6th, 2022

    What jumps out to me are the top two statistics. A 15.5% median listing price increase, coupled with 8% fewer listing than the week before (Realtor.com). Hale has a unique and thought-provoking perspective on this phenomenon.

    Is There Surprisingly Good News in a 15.5% Increase in Median Listing Price?

    According to Hale, yes, this number is good news for prospective buyers. The last data from July 2022 shows a median nationwide listing price of $449,000. For the week ending August 6th, a 15.5% listing price increase means the new median was $518.595. While this marks the 34th straight week of double-digit price growth, Hale points out it’s also the “second consecutive week of deceleration” (Dutton, Realtor). The previous two weeks – at the end of July 2022 – median listing prices rose by 16.6% and 15.6%, respectively. This third ‘relatively temperate’ hike offers buyers hope home price growth will finally continue steadily dwindling.

    “The improvement has been substantial”, confirms Hale. She’s just as quick to add, “buyers in today’s market may still face meaningful affordability challenges as the typical home listing price remains near a record high”. But there’s little long-term evidence to suggest sticker price is a major deterrent for buyers (Dutton, Realtor). Hale reaffirms, “Persistent [homebuyers] may still continue to find success”. She goes on to add, “Second quarter data showed that homeownership rates increased from a year ago, both overall and for nearly every age and racial and ethnic group”.

    Given that homeownership rates have surged — amid rampant inflation, rising mortgage rates, and other deterrents — strongly signals that buyers who are willing to have some flexibility will ultimately win. Participants who are been willing to purchase somewhere they may not have considered pre-pandemic have largely become homebuyers. It’s a true testament to the lengths that homebuyers are willing to go today, provided sellers meet them halfway.

    Are Sellers Undermining the ‘Buyer Friendly’ Market?

    Anything positive for homebuyers is a negative for home sellers and of course, vice versa. Many sellers with properties on the market are panicking they ‘missed the mark’ by not closing a sale on their property during the COVID-19 real estate boom. For week-end July 30th, 2022, the number of new listings dropped by 8%, year-over-year (Dutton, Realtor).

    “New listings fell from a year ago for a fourth week. This is looking more and more like sellers may be wary of current market conditions, which have shifted substantially, even though they remain quite favorable to sellers who have owned for just about any length of time.”

    – Danielle Hale, Chief Economist, Realtor

    Hale appears to be hesitant to commit to buyer-friendly market conditions. However, she does definitively comment that conditions are becoming less and less favorable for sellers. The same message seems to be resonating across the board: if you’re a seller, the longer your property stays on the market, the worse-off your position will be.

    “While overall inventory [of new and old listings] grew by 28% over this same week last year, the active listings count still trails its 2020 and 2019 levels by more than 15% and 45%, respectively. More improvement in active inventory is likely needed to bring balance, but the recent trend may be at risk if homeowner attitudes toward selling now continue to deteriorate.”

    – Danielle Hale, Chief Economist, Realtor

    Once again, Hale seems to reemphasize the same underlying position. ‘We’re not in a pro-buyer’s market, we’re in a market that’s rapidly growing less favorable to sellers.’

    Are Rising Mortgage Rates to Blame for Homebuyers not Rushing to Close a Deal?

    The last question Realtor’s frequented market assessment addresses is why buyer’s aren’t rushing to close the deal. We are in a market that’s getting less and less favorable towards sellers, after all. What happens when we hit that market floor and conditions start to change against homebuyers. That has been the case – at a staggering rate – for well over two years now (Dutton, Realtor).

    In July 2022, listings lingered on the market a mere 34 days before getting snapped up. That’s nearly half the time it took two years earlier (Dutton, Realtor). Conversely, after having entered August 2022, it seems homebuyers are pumping the breaks and not feeling in such a rush. Hale’s prediction? Expect more of the same. She stated, “We expect more slowing ahead as the housing market reset”. The question remains, why?

    According to data provided by Freddie Mac, rising mortgage rates are a good place to start. For week-end August 11th, 2022, the average 30-year fixed mortgage rate increased to 5.22%. That’s considered a significantly steep spike from the previous week’s 4.99% (Mortgage Rates, Freddie Mac). Realtor predicts the future will hinge on how large corporations will view the potentially looming recession.

    “The big question for consumers is whether companies will over-react to the recession concerns and start trimming payrolls. A sharp pullback in hiring could have a direct impact on people’s ability to keep spending, especially with today’s high inflation.”

    – George Ratiu, Senior Economist, Realtor

    Realtor ultimately winds up agreeing. Prospective homebuyers should take full advantage of this buyer-friendly market while it lasts (Dutton, Realtor).