We’ve seen the reasons to invest in Commercial Real Estate (CRE) in a previous article. Though we believe that every investor should have access to Commercial Real Estate as an asset class, it may not be a good asset class to invest in for some investors due to certain characteristics of the real estate asset class. The purpose of this article is to go through the major reasons NOT to invest in real estate. This way an investor can evaluate for herself the pros and cons of investing in real estate and make an informed decision about real estate investing.
Long term horizon and illiquid
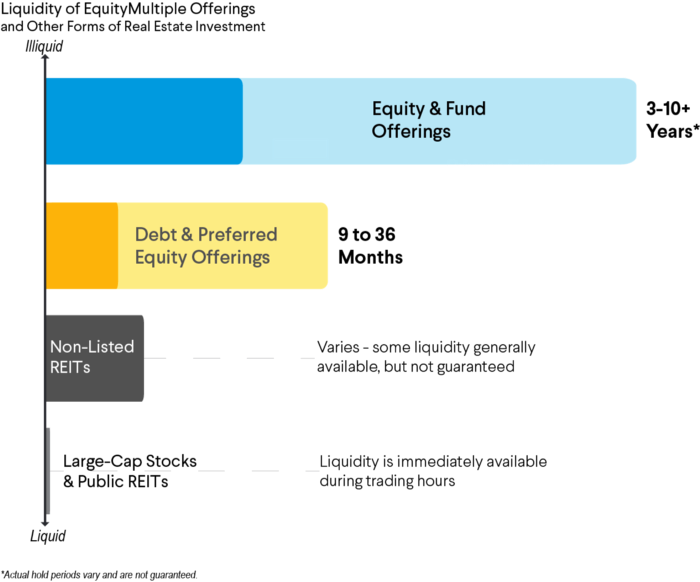
First and foremost, Real Estate is the least liquid of the major asset classes i.e. you may not be able to take out your money immediately when you need it. This applies to real estate private equity, syndicates, or investing directly in the assets (not through REITs). You could sell your stocks or bonds and cash it in a matter of hours, in real estate it will take months.
Real Estate also has evolved over the decades and the liquidity problem is solved by public REITs. REITs maybe an ideal vehicle for investors who want to invest in real estate, but want liquidity. REITs behave like securities and hence investors can buy and sell like any of their favorite stocks. REITs in turn have to buy and sell capital and illiquid assets which may take months.
The above chart from EquityMultiple real estate platform goes into the various offerings and the liquidity aspect. If an investor doesn’t have the appetite for the long-term and illiquid nature of the real estate, it is best to think of alternatives.
Capital intensive
Real Estate, by definition, is capital intensive. Though real estate can use leverage, an investor may still need to layout significant capital for many real estate types. Here are the top three CRE sales in NYC in 2020 to give an idea of the capital-intensive nature of CRE:
424 Fifth Avenue | $978 million Buyer: Amazon Seller: WeWork, Rhône Group Brokerage: N/A
410 Tenth Avenue | $952.5 million Buyer: 601W Companies Seller: SL Green Realty Brokerage: CBRE
330 Madison Avenue | $900 million Buyer: Munich RE Seller: Abu Dhabi Investment Authority Brokerage: CBRE
All of us will agree that raising $978 million is no small capital raise even for large institutions though there will be multiple sources of capital including debt. There are options for investors to invest in real estate without a large capital commitment (e.g. REITs), but we need to keep in mind that real estate projects and assets are very capital intensive directly or indirectly.
Risk tolerance and scars from global financial crisis
The first rule of investment is don’t lose money. And the second rule of investment is don’t forget the first rule. And that’s all the rules there are.
Warren Buffett
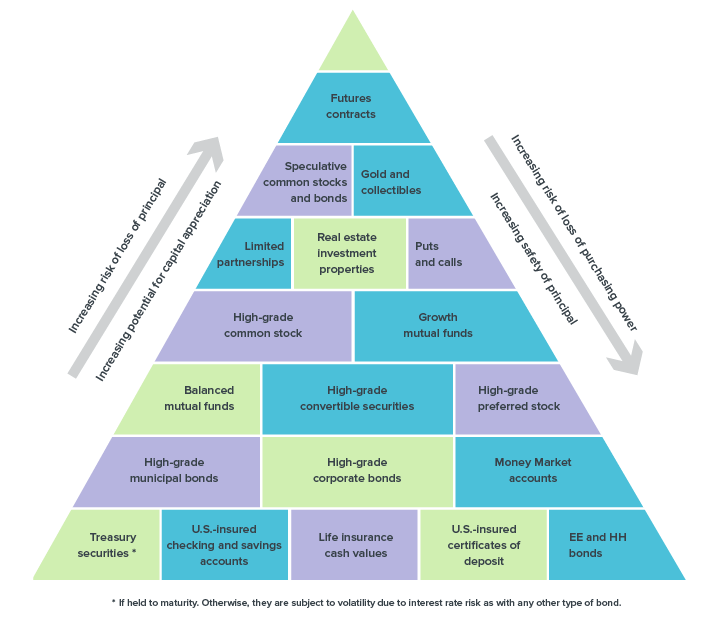
Is real estate a good investment for a risk-averse person? All asset classes have varying levels of risk, but let us address real estate in this article when compared to other asset classes. The chart below from Smart About Money illustrates the risk of loss of principal and increasing potential for capital appreciation in the chart below.
There can be a wide variety of risk level within the real estate property types and deals, but real estate as an asset class falls somewhere in the middle of the risk spectrum i.e. there is a probability that you could lose your entire money and even more. For e.g. you could lose your equity money and a lot more if you’ve provided a loan guarantee and the deal goes way south.
The residential Real Estate sector was a trigger for the Global Financial Crisis and it affected millions of people. People who remember it well may not have a good association with real estate and may have developed a risk-aversion. If you’re one such individual, there is a lot of preparation and groundwork that needs to be done even before you invest your $ in real estate.
Investor Takeaways
This article is the yin to the yang of ‘Why bother to invest in Commercial Real Estate?” We’ve looked into three major reasons NOT to invest in real estate. First, the illiquid nature of real estate for private placements and direct holding of assets. Second, the capital intensive nature of real estate outside of REITs. Third, is the relatively higher risk tolerance needed for investors compared to some other asset classes. It is best for an investor to consider their financial situation, understand the risks involved before proceeding (or not) with investing in real estate.
Investing in stocks or bonds has become so easy and widespread with advances in technology, with the likes of Robinhood. It also makes us wonder why invest in other asset classes like Commercial Real Estate (CRE) in the first place? In this article, we will attempt to answer this question. Along the way, we will also try to appreciate the risk profile and pros and cons of the three major asset classes – stocks, bonds, and real estate.
As we look into the three major asset classes – stocks, bonds, and real estate – we will review the basis for portfolio diversification to manage risk. We will also look into the performance of the major asset classes in the past 15 years to see how they have performed relatively. Finally, we’ll see the relative tax and other advantages of the various asset classes as that will affect the bottom line to the investors.
Portfolio diversification among asset classes
You must have heard the oft-repeated phrase “don’t put all your eggs in one basket”. Though cliched, it is the idea behind portfolio diversification. In financial terms, the intent of portfolio diversification is to reduce overall volatility and enhance risk-adjusted returns. As we have seen in previous FinYork articles, investing is all about having an investment strategy in accordance with one’s risk tolerance and executing on that strategy. Hence, portfolio diversification is a key tenet of investment strategy.
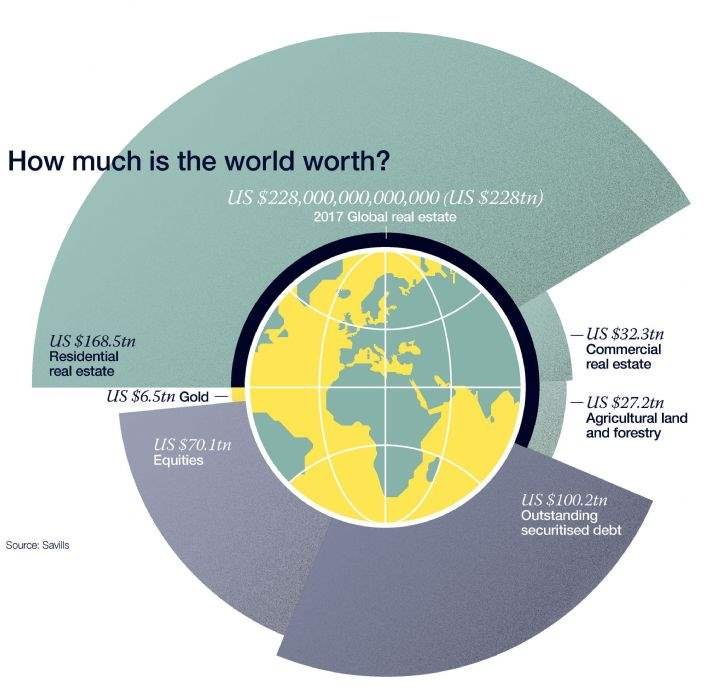
Here’s a chart from Savills on how much the world is worth divided into various asset classes. Real estate refers to residential real estate and CRE market size is $32 Trillion. It comes after Debt (Bonds) and Equities (Stocks) and only growing. Essentially, CRE is a major asset class globally.
Source: Savills
When added to a stock and bond portfolio, real estate can provide diversification benefits as real estate has historically shown a low correlation to stocks or bonds. There have been a couple of instances when all asset classes move together as in the Great Financial Crisis (GFC). Still, it is fair to say that the addition of real estate to a mixed-asset portfolio may lower overall volatility and enhance risk-adjusted returns.
Real estate is likely the first asset class that we got exposed to whether it is to live, study, play, or work. Even if everything falls apart, humans need people need built space to sleep, live, and work. Simply put, humans cannot live without real estate. This provides a powerful argument for the longevity of the asset class and why a portfolio must have exposure to an asset class that meets the basic needs of humans.
Long-term investment returns
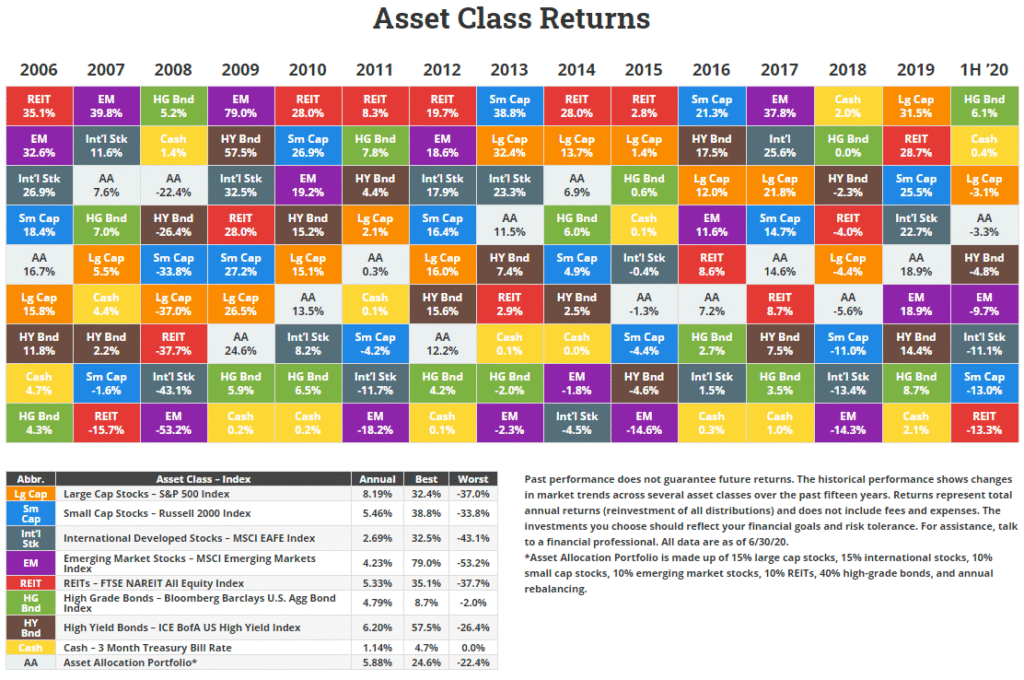
As of Feb 2021, stock markets are at all-time highs even though it has not been a good year for certain real estate property types like retail or hotels. Let us rewind a bit and look at asset class returns over a longer period. We found the following chart from Novel Investor that compares asset class performance since 2006. As it turns out, REITs (real estate securities) came out on top the most in 6 of the 15 years tracked. Including the 2007-2008 great financial crisis (GFC), which was triggered by real estate, REITs have performed well.
Real estate is in many ways different than a popular high-tech stock that may have doubled over a couple of years. For e.g. real estate offers investors relatively steady and recurring quarterly or monthly income that comes from operations. Many property types in real estate historically involved multi-year lease agreements (e.g. office leases) and hence the cash flow also tends to be relatively predictable and long-term in nature.
On the other end, an investor may be getting zero returns in her savings accounts. Relatively speaking, real estate offers higher yields for such investors. When the cash and equivalents produce close to zero interests. A lot of people (e.g. retirees) need steady and stable cash flows.
Inflation hedge and tax advantages
The fourth benefit real estate provides – inflation hedge and tax advantages. This is very powerful because it can make a big difference to how much money you can actually pocket. Compared to other asset classes, CRE provides a level of inflation protection. How does it provide protection? Real estate leases for the most part incorporate rent increases based on inflation. You may be familiar with your annual house or office rent increase based on inflation. In addition, property values also appreciate based on input costs. If the cost of input like construction material or amenities increase due to inflation, so does the property price and value. The above also doesn’t take into account inflation i.e. it assumes the dollar value is the same in 2006 as it is in 2020. We know that a dollar can buy less of gas or milk than before.
Investing directly in hard assets provides tax advantages in most countries. Tax policies favor real estate investing in many countries including the USA. For stocks and bonds, you’d have to pay taxes on interests, dividends, and capital gain. Depreciation and other treatment can lead to a paper loss when filing corporate or individual taxes. Hence, your tax burden may actually be very less. This deserves in-depth treatment and we will cover it in the future, but let us remember that many countries have historically provided very favorable treatment to the real estate sector.
Investor takeaways
We looked at the major asset classes and the role real estate can play in a portfolio to provide diversification. Real estate can help some investors meet their diversification strategy according to their risk tolerance. Looking at the long-term investment returns of various asset classes securities, Real Estate performance has actually been good in the long run. Scars of the Global Financial Crisis remain and COVID-19 will continue to be a challenge for many real estate property types.
We also compared the asset classes using inflation and a tax lens. Of all the asset classes, real estate provides the most inflation hedge and tax advantages due to real estate advantageous tax policies in many countries.
In summary, it may be worth investing in Real Estate as an asset class. We at FinYork believe all asset classes have a role to play in a portfolio, though we’ll be the first to admit we’re biased towards the real estate asset class. We also believe the real estate asset class is going to become more available and accessible to investors in the years to come. We want all investors to learn and benefit from this asset class. We plan to have a corresponding article on why NOT to invest in real estate. We encourage you to read both the articles and come to your own conclusions.
We looked at how understanding our risk tolerance and setting goals is the first stage of investing in a previous post. What do we do once we understand our risk tolerance and the goals are set? The next step is to have a basic idea of the investing universe and determine the areas to put investment dollars to work.
Many individual investors have a typical journey when it comes to investing. We would have started with savings accounts or CDs and then moved to dabbling in stocks and bonds. It is also very likely that many were forced to manage our retirement portfolios when we started working and got introduced to mutual funds and index funds. Along the way, some may have got exposed to real estate, commodities, or derivatives.
In essence, many individual investors do not have the opportunity to look at their portfolio holistically. After all, most of our time is consumed with our daily job and family commitments. The purpose of this article is to provide a holistic picture of investing. We will go through the various investment options available for investors to put their assets to work. We’ll get some ideas from top institutional investors who have performed well in the long run.
Myriad of Investing options
An investor has a myriad of investments to choose from these days. We may have heard about many of these investments, but we may have just invested in one or two of them. It can sometimes be confusing and sometimes daunting.
Unfortunately, investing is not taught for many in school or college and hence we don’t have any structured approach or framework for investing to follow. Let us first understand the myriad of investment options available. In the financial world, the various investment options are also called asset classes.
An asset class is a grouping of investments that exhibit similar characteristics and are subject to the same laws and regulations.
The major asset classes are depicted below. Historically, the popular asset classes have been stocks, bonds, cash-equivalent, commodities and real estate as depicted below. This misses some of the relatively newer investing options like private equity, hedge fund, derivatives and cryptocurrencies.
If you’re interested further in evaluating the various asset classes, nerdwallet has a detailed review of major asset classes.
How do you allocate the assets?
Understanding asset classes provide a lay of the land or big picture that will help you chose the asset classes that you can invest in. Understanding various characteristics of the asset classes helps you diversify your assets (the often used “don’t put all your eggs in one basket”).
The key is to understand the characteristics of an asset class, whether you invest in it or not. For e.g. when one thinks of transportation, one intuitively understands the difference between various modes of transportation – cars, trucks, trains, buses, planes, etc, and their characteristics. Assets classes are similar when it comes to characteristics between the various asset classes.
There are various traditional asset allocation calculators available to help allocate the assets. Many of them only consider traditional assets – stocks, bonds, and cash – only. We’ll see in the upcoming section, why investors should also consider diversifying beyond these traditional assets.
Yale University’s Asset Allocation
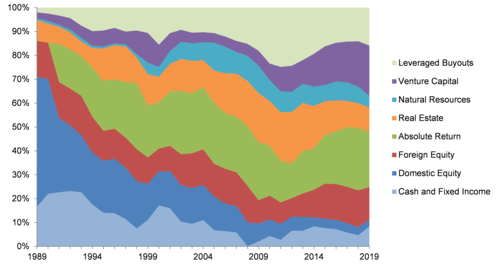
Let us look at industry leaders when it comes to investment performance. We can look at enterprises with a good record of investment returns. Yale University is one of them. Yale University is known for its portfolio performance as it has performed better than many peers and many college endowments compare themselves to Yale’s endowment performance. Let us take a look at Yale’s portfolio below.
As we can see, Yale has allocated amongst many asset classes, some available to individual investors and some that aren’t (except for those with high net worth). Yale does invest in cash and fixed income, equities, and real estate that are available to individual investors. It also invests in private equity, venture capital, etc. that may not be available to individual investors.
California Pension Fund’s Asset Allocation
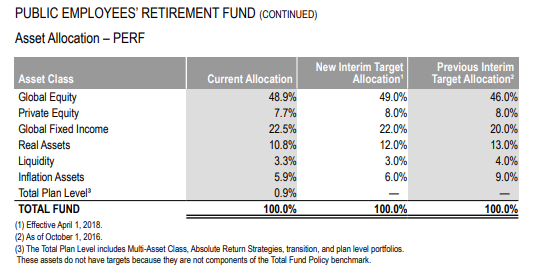
Let us look at another institution that manages many people’s money – Calpers. Calpers is California’s pension fund and manages the pension funds of its 1.9 million members. They are a leading institution when it comes to investment portfolio management. Let us take a look at Calpers portfolio below.
Essentially, Calpers has major allocation to cash equivalents (liquidity, inflation assets), fixed income, real estate and equities.
Personal Asset Allocation
Looking at Yale and Calpers has given us an idea of how a couple of leading institutions are allocating between assets. We can draw some lessons for our personal portfolio from them though some asset classes may be out of reach for many individual investors.
Thinking through risk tolerance and portfolio asset allocation is a key pillar of investing. For a majority of us, the investment universe may just consist of cash and fixed income, equities, and real estate. The exact percentage allocation for your portfolio would be based on your risk tolerance and your goals. The traditional calculators and thinking behind asset allocation is undergoing a big change.
Traditional Assets
Cash
Bonds
Stocks – Domestic and Foreign
Alternative Assets
Real Estate – REITs, crowdfunding, direct ownership, or private placements
Private Equity
Venture Capital
Commodities
Your Business
If you need more ideas on the % allocation, check out articles that address the various asset classes described above. We highly recommend you do this exercise on a regular basis. Here’s some advice from US SEC for investors.
If you understand your time horizon and risk tolerance – and have some investing experience – you may feel comfortable creating your own asset allocation model. “How to” books on investing often discuss general “rules of thumb,” and various online resources can help you with your decision.
For example, although the SEC cannot endorse any particular formula or methodology, the Iowa Public Employees Retirement System (www.ipers.org) offers an online asset allocation calculator. In the end, you’ll be making a very personal choice. There is no single asset allocation model that is right for every financial goal. You’ll need to use the one that is right for you.
Some financial experts believe that determining your asset allocation is the most important decision that you’ll make with respect to your investments – that it’s even more important than the individual investments you buy….
Coming up with a personal asset allocation model is the biggest decision an investor can make. An investor should devote significant time and attention to this effort and get trusted financial advice as needed. After taking a risk tolerance assessment and understanding your risk profile, the next step is to understand the major asset classes and allocate them amongst your portfolio.
We’ve seen some examples of leading institutional investors and how they invest in both traditional and alternative asset classes. Leverage calculators and modern thinking around asset allocation. Write down your asset allocation model and visit it on a periodic basis. This exercise is in itself worth your time in Gold.
There are beginner investors who can’t wait to invest or do a deal. They want to put capital to work right away and see the returns. On the other end of the spectrum, there are investors who hesitate to invest as they fear losing the money. And then there is a wide range of investors in between.
So, with this wide range of investors, where does one start? We’ll argue in this article that the first step to start investing is to understand risk, our tolerance to risk, and our goals. Understanding ourselves, our motives, and behavior is probably the hardest and most time consuming for many beginner and intermediate investors. In this post, we’ll share key steps with some resources for investors to assess their personal risk tolerance and create investing goals.
Where does an investor start?
Remember the first time you built a hobby? It probably happened over months or years. You tried a few things, liked that particular activity, and started doing more and more of it. Consciously, you may not have even taken the time to observe our actions. But, but you enjoyed it and continued it. Though many won’t consider investing as a hobby, the journey is similar. There is a lot of learning involved – technical and behavioral – and it is a very long journey to get better at investing. What is the first step in this journey? It comes down to understanding risk and our tolerance for risk. In the first place, what is risk?
In simple terms, risk is the possibility of something bad happening……
Risk involves uncertainty about the effects/implications of an activity with respect to something that humans value…such as health, well-being, wealth, property, or the environment…. often focusing on negative, undesirable consequences.
It is easy to get carried away in this day and age as most of us are exposed, sometimes overexposed, to finance and investing from general and financial media? We maybe seduced to get stock tips from our favorite financial media or guru and act on it. We need to be careful. Investing is not speculation and is for the long-term, and patience and learning are key. A good investor learns the basics and continues to learn every day!
Understanding and having an appreciation for risk is at the heart of finance and investing. Reward or returns is a by-product of risk. Many of us focus on rewards without appreciating the underlying risk. We’re always enticed by the higher return. But, we need to start with understanding our risk tolerance as explained below.
Evaluating our personal risk tolerance
We take risks on a daily basis though we may not see it as such. We make decisions based on risk all the time. Every time we cross a road we assess and take the risk of safely crossing the road. We select a college and course after weighing the risks and rewards. Will this college help me secure a job? We may not see it as such but some of the major life decisions are also risk-based decisions:
Given the importance of risk in finance and our daily lives, understanding our individual risk tolerance is of paramount importance. This will save months and years of worry and regrets.
Let us take an example. Say, you’ve $1000 to invest and are looking for ways to invest. You have done your research and narrowed it down to 3 options. The first option will give $10 after a year, but $1000 most likely not get affected. The second option will give you $100, but you could also lose $100 and end up with $900. i.e. Option 2 is riskier than Option 1. Some may prefer Option 1 and some may prefer Option 2. There is no universal single correct answer. It depends on the individual. It is important to understand which option you prefer i.e. what is your risk tolerance.
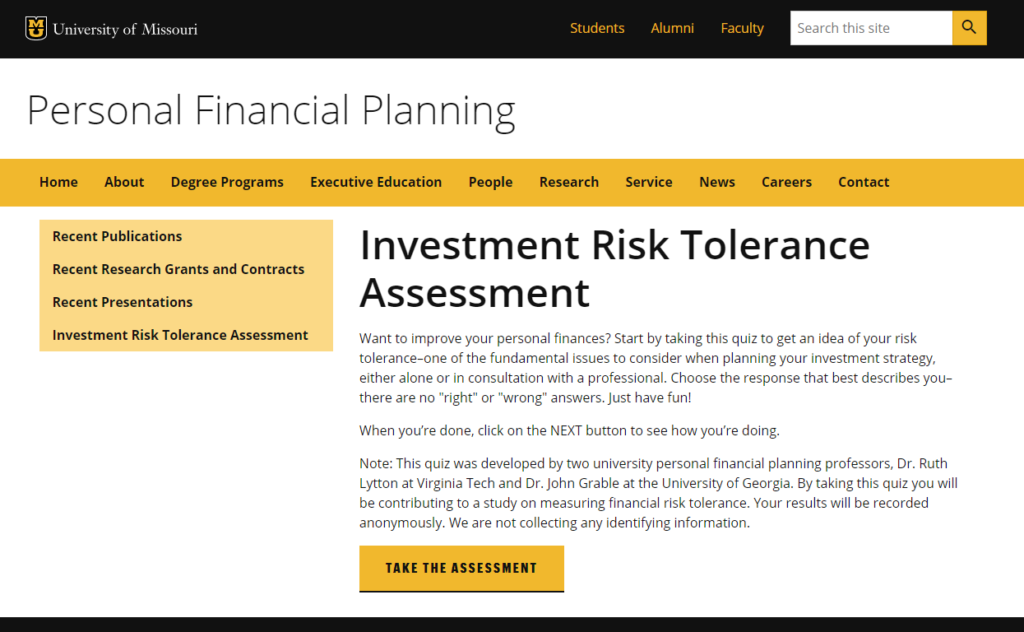
FinYork recommends taking an Investment Risk Tolerance Assessment, as the first step in assessing investment risk tolerance. The one below from the University of Missouri is popular. It is worth every minute of your time as this will set the stage for your investment planning.
Once you finish answering all the questions, you’ll be given an assessment of your risk tolerance. You can use this as the basis of your investments or discuss it with your financial advisor. You may have seen your brokerage’s investor profile questionnaire which is another tool for individual risk tolerance assessment. The whole purpose of this exercise is to evaluate your individual risk tolerance and even confront your fears upfront.
The survey gives a risk tolerance score at the end as shown below. The score will indicate whether you have a HIGH, MEDIUM or LOW risk tolerance. Your investment strategy has to follow your risk tolerance level. For e.g. someone with a LOW risk tolerance should go with a conservative investing strategy and invest in less risky asset classes. We’ll cover this in detail in upcoming articles.
We have so far looked at evaluating our risk profile and risk tolerance. Once we have an idea of our personal risk tolerance, what do we do next? The next step is to set up investing goals which will form the basis of our personal investing approach. If you already have investing goals and approach to meet those goals, that is great. If you don’t, please take the time to write them down. You need to make sure that you don’t stop at personal finance and budgeting but also think about your net worth and investing goals with a long-term view. You’ll find it beneficial to evaluate where you’re today in terms of personal finance (income/expenses) and net worth.
Investment Goals will differ by age and personal situation
Investment goals for people in their 20s are quite likely different from people in their 40s or 60s. Similarly, goals for people with families are going to be different for singles or couples. More importantly, they are going to be different based on your risk tolerance and personal financial situation. Please take note of your work situation, financial cash flows when coming up with goals. It is best for goals to follow the SMART method of setting goals. For further reading, please visit Corporate Finance Institute’s site on setting up SMART goals.
Write down Investing Goals
Before we get into the how of investing, particularly real estate investing, it is very important to assess your risk tolerance and have clear investing goals. Please take the time to write down the investing goals even if it takes a few hours a day. Above all, investing is a habit. You need to be committed and keep practicing it consistently to get better at it. Your investing goals may consist of the following or more:
Your goals and why you want to achieve those goals? For e.g. “My goal is to retire by 55 with X income and Y assets so that I can be financially free”
What are your guiding principles? For e.g. “I will invest in companies that also do some social good”
Your fears and how to overcome them? For e.g. “My fear is that I have little confidence in myself when it comes to money matters. I plan to overcome my fear by learning about investing by spending an hour every day.”
Investor Takeaways
In this article, we understand the basics of risk and risk tolerance and why understanding our risk tolerance is so important. Risk and our tolerance of risk is in itself not a good or bad thing. We just need to understand our risk tolerance as this will define our investing strategy. Having a true appreciation of our risk-taking will define our investing strategy. It will lead to the kind of investments – stocks, real estate, etc. we chose. We hope we’ve convinced you as an investor to evaluate your risk tolerance before making your first investment as it will save a lot of headaches.
Complete the above-referenced questionnaire, evaluate your risk tolerance, and keep it for your reference. In addition, take the time to think through and write your Investment Goals. We suggest doing this exercise on a regular basis (say, year-end every year) as that will inform us of our risk tolerance and come up with an appropriate investment strategy to manage risk. This will be the topic of upcoming articles.
One of the most common questions we get from beginner individual investors: should they invest in real estate rentals? Some want to take their first step in investing beyond stocks and bonds. Some see rentals as a source of passive income, in addition to their primary source of income. Some rent out their existing house when they buy a new house. Some are very much interested in real estate and want to take their first step. Reasons are varied and many.
Even though there is a lot of interest, real estate investing comes across as daunting for many. The reasons are again varied and many – high capital needs, time commitment, etc. The purpose of this article is to lay out three major ways to invest in real estate, including rentals. We will look into the characteristics of the different investment options and provide an approach to answer the question. The investor can then evaluate the pros and cons and decide whether rentals make sense.
Investing options
Real estate investors these days have a variety of options to start investing in real estate. Many of these were not easily available to a lot of individual investors even a few years back. The major options include investing in REITs, private placements, and directly investing in rentals. The good news is that there are so many ways to invest in real estate and get started that you don’t need to have a large amount of capital which used to be a big roadblock.
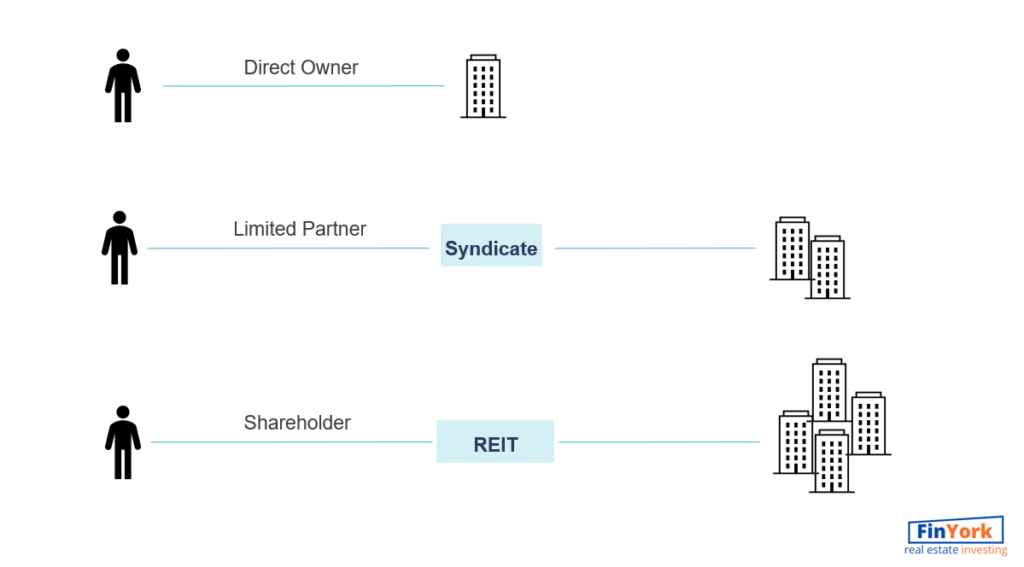
We’ll look at all three investment options through the lens of an investor, not necessarily as someone who wants to build a career in real estate. There are many ways for investors to get started with investing in real estate. Basically, it comes down to investing in the following three major ways illustrated and explained below.
Real Estate Investing Options
Direct Ownership of Rentals
Direct ownership of rentals needs no introduction. Buying a rental property has been an “old school” way to invest in real estate for decades and even centuries. Almost everyone can identify with buying a rental property and having full control over the property. People buy a rental home and are responsible for everything – buying the home and managing it themselves.
Syndication or Crowdfunding Platforms
Investing through syndication or crowdfunding platforms has become very popular over the past few years. Someone you know may have done it through crowdfunding platforms like Fundrise, RealCrowd or CrowdStreet. The terms maybe confusing to beginners, but think of syndicates as capital pooled from tens or hundreds of investors. The property is bought, managed and sold by the sponsor. In essence, sponsor is the active landlord and you’ll be the passive investor as a limited partner.
REITs and Stocks
Real Estate Investment Trusts (REITs) are real estate securities that trade like stocks. REITs are run by large institutions and they typically manage a property type (e.g. office or multifamily) across a large geographic region. Some of the popular REITs are Equity Residential for Multifamily or Prologis for Industrial property types. In addition to REITs, investors can also invest in housing stocks or real estate mutual funds.
Comparison of Various Options
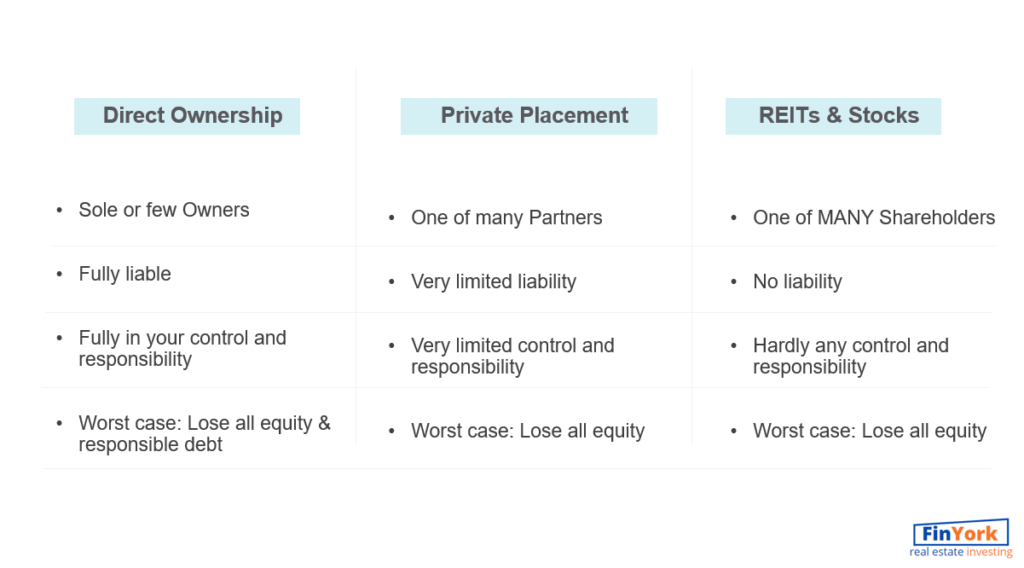
Now that we have an understanding of the major options to invest in real estate, let us look at the characteristics of each of them. We’ll look into the four key characteristics of the real estate investing options available – Ownership, Liability, Control, and Finances. The key characteristics are summarized in the illustration below:
Comparison of the Investing Options
Ownership, Control and Responsibility
When an investor invests in a rental property she will be the sole owner or one of the few owners. The investor is in full control. This is the storied mom and pop landlord that many of us are familiar with. The investor will be the sole responsible party as the landlord and she is responsible for all aspects of buying the property, getting a loan on the property, managing the property, and eventually selling it.
For private placements, the investor will most likely be a limited partner – one amongst tens or hundreds – in a given property. The investor will share the ownership with tens and possibly hundreds of other investors depending on the capital contributed. The investor will have limited or no responsibility, but she will have access to the sponsor and will get periodic distributions (usually quarterly or monthly) and reports.
From an ownership perspective, the investor will be one of the thousands of shareholders in REITs, funds, and housing stocks. The investor will hardly have any control over the property or management. The investor’s experience is the same as buying the shares of a public company in any other sector.
Liability and Financial Worst Case Scenario
When someone buys a rental property directly, they are fully liable as their name is on the title and all the documents. If a tenant sues the landlord because she hurt herself, the landlord will be fully liable and responsible. The investor also needs to get the debt (i.e. loan) and guarantee it. If things go south, the investor will lose her equity in the property and in addition, will need to pay off the debt as well. This is very important to understand.
For private placements, the investors will usually be a limited partner i.e. someone with very limited or no liability. The sponsor will be the general partner and will be responsible for all liability. The investor doesn’t even have to worry about debt financing, as the sponsor will be responsible for the loan. So, if things go terribly wrong, the worst thing that could happen is the investor will lose all their investment, but not more.
For REITs, the company management will be liable and the investor has NO liability at all. In the worst-case scenario, if the REIT does a poor job the investor loses all her money invested, but she won’t be responsible for the debt.
Investor Objective and Takeaways
We have looked into the major ways to invest in real estate and their characteristics. Now, let us come to the key question – Should you consider investing in rentals? Investors have different personal objectives, motivations, and situations. There is no one answer that fits all. We’ve seen the characteristics of the major investment options. Which one do you find appealing? The following questions will help you personalize the decision to your objectives and situation:
What are your (a) personal and (b) real estate investment objectives?
How much control/ownership do you want to keep or give to others?
How much liability and responsibility (including time commitment) are you willing to take?
Are the returns worth the risk?
Once you have understood the characteristics of the major investment options discussed earlier and answered the above questions, the choice will start crystallizing. Are you looking for passive income with minimal time commitment and headaches? Then, the options are REITs or private placements. Do you enjoy real estate or want to be more active in real estate? Then direct ownership in rentals may make more sense. After all, you know yourself the best.
Effective Commercial Real Estate (CRE) investing has two key requirements – capital and opportunities to invest the capital. Both are equally important and one without the other doesn’t work. And hence an investor has to constantly look for opportunities to invest if they have the capital. Where does one find real estate investing ideas or opportunities? How does an investor validate their real estate investment ideas and thesis? The purpose of this article is to answer these questions.
A Real Estate (RE) investor has to look at the right places to get RE investment ideas in today’s information overload age. Some good sources are market studies, reports, and research done by academia, government agencies, and consulting companies. We’ll look at one great source – Real Estate Market Cycle reports – to answer our questions around RE investment ideas. We will see if we can validate investment ideas at the property or portfolio level according to the investor type and their risk tolerance. We’ll summarize investor takeaways based on the three major investor types – conservative, moderate, and aggressive.
Real Estate Market Cycle Introduction
You may have heard about economic/business cycles or credit cycles. The Real Estate Market Cycle can be viewed as the business cycle for the real estate industry. It is based on the fundamental belief that real estate goes through sequential cycles. A given cycle also goes through multiple phases. Real Estate Market Cycles are long, like credit cycles, and can last 10-20 years and so the investor needs to think and plan long-term.
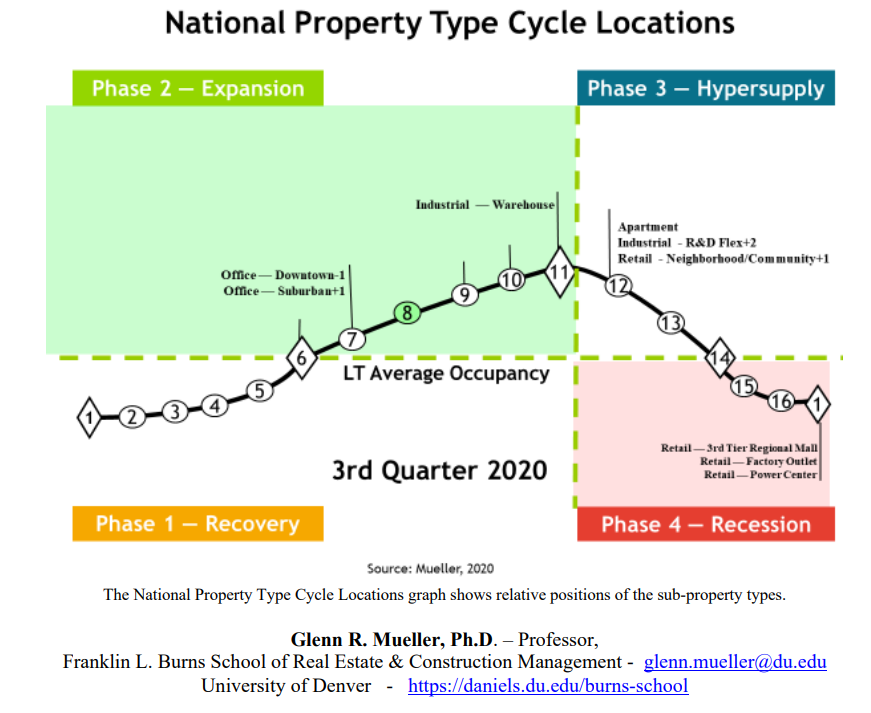
One of the popular US real estate cycle report comes from Professor Mueller at the University of Denver. Professor Mueller publishes a quarterly Physical Market Cycle Analysis of four Property Types in 54 Metropolitan Statistical Areas (MSAs). The Real Estate Market Cycles are based on the long-term occupancy average as it is a key factor for rental growth rates, income, and thus property values. The market cycle phases or quadrants within the real estate cycle are illustrated in the graph below:
CRE property types have different risk/reward profiles. Accordingly, Real Estate Market Cycles covers the following property types and sub-types:
The chart below shows the National Property Type Cycle Locations in Q3 2020. In summary, Office and Industrial warehouses are in the expansion phase. Apartments, Industrial R&D and Neighborhood Retail are in the Hypersupply phase. Retail, except for neighborhood stores – is in the recession phase.
How to leverage the Market Cycle and invest?
How does an investor leverage the market cycle for her investment decisions – Buy, Hold, or Sell? Before we analyze this further, it is important to remind ourselves that COVID-19 has caused major dislocation in the CRE industry. CRE industry is in a state of flux and it will cloud the picture for investors in 2021-2023. The Real Estate market cycle can be one data point for investors, but not the sole data point or factor. Keeping this in mind, an investor has a couple of ways to leverage the real estate market cycle:
Portfolio Strategy
Portfolio strategy is the overall asset allocation amongst the major asset classes – stocks, bonds, and real estate. The Real Estate Market Cycle gives an investor the opportunity to validate or make updates to her long-term portfolio strategy. Should an investor increase or reduce her exposure to real estate? Compared to stocks and bonds what should the real estate allocation be in the years going forward? Real estate investing, in particular, takes a lot of portfolio planning and long-term thinking as the execution can run into quarters.
New and Existing Investments
When it comes to investing in new real estate deals, an investor can look at the Real Estate Market Cycle for the given property type and location to determine the potential risk and upside. For e.g. if the investor buys during the hyper supply phase, the returns are going to be lower than when buying during the expansion phase. On the flip side, the investor can expect more upside when she buys during recovery/expansion and sells during the hyper supply phase. The investor can follow a similar approach to see if an asset should be sold or held.
Our opinion for all investor types
As we saw in the last section, an investor can prepare herself and plan for her portfolio based on the Real Estate Market Cycle. It is important to keep in mind that the progression along the market curve is not always smooth and sequential. It is possible for a property type and location to fall back on the curve.
An investor can look at the property type and location combination and see where they are in the market cycle. In the following sections, we review the Real Estate Market Cycle by property type and give our opinion for various investor types.
Multifamily
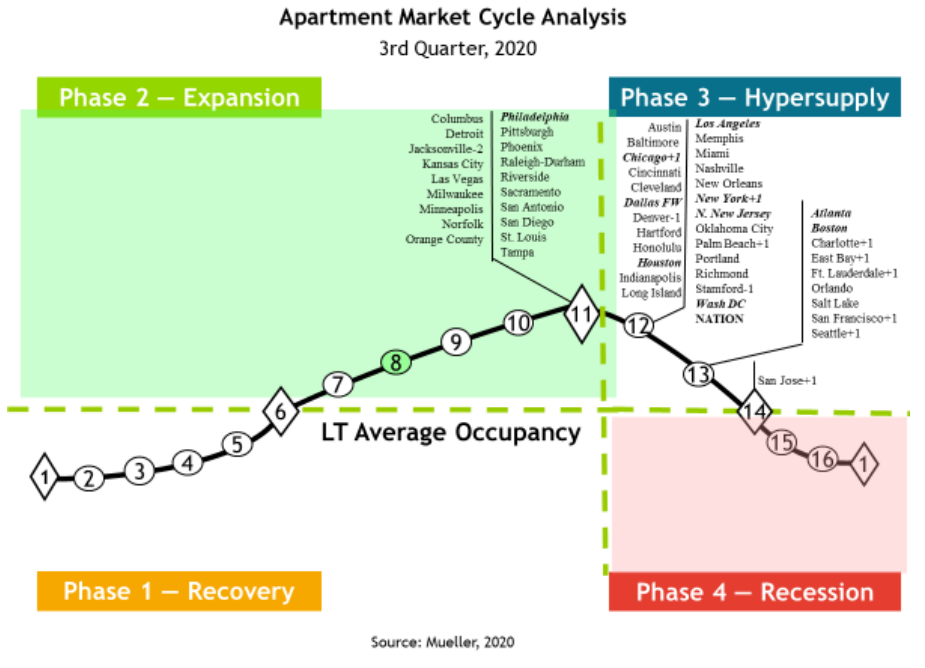
Multifamily property type for various locations is either in the hyper supply phase or close to it, as in the Multifamily Real Estate Market Cycle shown below. Multifamily has been resilient in 2020 with expectations for it to continue the next few years. Deal activity came to a halt for most of 2020 and it is expected to pick up in 2021. An investor will have opportunities to buy, hold, or sell but the asset prices will remain elevated in the hyper supply phase.
Those looking to buy will be faced with high asset prices and thus low returns and cap rates. The key macro-trend to watch is the outward migration from urban and coastal areas to the sunbelt and the limited supply of housing stock.
Our opinion: Multifamily will provide opportunities for all investor types – conservative, moderate, and aggressive. But, investors need to do due diligence at the market, company/operator, and deal level.
Industrial
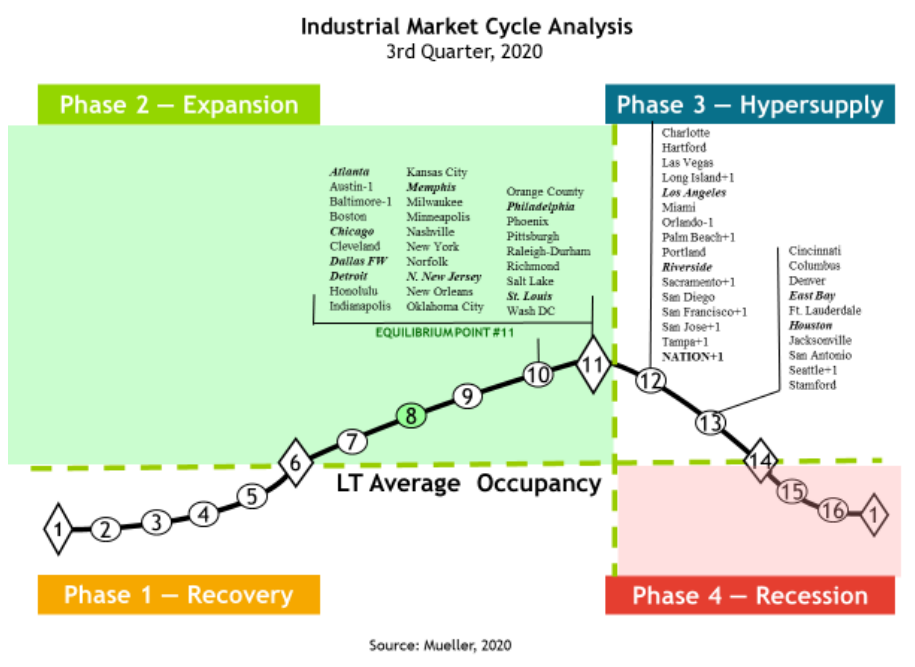
The industrial real estate market cycle looks very similar to the multifamily market cycle. Similar to multifamily, industrial properties have been resilient in 2020 and the eCommerce acceleration has only increased industrial demand. The trends in play are not going to slow down anytime and actually can be expected to increase in the coming years.
Our opinion: Industrial will continue to provide opportunities for all investor types – conservative, moderate, and aggressive. But, investors need to do due diligence at the market, company/operator, and deal level.
Office
The office property type is usually the domain for institutions, but there are some individual investors who invest in smaller suburban offices. Per the Office Market Cycle Analysis, most of the markets are in the expansion phase. This may come across as a surprise to many as offices were hardly occupied in urban areas. Most of the office leases are long-term and hence there hasn’t been a drastic impact on economic occupancy as tenants have continued to pay the rent.
The upcoming quarters need to be carefully watched as many of the urban offices may move into hyper supply or recession. Though the Office Market Cycle looks favorable, we believe it is clouded due to the long term leases. In addition, there are major macro-trends at play like work from home and employer migration to sunbelt states, that makes it risky for conservative and moderate individual investor types.
Our opinion: We do not recommend investing in office for conservative and moderate individual investor types. Aggressive individual investors may leverage distress, adaptive reuse, or contrarian opportunities.
Retail
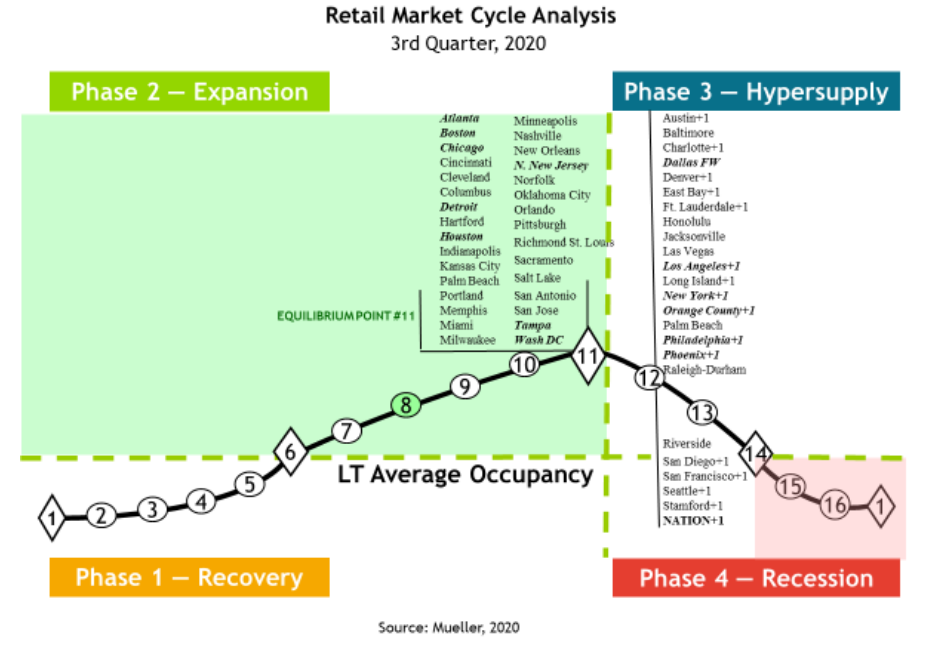
Retail Maret Cycle has been clouded with the underlying macro-trend of the retail “apocalypse” over the past few years as well as COVID-19. Simply put, investing in Retail is for professional and aggressive investors only. It is for the institutional players who can make use of the adaptive reuse opportunities (i.e. convert retail into warehouses or apartments etc.). Quality institutional investors have the scale, capital, and wherewithal to execute adaptive reuse. We can expect some breakthrough innovation and associated rewards in retail, but it is not for the faint of the heart. Retail is not for conservative or moderate investors.
Our opinion: We do not recommend investing in retail for conservative and moderate individual investor types. Aggressive individual investors may leverage distress, adaptive reuse, or contrarian opportunities.
Investor Takeaways
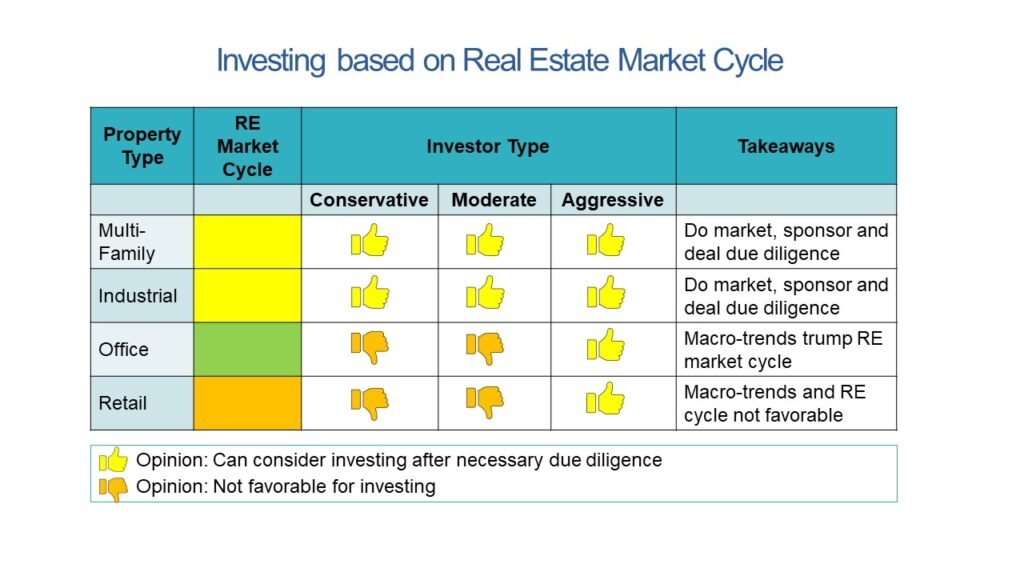
We introduced Real Estate Market Cycle as a great resource to generate or validate CRE portfolio and investment strategy. We looked into the Market Cycle for each property type and our opinion for different types of investors. The following table captures the key takeaways based on the type of investor. Conservative and moderate investors can consider multi-family and industrial property types but stay away from office and retail. Nevertheless, all investors need to do the market, sponsor, and opportunity due diligence.
Source: Prof Mueller’s Q3 2020 Real Estate Market Cycle Analysis; FinYork’s analysis and opinion on secular trends
The CBRE report gives a good lay of the land of the top 30 tech cities. We advise investors to do their own due diligence as we live in a different world in 2020 and growth data from 2018 and 2019 cannot be used as reliable indicators. But, this will give some investment ideas for investors interested in the office space and also where the coveted tech jobs are going. A lot of other property types (for e..g multifamily) also look at cities with a great tech story. For the full report, please visit CBRE 2020 Tech 30.