Tag: investing

  • What Happened to the Cryptocurrency Market on Black Friday?

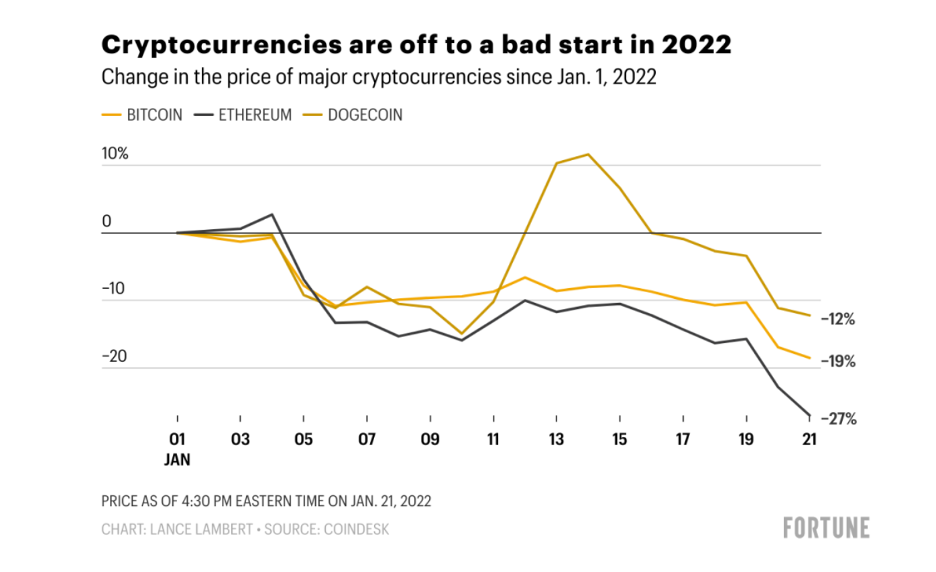
    On a Friday that surely won’t be forgotten anytime soon, on January 21st, 2022, according to CoinMarketCap, cryptocurrencies lost $205 billion in combined market capitalization. Bitcoin was trading at $38,440 as of 10AM Eastern Time on the day many are already calling “Black Friday”. This represents a 16.6% year-to-date drop for the most widely recognized cryptocurrency (Morris, Fortune). Furthermore, Bitcoin has already successfully erased 75% of their gains from 2021 and we’re less than a month into 2022.

    Additional noteworthy cryptocurrencies that suffered substantial setbacks were Ethereum, Solana, and Cardano. Ethereum is especially relevant here, as they received a monumental endorsement from Goldman Sachs in mid-2021. It plummeted 13.5% on Black Friday (-24% YTD), while Solana crashed 16% the same day (-30% YTD), and Cardano dropped 15% (Morris, Fortune). Cardano is also unique since their early gains make their current -8.5% YTD slip seem almost unscathed by comparison.
    Fortune

    Dodgecoin and Shiba Inu, classified as “meme coins”, weren’t exempt from the carnage either, falling 10% and 13%, respectively (Shrivastava, Yahoo Finance). According to CoinMarketCap, judging by overall market cap, they are by far the two largest meme coins. With that, let’s dig into the question investors around the world are actively pondering; what happened?

    Russia’s Central Bank Proposed a Cryptocurrency Ban

    Let’s start with the most obvious. On Black Friday, Reuters reported Russia, one of the world’s largest economies the third-largest Bitcoin miner in the world, proposed banning the use and mining of cryptocurrencies via their central bank. This is eerily similar to a move China pulled at the end of May 2021. We similarly witnessed Bitcoin and other major crypto’s suffer short-term dips, while quickly rebounding in the immediate weeks that followed.

    Russia’s central bank argued cryptocurrencies pose a substantial threat to the country’s financial stability. Additionally, they highlighted reasons pertaining to citizens’ wellbeing and its monetary policy sovereignty (Reuters). Ultimately, Russia’s central bank didn’t mince words, concluding with:

    “The best solution is to introduce a ban on cryptocurrency mining in Russia”

    -The Central Bank of Russian Federation (CBR)

    What’s lacking coverage right now is Russia has been arguing against cryptocurrency adoption for years. Russia’s been extremely vocal in raising concerns about the ease of cryptocurrency markets being used for money laundering and even financing global terrorism. It wasn’t until 2020 that they were given legal status, despite still being banned as a means of payment.

    Specific to events that unfolded on Black Friday, Russia’s central bank focused heavily on the long-term stability of cryptocurrencies. To be blunt, it tore them apart. The central bank determined their rapid growth was reflective of potentially perilous instability. Essentially, the central bank issued stern warnings of the cryptocurrency market being one enormous bubble. They went so far as to indicate cryptocurrencies carried similar characteristics to a financial pyramid.

    Large Market Liquidations Led by Bitcoin

    As one would expect, Black Friday was one of the highest ever single-day cryptocurrency liquidations. The significance of losing a combined $205 billion in market capitalization over a 24-hour period cannot be underscored. Leading that effort was Bitcoin, with Ethereum not far behind. The two lost over $281 billion and $207 billion in 24 hours, respectively.

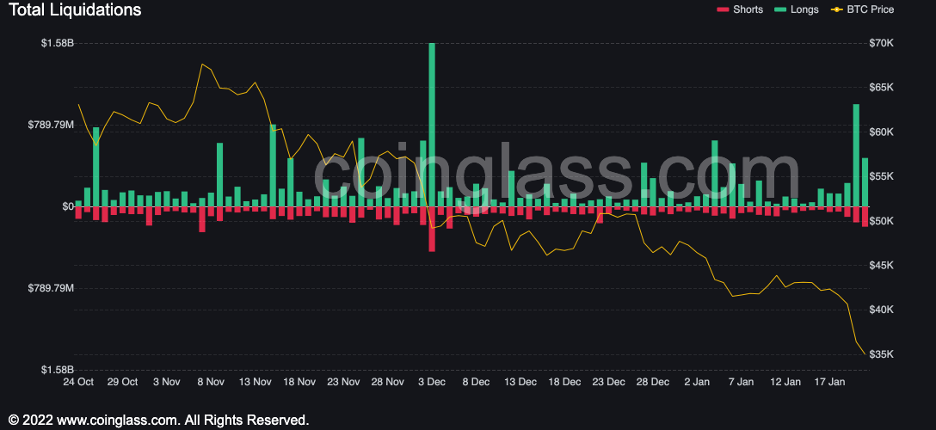
    The below chart, derived from CoinGlass Liquidation Data, does an excellent job in illustrating how Bitcoin’s price is impacted by investors taking a short position on crypto’s. As investors begin to show skepticism, it appears Bitcoin (BTC) begins to snowball downwards at an increasing rate.
    CoinGlass

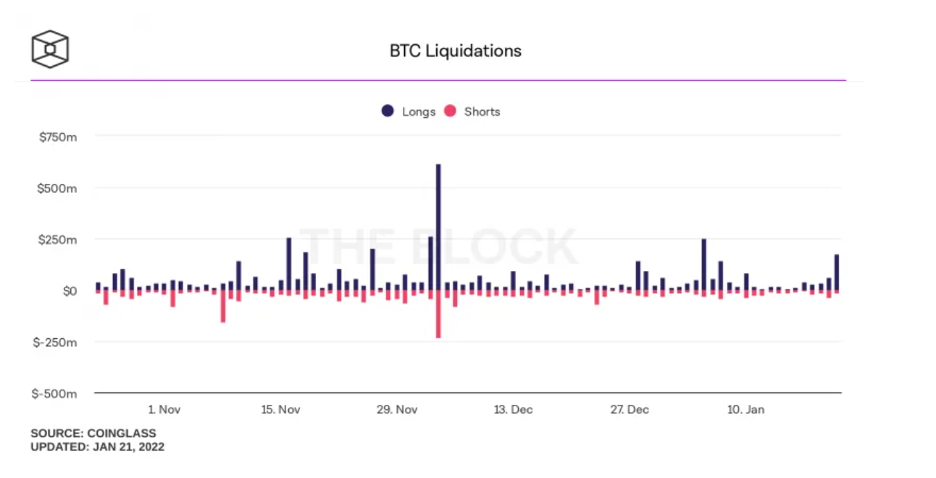
    As the largest and most well-known cryptocurrency, historically Bitcoin’s performance dictates the overall crypto market trend. The same proved to be true on Black Friday.
    CoinGlass/Yahoo Finance

    Wall Street’s Weak Overall Weekly Performance

    Looking to recent history again, the US stock market performance has had a direct relationship with the crypto market’s performance. Before Black Friday, the S&P 500 Index (SPX) dropped nearly 4% over the course of 72 hours (Shrivastava, Yahoo Finance). When this was covered in real-time by Yahoo Finance, MacroAxis’ model had a maximum correlation of 0.59 between BTC and SPX. This is considered a significant correlation. The macroeconomic models from MacroAxis now show an existing correlation as high as 0.64, a stunning daily increase.

    While Russia’s central bank is undeniably the primary catalyst, Bitcoin’s rapid liquidation created an expected snowball effect. That made for terrible timing for historically safe, reliable US stock market investments to have a noticeably subpar week. Many investors, who were already feeling the pressure of safer investments in their portfolio losing value, were put in an even more precarious situation with their more speculative investments nosediving, causing many to quickly liquidate before further damage was done.

    Unsurprisingly, what’s next for Bitcoin and the cryptocurrency market is continuing to be widely debated. Multiple highly credible analysts and institutions remain firmly bullish, claiming Bitcoin will surpass $100,000. While a very wide network of high-net-worth individuals and financial giants still backing Bitcoin and crypto’s exists, it’s hard to imagine we won’t see another rebound yet again.
  • What Happened to the Cryptocurrency Market on Black Friday?

    On a Friday that surely won’t be forgotten anytime soon, on January 21st, 2022, according to CoinMarketCap, cryptocurrencies lost $205 billion in combined market capitalization. Bitcoin was trading at $38,440 as of 10AM Eastern Time on the day many are already calling “Black Friday”. This represents a 16.6% year-to-date drop for the most widely recognized cryptocurrency (Morris, Fortune). Furthermore, Bitcoin has already successfully erased 75% of their gains from 2021 and we’re less than a month into 2022.

    Additional noteworthy cryptocurrencies that suffered substantial setbacks were Ethereum, Solana, and Cardano. Ethereum is especially relevant here, as they received a monumental endorsement from Goldman Sachs in mid-2021. It plummeted 13.5% on Black Friday (-24% YTD), while Solana crashed 16% the same day (-30% YTD), and Cardano dropped 15% (Morris, Fortune). Cardano is also unique since their early gains make their current -8.5% YTD slip seem almost unscathed by comparison.

    Fortune

    Dodgecoin and Shiba Inu, classified as “meme coins”, weren’t exempt from the carnage either, falling 10% and 13%, respectively (Shrivastava, Yahoo Finance). According to CoinMarketCap, judging by overall market cap, they are by far the two largest meme coins. With that, let’s dig into the question investors around the world are actively pondering; what happened?

    Russia’s Central Bank Proposed a Cryptocurrency Ban

    Let’s start with the most obvious. On Black Friday, Reuters reported Russia, one of the world’s largest economies the third-largest Bitcoin miner in the world, proposed banning the use and mining of cryptocurrencies via their central bank. This is eerily similar to a move China pulled at the end of May 2021. We similarly witnessed Bitcoin and other major crypto’s suffer short-term dips, while quickly rebounding in the immediate weeks that followed.

    Russia’s central bank argued cryptocurrencies pose a substantial threat to the country’s financial stability. Additionally, they highlighted reasons pertaining to citizens’ wellbeing and its monetary policy sovereignty (Reuters). Ultimately, Russia’s central bank didn’t mince words, concluding with:

    “The best solution is to introduce a ban on cryptocurrency mining in Russia”

    -The Central Bank of Russian Federation (CBR)

    What’s lacking coverage right now is Russia has been arguing against cryptocurrency adoption for years. Russia’s been extremely vocal in raising concerns about the ease of cryptocurrency markets being used for money laundering and even financing global terrorism. It wasn’t until 2020 that they were given legal status, despite still being banned as a means of payment.

    Specific to events that unfolded on Black Friday, Russia’s central bank focused heavily on the long-term stability of cryptocurrencies. To be blunt, it tore them apart. The central bank determined their rapid growth was reflective of potentially perilous instability. Essentially, the central bank issued stern warnings of the cryptocurrency market being one enormous bubble. They went so far as to indicate cryptocurrencies carried similar characteristics to a financial pyramid.

    Large Market Liquidations Led by Bitcoin

    As one would expect, Black Friday was one of the highest ever single-day cryptocurrency liquidations. The significance of losing a combined $205 billion in market capitalization over a 24-hour period cannot be underscored. Leading that effort was Bitcoin, with Ethereum not far behind. The two lost over $281 billion and $207 billion in 24 hours, respectively.

    The below chart, derived from CoinGlass Liquidation Data, does an excellent job in illustrating how Bitcoin’s price is impacted by investors taking a short position on crypto’s. As investors begin to show skepticism, it appears Bitcoin (BTC) begins to snowball downwards at an increasing rate.

    CoinGlass

    As the largest and most well-known cryptocurrency, historically Bitcoin’s performance dictates the overall crypto market trend. The same proved to be true on Black Friday.

    CoinGlass/Yahoo Finance

    Wall Street’s Weak Overall Weekly Performance

    Looking to recent history again, the US stock market performance has had a direct relationship with the crypto market’s performance. Before Black Friday, the S&P 500 Index (SPX) dropped nearly 4% over the course of 72 hours (Shrivastava, Yahoo Finance). When this was covered in real-time by Yahoo Finance, MacroAxis’ model had a maximum correlation of 0.59 between BTC and SPX. This is considered a significant correlation. The macroeconomic models from MacroAxis now show an existing correlation as high as 0.64, a stunning daily increase.

    While Russia’s central bank is undeniably the primary catalyst, Bitcoin’s rapid liquidation created an expected snowball effect. That made for terrible timing for historically safe, reliable US stock market investments to have a noticeably subpar week. Many investors, who were already feeling the pressure of safer investments in their portfolio losing value, were put in an even more precarious situation with their more speculative investments nosediving, causing many to quickly liquidate before further damage was done.

    Unsurprisingly, what’s next for Bitcoin and the cryptocurrency market is continuing to be widely debated. Multiple highly credible analysts and institutions remain firmly bullish, claiming Bitcoin will surpass $100,000. While a very wide network of high-net-worth individuals and financial giants still backing Bitcoin and crypto’s exists, it’s hard to imagine we won’t see another rebound yet again.

  • New York City’s Housing Market Finishes Strong in 2021; Slowdown Expected in 2022?

    New York City’s residential real estate market closed 2021 with many arguing it had the strongest performance in three decades. By mid-October, Manhattan contract signings already surpassed the previous record, which was 12,520 in 2013 (UrbanDigs). With a little under two weeks left in 2021, closings reached 14,774 (Cavanaugh, TheRealDeal). Already, that’s more than double the 2020 total. Despite a rise in listings, that level of closings undoubtably depleted inventory. Are we heading towards a residential real estate market slowdown in NYC in 2022?

    UrbanDigs found that through December 5th, 2021, listings had exceeded the 2008-2018 average by 18%. Net new inventory – the number of monthly new listings, minus contracts signed and listings taken off-market – surprised many market experts. Astonishingly, buyers bought out the increased supply at an even faster pace. Net new inventory dropped below zero in 9 of 11 months during 2021, to negative 861 units (Cavanaugh, TheRealDeal).

    For buyers, prices have steadily risen in tandem. For the first time since 2015, listing discounts fell consistently throughout the year, even as buy-side competition increased. The luxury market, considered properties with a selling price of $4M and up, had the best year since 2014 (UrbanDigs). Buyers spent over $14B so far and with less than a couple weeks left in 2021, this represents a 19% increase over the previous record of the last three decades (UrbanDigs).

    Even with the residential housing market’s red hot 2021 performance, UrbanDigs co-founder John Walkup does not have nearly the same forecast for 2022.

    “Deal volume may slow through the holiday season, especially with fewer units coming to market”

    -John Walkup, Co-Founder of UrbanDigs

    He continued with stating he feels the next quarter could be noticeably slower than Q4 of 2021.

    “A slowdown in buy-side activity may cause inventory levels to rise, pressuring prices”

    -John Walkup, Co-Founder of UrbanDigs

    Furthermore, he predicted a “multi-quarter lull in 2022” for the luxury market.

    Walkup’s predictions for 2022 aren’t exactly universally accepted by known residential real estate experts. Jonathan Miller, President and CEO of Miller Samuel, had a different sentiment in his latest report for Douglas Elliman. Miller sees deals in Manhattan and Brooklyn continuing to outpace listings heading into 2022, as they have closing 2021. His report cautions real estate market participants not to be surprised if there isn’t as noticeable a slowdown in 2022.

     “Inventory is continuing to collapse, and that’s why we anticipate continued price growth into the new year”

    -Jonathan Miller, President & CEO of Miller Samuel

    According to the Wall Street Journal (WSJ), the Federal Reserve may hike interest rates as early as March 2022. Walkup believes this could “put an upper bound on condo prices, with luxury and new development prices falling first”. Simultaneously, Walkup assured the luxury lull will be “nothing too drastic”, estimating discounts maxing out at 5%.

    In a peculiar comparison, the WSJ noted that condos, as an asset class, lag behind the exceptional performance of the S&P 500 Index (Joe Wallace, Wall Street Journal). The S&P hit a 67th record high in the third to last week of 2021 (Alexander Osipovich, Wall Street Journal). Since the 2008 US financial collapse was largely related to assets and various securities in the housing market, it’s not surprising during that time, both the stock market and the value of real estate took a hit as a result (Cavanaugh, TheRealDeal). UrbanDigs found that since January 2008, the S&P increased 230%, while the price per square foot of a new Manhattan condo rose 68%.

    “The frothy activity observed in the NYC real estate market since the reopening has yet to translate into anything approaching the gains seen on the broader equity index”

    -John Walkup, Co-Founder of UrbanDigs

    While that may be true, you cannot live in an index, or any stock portfolio.

    Interest rates could also be a major influencing factor for foreign investment. Should the Fed raise rates, this would further strengthen the USD, which already surged to a 16-month high in November 2021 according to Barron’s. As a result, this places buyers with wealth in other countries in a disadvantageous position. So much so, Walkup pontificates, that this will dissuade foreigners from buying US real estate. Instead, Walkup believes they are likely to liquidate their current holdings. He goes on to state, “2022 could be the year of the foreign sellers”.

    In anticipation of the opposite, NYC brokers geared up for an influx of foreign buyers, ahead of travel bans being lifted from 33 countries in November 2021. The increasing prevalence of the Omicron variant is heavily pushing a slowdown on that effort. Nonetheless, a rebound of residential real estate in overseas markets suggests foreign investor fears may be receding.

    “On the whole, I think travel bans take a back seat to [profit and loss] statements. So whereas a lifted travel ban could certainly stimulate some activity, if NYC investment returns are viewed as less than optimal due to currency fluctuations or price volatility, foreign buyers will look elsewhere.”

    -John Walkup, Co-Founder of UrbanDigs

    On a more granular level, Walkup expects continued strong townhouse demand and a renewed interest in “fixer-uppers”. Compared to the 2008 – 2018 average, in 2021 average monthly sales volume of Manhattan townhouses rose by nearly 50 percent. Walkup feels the market will likely remain hot, as buyers continue pursuing space and privacy, inspired by the COVID-19 pandemic. He sees sales and prices continuing to rise, as more homes are snapped up, thereby depleting inventory.

    The demand for renovated units, however, could be ebbing (UrbanDigs). In October 2021, UrbanDigs released a report outlining a roughly 30 percent divide between prices of renovated units and “fixer-uppers”. The prevailing theory seems to be supply chain problems, with labor shortages and rising material costs being the main catalysts. This helps explain why a very substantial block of buyers opted to avoid properties requiring extensive renovation.

    Walkup said in 2022, the spread between renovated and unrenovated units has potential to narrow. Increasingly tightening supply compels buyers to opt for units in need of some TLC. All-in-all, especially considering NYC has remained a historically hot buyer’s market when it comes to residential real estate throughout all of 2021, it’s too early to truly predict what 2022 will bring. The Omicron variant’s spread throughout the US, as well as the world, will surely have an impact. Other external economic factors will continue to impact NYC’s housing market as well, as all eyes are on the Fed. If and when the Fed chooses to hike up rates, investors should expect the entire landscape of residential real estate in NYC, as well as the entire United States, to change.  

  • Inflation is Rising, What About Housing Prices?

    Prices are rising, nearly universally. Inflation appears to be increasing at an increasing rate.

    Just about all credible economists are continuing to signal the inflation warning bells, with consumers continuing to pay more for everyday necessities, such as food and gasoline (Fox, CNBC). While we’re yet to see substantive, broad housing price increases, many believe we’re going to. 

    “With inflation rising so aggressively and the fact that people’s salaries and weekly income are not rising at the same rate, we end up with less discretionary money to spend each month”.

    -George Ratiu, Manager of Economic Research at Realtor.com

    Rising Home Prices

    To be clear, home prices have began to rise as well. The CPI (Consumer Price Index), which measures the cost of goods and services, shows that shelter [housing] rose 0.5% in October (Olick, CNBC). The CPI takes into account both rent prices and approximate prices homeowners would receive in hypothetical rent payments.

    Separately, it’s critical to note one month almost never gives any sort of definitive indication. However in August 2021, home prices were up 19.8%, a staggering increase (S&P CoreLogic Case-Shiller Indices). Nothing is definite yet, but renters would be wise to begin lowering their other budgetary expenditures. First and foremost, you will have less disposable income every month since you’re paying higher prices. However secondarily, according to Realtor.com, we’re also seeing mortgage rates climbing. Compared to a year ago, buyers are now spending on average $160 more a month on mortgage payments. Many experts believe those rates will continue to climb.

    “Generally as we see inflation go higher, we are going to see mortgage rates go higher”.

    -George Ratiu, Manager of Economic Research at Realtor.com

    Hedging Against Inflation

    Historically, real estate has largely been viewed as a hedge against inflation. With a mortgage, you lock in a fixed monthly payment for the term of the loan, which is definitely long-term. In turn, this shields you from sharp volatility in prices. Additionally, home values have traditionally at least kept up with inflation (Cox, CNBC).

    “Homes are expensive now … but for most people the comparison that is most important is how that cost of home ownership is going to compare to the cost of renting”.

    -Jeff Tucker, Senior Economist for Zillow

    Of course, rent is more unpredictable than locking in a fixed mortgage monthly payment. Over the course of your mortgage repayment, rent prices are almost certain to go up.

    “If wages are rising or if the cost of building materials and appliances and light bulbs and paint is rising, all of these to some extent will flow into the cost of maintaining and building rental homes”.

    -Jeff Tucker, Senior Economist for Zillow

    Furthermore, as seasoned investors are aware of, supply and demand often dictates housing market prices. According to CoreLogic, demand rose 10.2% nationally in September 2021 compared to where it was in 2020. On the flip side, a Realtor survey of 1,300 homeowners from fall 2021 found 26% plan to sell their home within the next 12 months. This figure is more than double the percentage of their same March 2021 survey. Overall, the consensus appears to be buying over renting, so long as you can afford it.

    “Historically, you are likely to get some of the best bargains of the year. I think 2022 has the promise of providing less competition, a lot more homes to choose from and, as a result, a lot more approachable prices”.

    -George Ratiu, Manager of Economic Research at Realtor.com

    At the same time, you may want to reconsider talking yourself into buying a home based on price alone.

    “The house is the place where your family is going to live every day”.

    -Jeff Tucker, Senior Economist for Zillow
  • What America’s Past in Real Estate Tells Us About the Future

    Some experts have argued that we’re at a torrid time in the future of the US real estate market. Others have argued NYC’s housing market has been roaring, with no sign of slowing down. With inflation continuing to cripple the value of the USD, prospective home buyers face pressure to invest in tangible assets. Many Americans are realizing a home is the most sensible shelter for their savings (Nguyen, Forbes).

    However, home supplies in coveted markets are scarce. Prices are ever-climbing and competition for homes is currently relentless. That’s generally where America’s market currently stands. The main question on the minds of homeowners and prospective buyers continues to be: “Where will markets go from here?”

    Of course, no one can say with certainty. Nevertheless, select lessons from America’s history provide a blueprint for home buying at this unique historical juncture.

    Lesson from the Great Depression

    Principally, you cannot separate the national economy from the nation’s housing markets. The American economy and the American housing market are akin to dominos aligned in the same row. On some occasions, the economy is the domino at the front of the row. Whereas there were other times – the subprime mortgage crisis (Great Recession, 2008) – the housing market is first in line.

    Arguably no time in American history better exhibits the inextricable link between national economic performance and the American people’s ability to both purchase, as well as hold onto, long-term houses. As the stock market crashed in 1929, bank runs quickly ensued, and mass unemployment followed closely behind. A staggering 273,000 Americans lost their homes in 1932, plus even more suffered foreclosure in the following year. Americans simply did not have the wherewithal to keep up with mortgage payments when crushing stagflation hit.

    Some things have not changed since the onset of the Great Depression. Americans today have become far more cognizant of a future possibility of widespread economic downturn. An economy in contraction means jobs lost, wages uncollected, and mortgage payments undelivered. Ultimately, this means foreclosures.

    Current Home-Buying Spree Continues

    Yet, even facing economic hardship triggered by the pandemic, America finds itself in the midst of a record home-buying spree. This may suggest any of the following three (Nguyen, Forbes):

    • A new segment of Americans (including former apartment-dwelling city residents) are injecting unprecedented capital into newfound housing markets.
    • Home buyers see houses as a sound investment, even as many expect the economy to take a turn for the worse.
    • The demand for homes in America is far greater than supply, increasing competition for each home.

    On one hand, the Great Depression is a necessary reminder for prospective home owners to not purchase beyond their means. However, many who lost their homes during the Great Depression certainly weren’t living lavishly. This is a critical takeaway – though one we must extract – from the hardships of the late 1920s and 1930s.

    Moreover, there are notable differences between 1930’s America and 2021, which bode favorably for today’s housing market. Incentive-laden tax policies, enacted since the Depression, made it more affordable to purchase homes and make the requisite mortgage payments. Today, Americans have a variety of investment options to mitigate risk. Additionally, federal policy has prevented bank failures from the magnitude witnessed during the Great Depression.

    Lesson from the GI Bill (1944)

    Concisely, cheap credit can set you up for life (Nguyen, Forbes). If you’ve been relishing your prevailing 3% interest rates, prepare for disappointment (by comparison).

    Not long after the Allied invasion of Normandy Beach, US President Franklin Roosevelt signed the GI Bill (1944). The was portrayed as a token of appreciation to a generation of young Americans, who risked their lives at war. Upon returning home, those GIs received government-backed loans that all but guaranteed homeownership, amongst other benefits. Banks the US government deemed a guarantor were overwhelmingly likely to approve a mortgage application.

    With access to such favorable loan conditions, veterans went on to purchase 20% of all homes built after the war. GIs took full, absolute advantage of the easy credit they undeniably earned.

    Fast forward to the present. While a government-guaranteed loan might sound ideal, you truly cannot complain about today’s prevailing 3% interest rates (Campisi, Forbes). To compare, interest rates topped 17% in 1982, then hovered around 10% for significant periods in the 1990s. That means two decades ago, you’d have to pay 8% for a home loan. Quite staggering compared to today’s housing market climate, to say the least.

    To reemphasize, the prime takeaway from the GI Bill, is that favorable credit should be pounced on, while it’s available. Historically, the sub-3% rate, which we’ve seen for the vast majority of 2021, is a statistical anomaly. Based on the frenzy of home buying we’ve witnessed, it seems that many Americans and foreign investors know their history. Perhaps much more than some casual real estate investors may think.

    Conclusion

    Seemingly, the two monumental American national economic events discussed provide opposing lessons for today’s prospective home buyer. The sudden, near-total crash of the Depression-era housing market reminds us the importance of consumer’s buying within their means. The GI Bill reinforces the importance of closing on a home, especially while lending terms are favorable. Upon extensive examination, these lessons can be very much complimentary in the future.

    As we’ve noted, today, Americans find themselves at a confounding point. Interest rates are very favorable; however, the economy is riddled with inflationary concerns and general uncertainty. It’s a time both reminiscent of GI Bill-era opportunity and Depression-era anxiety (Nguyen, Forbes).

    Of any lesson investors should takeaway, it’s this: you can embrace the benefits of comparatively cheap credit while remaining within your spending means. Be sure you don’t miss out on a prime real estate investment, while interest rates are so favorable. Stray away from overextending yourself to the point where you cannot keep up with future payments, should times get tough.

    For strategically sound real estate investing, you must look to the past to help predict the future. If nothing else, for guidance. That includes the better parts, but perhaps even more importantly for investors, the worse.  

  • How to Best Invest in Real Estate in the Midwest

    The most surprising feature about housing markets in the Midwest is that home prices – in most of them – are still below the level where local incomes dictate they should be (Winzer, Forbes). If you’re a real estate investor, this means two things. Firstly, there are bargains still available in these markets. Secondly, demand for housing not been very strong, at least not yet.

    Midwest Housing Market Overview

    The lack of rebound in the Midwest housing market following 2008 is largely due to the specific types of local economic growth that prevailed before that (Winzer, Forbes). The housing recession came coupled with a lengthy, slow decline in manufacturing. The availability of an educated but low-cost labor force had encouraged the growth of big financial operations in Des Moines, Minneapolis, Omaha, Sioux Falls and Green Bay. However, manufacturing still has a large role in Fayetteville, Davenport, Peoria, Rockford, Gary, Fort Wayne, South Bend, Wichita, Milwaukee and Green Bay (Millsap, Forbes).

    This makes these markets a bit riskier to invest in. The markets with a large finance sector are also risky because automation is responsible for an increasing amount of work. Despite structural problems, growth is now returning to many Midwest markets, as it did prior to COVID-19. Especially in areas that function as regional centers – Fayetteville and Peoria, for example – the expansion of jobs is due to an increase in healthcare and business services. Similarly, to the country, these services are becoming concentrated in large urban centers, creating opportunities for investors in rental housing.

    An uncharacteristic feature housing investors contend with is many Midwest markets have agricultural roots, with manufacturing later added on top. Since land was readily and easily available during their growth, they tend to be spread out. This combination produces low home prices, but increased difficulty for investors to select a locality. After all, the saying “real estate is about location, location, location”, rings true in most cases.

    Now that we’ve established some fundamental generalities, let’s get to the specifics and numbers.

    Established Demand

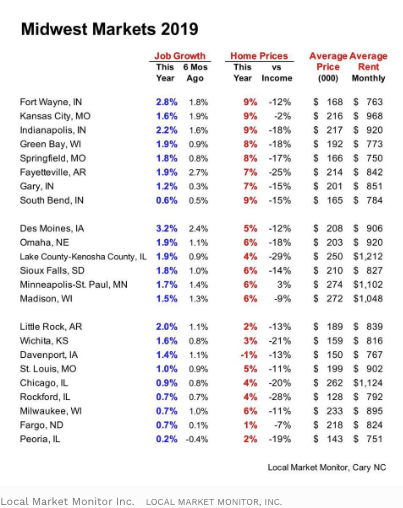
    Fort Wayne, Kansas City, Indianapolis, Green Bay, Springfield, Fayetteville, Gary and South Bend.

    In these markets, it appears home prices increased relatively broadly in the past year, indicating good demand not just for single-family homes, but rentals as well. With prices still well below income levels and above average job growth, demand is likely to keep raising prices higher. Though the trend depicted below shows the housing market pre-COVID, that trend is pretty much identical today. The housing market didn’t really suffer the same volume of consequences as other markets, but the small parts that did are steadily recovering (Winzer, Forbes).

    Source: Local Market Monitor, Inc.

    South Bend and Gary are at the bottom of this list because their job growth had been less reliable. Before bargains evaporate, investors should move quickly into these markets. Straight, single-family rentals – with minor improvements – are the best bet (Winzer, Forbes).

    Growing Demand

    Des Moines, Omaha, Lake County-Kenosha County, Sioux Falls, Minneapolis, Madison.

    These markets are showing solid job growth, but only moderate increases in demand thus far. Apartments appear to be a good investment in Lake County-Kenosha County and Minneapolis, due to higher density and prices. Since their dependence on the financial sector is comparably very high, most of these markets are also slightly riskier, so investors should be very careful to find properties towards the middle of the renter pool and definitely avoid the higher end.

    Uncertain Demand

    Little Rock, Wichita, Davenport, St. Louis, Chicago, Rockford, Milwaukee, Fargo, Peoria.

    In these markets either demand or job growth are weak, or even more likely, both. Low home prices are also far more commonly found in these markets. This may tempt investors to purchase a low-cost property and rent it out for cheap, without spending another dime. However, renting at the low-end is a specialty that most investors should avoid. In uncertain real estate markets, it makes sense to first look for the safest geographic areas in that market. Then you can perhaps expand and renovate a really inexpensive property, turning it into a profitable rental. That definitely involves more work, but it has potential to give you a bigger return for less risk.

    The Bottom Line

    Concisely, there’s clearly room for excellent returns on housing market investments in the Midwest. While some areas have more opportunity, depending on what strategy you choose, there’s solid return on investment potential all-around. The more time that passes from the start of the COVID-19 pandemic, the less attractive prospects will exist. Active real estate investors would be wise to look strongly into the Midwest and move quickly on specifically the kinds of properties with the features described above. Considering the housing rental market is excellent and still growing, there are definite, safe strategies to fall back on.

  • What is a Private Equity Real Estate Fund?

    In the simplest terms, a real estate private equity fund is a partnership established to raise equity for ongoing real estate investments (Bond, NAIOP). A general partner (GP), most frequently referred to as the “sponsor”, creates the fund. The sponsor asks investors, known as limited partners (LPs), to invest equity in the fund or partnership. Those funds, along with money borrowed from commercial banks, investment banks, public institutions, asset managers, and other lenders, are supposed to be invested in a variety of real estate development or acquisition opportunities.

    Typically, the LPs provide the bulk of the equity capital and are passive investors, who have actively chosen to invest in an offering, which was presented by the sponsor. LPs earn an early return of capital and a preferred return on capital invested (Bond, NAIOP). Sponsors are in charge of providing the equity capital, securing investment opportunities, managing the real estate and the fund, and earning fees (that typically are based on performance).

    A real estate private equity fund differs from capital that comes from friends and family and joint ventures. A differentiating example of a joint venture could be among a landowner, a developer, and a money partner. None could complete the investment without the others, and the joint venture is specific to just one investment. Real estate private equity funds, on the other hand, are created to invest in a series of deals with a standardized risk and reward structure created for the overall fund in which the sponsor and LP participate unequally (Bond, NAIOP).

    What are the Sponsor’s Motivations?

    While there are arguments for a laundry list of motivations, we’ll highlight the general motivating factors for sponsors.

    • Diversify and expand funding sources, as well as holdings

    A sponsor with a pipeline of potential investments can use a fund to take advantage of a portfolio consisting of a variety of deals that would not otherwise be available. The capital-raising strategy should, however, focus on the sponsor’s history, the experience of the team, the potential for returns, alignment of interests and clearly identified opportunities. The most reputable developers with the best track records are able to find investment opportunities in their home markets that are outside their traditional property type focus, opportunities outside their historical geographic focus, or some combination of both (Bond, NAIOPI). A private equity fund has the potential to provide the scale that will allow the sponsor to fully take advantage of these opportunities, thereby generating returns over a much larger capital base and likely even lowering the risk of the firm.

    • Invest in larger and higher quality projects

    A sponsor that has capital constraints can use funds to invest in larger and more complex projects. Conversely, more partners also enable the developer to share the risks with their investors to create a better risk-return balance on large, complex projects that the sponsor would not be able to take on alone.

    • Obtain better terms from banks and other lenders.
    • Provide an alternative to mezzanine capital.
    • Develop projects using fund-level financing in lieu of project-by-project financing.
    • Earn fees from the fund, including a promoted interest. 

    The “Three Key” Considerations to a Private Equity Real Estate Fund

    While an argument could be made for a myriad of factors that are critical to take into account when setting up a private equity fund, three key considerations standout. These are pillars to success in establishing the fund and efficiently raising capital from the limited partners.

    1) Amount of Equity Capital to Raise

    The first consideration is the amount of equity capital that ought to be raised. This should include organizational fees. The minimum private equity fund size is generally considered to be $20 million. While organizational costs are generally proportional to fund size, the floor for organizational fees is about $400,000. While the sponsor recoups these fees from the fund once the capital is raised, the sponsor must carry these costs during the fund’s formation period. Examples of these costs include: formation costs for the legal entity or entities, filing fees, accounting fees, regulatory brokerage costs, clearing costs and the cost of producing marketing documents (Bond, NAIOP).

    While the fund’s equity capital is typically combined with debt capital to create a total pool for investing, a successful fund needs to balance potential deal flow with the fund’s size to ensure that the fund can produce sustainable returns for the LPs, and that it doesn’t become too small, such that a follow-on fund might need to be launched. The timing of flows to and from the fund should also be considered. In general, LPs begin earning a preferred return on their capital as soon as the funds are invested. Therefore, in addition to obtaining a commitment from each LP for the total investment amount, astute sponsors stage the pay-in to match the fund’s anticipated timing of investments.

    2) Realistic Amount of Time, Energy, and Seed Funding Required

    Sponsors must be clear-eyed about the time, energy and seed funding required to launch a fund (Bond, NAIOP). The sponsor is responsible for all aspects of the fund: organizing the fund, which includes generating a partnership agreement, offering and subscription documents; securing investment opportunities; securing loans and other financing; managing the fund; operating the properties; preparing partners’ tax returns; and responding to accounting and audit matters, and this is to name only a few of the highlights. These responsibilities put the sponsor is under a constant, daunting amount of pressure. You may have the financial acumen, but you may not have other traits essential to being a successful sponsor.

    3) Clear Investment Fund Strategy

    It’s imperative for sponsors to have a clear and easily understood investment fund strategy. This differs from the market fundamentals, property type, and location strategies that dominate traditional real estate investing assessments. Though experienced sponsors and the largest funds may be able to raise funds for a “blind pool” – a fund for which no individual investments are identified – first-time sponsors typically must identify specific investments that are included in the fund’s offering memorandum.

    Concisely, there’s a lot of complexity to operating or owning a private equity fund that we didn’t get to. However, our goal was to cover the core basics. What is a private equity fund, how is it set up, and what are the key takeaways? We hope this piece was helpful and educational for those interested in private equity.